
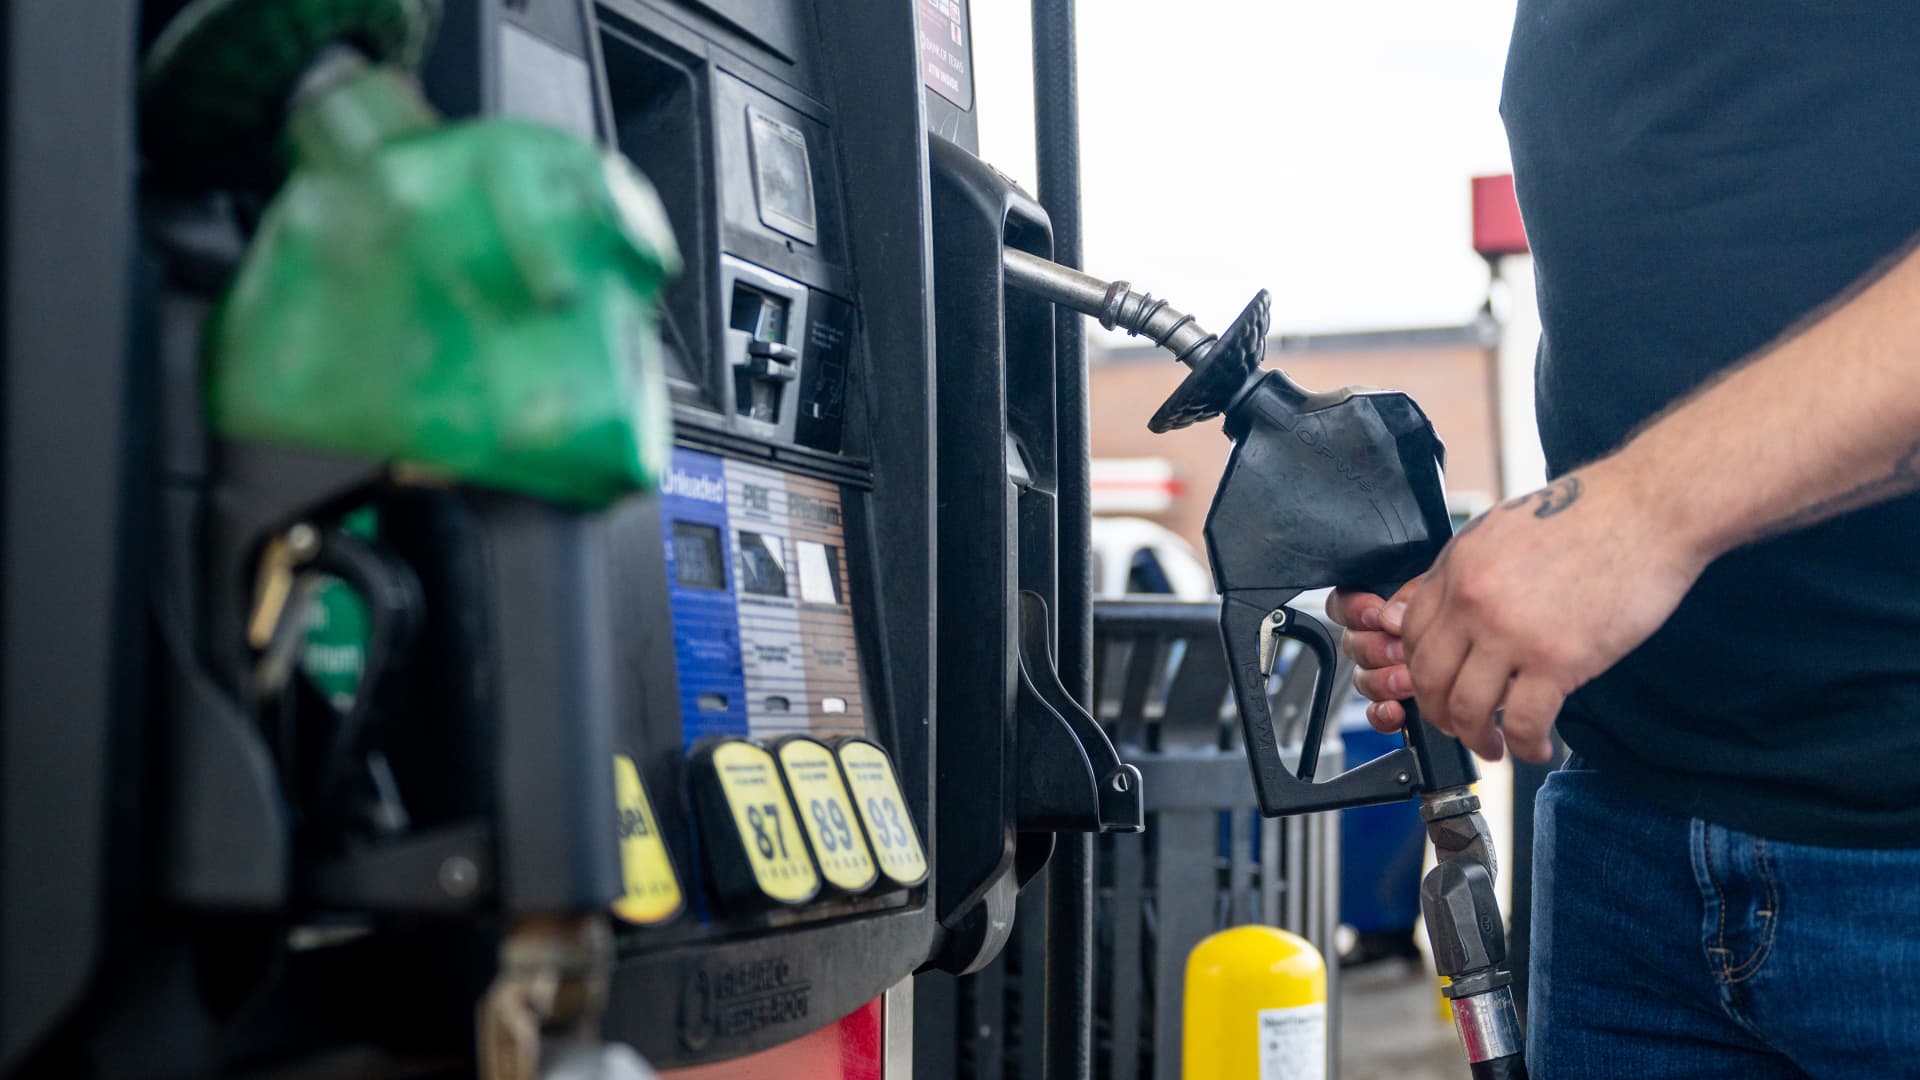
A person finishes filling up with gas at a QT gas station in Austin, Texas, on September 24, 2026.
Brandon Bell | Getty Images
If anyone at the Fed is looking for evidence against raising rates again, they are unlikely to get it in the statistics released Wednesday that are expected to show ongoing price pressures and consumers continuing to spend despite them.
The Personal Consumption Expenditure Price Index, a key inflation measure for central bank policymakers, is expected to show a 0.3% rise at both the all-items and core level, the latter not including food and energy costs, according to the Dow Jones Consensus.
On an annual basis, price levels are expected to rise 3.7% and 3.3%, respectively, unchanged from July and still well above the Fed’s 2% target.
In other words, there is little sign that inflation will abate anytime soon.
“I think the Fed will look at this and say, ‘The core isn’t moving. We don’t have any hope or reason to believe that it’s going to start to fall in a convincing way,'” said Dan North, senior economist at Allianz Trade. “It’s still well above target…so I think it’s really built into it so much that the Fed can’t ignore it or explain it away.”
Fed officials approved a quarter-point rate hike at their September meeting and specified the possibility of further hikes by the end of the year. All but two of the 18 Federal Open Market Committee members who provided forecasts raised their consensus PCE inflation outlook, saying they expect at least one more move in 2026.
Federal Reserve Chairman Kevin Warsh said in a press conference earlier this month that employment data, business investment and private sector earnings indicate the economy is doing well.
“It’s hard to say that broader financial conditions are restrictive,” Warsh said. Monetary conditions are important information about how the Fed adjusts interest rate policy.
Other officials also weigh in
Similarly, Fed Chairman Michael Barr said Tuesday that the combination of tariffs and the prolonged war with Iran has “kept progress towards the 2% goal off track.”
“There is still no clear trend towards returning to 2% in a timely manner,” he said.
As a result, Barr reiterated his belief that the Fed will likely need to continue raising rates, but did not say by what level. The September decision brings the central bank’s borrowing standards to a range of 3.75% to 4%.
“In my base case, further policy adjustments are likely to be needed to ensure that inflation falls to target in a timely manner,” he said. “We want to support sustained and sustainable growth that supports maximum employment, and price stability is critical to that.”
New York Fed President John Williams cited increased artificial intelligence and the resulting demand for related products as a third driver of sustained inflation.
“Fortunately, other indicators are brighter on the inflation outlook,” he said. “Prices for housing services are slowing, but there is no evidence that the labor market is increasing inflationary pressures.”
Williams added that the pressure on commodity prices from tariffs has been significantly reduced.
From a policy perspective, he was more dovish than Barr, saying, “There’s no need to rush. We have time to gather more information.” However, he said there may be a need for “further upward adjustments” to interest rates this year.
continue to spend despite inflation
Wednesday’s announcement adds another wrinkle to the inflation permutation, with the previous month’s reading lower due to a revision applied retroactively by the Bureau of Economic Analysis.
Specifically, BEA is adjusting its methodology retroactively to 2021 for how it measures prices for legal services, software and computer accessories, and portfolio management services. As a result, the PCE annual inflation rate in July is likely to be revised downward by two to three tenths of a percentage point, possibly reducing 12-month inflation to 3%, according to various Wall Street estimates.
That way, you might be able to improve the appearance in your rearview mirror without necessarily changing the road ahead, since visibility remains cloudy.
Goldman Sachs, for example, expects inflation data in the coming months to be “modestly less favorable until more favorable trends resume.”

Any withdrawal would come as a relief to consumers who continue to spend despite sentiment being shaken as prices continue to rise.
The consensus is that consumer spending rose 0.8% in August, at least in part due to further increases in gasoline prices. In July, the rise was only 0.2%.
Despite rising energy costs, Bank of America reported strong spending.
Debt and credit card spending rose 6.9% year-on-year for the week ending September 19. Much of that increase was due to a 26.5% jump in gasoline prices. However, even excluding gasoline, spending increased by 5.7%.
For the Fed, the combination of persistent inflation and the fact that consumers are still willing and able to spend gives it little clear reason to conclude that a rate hike in September will be enough. Markets are pricing in a rate hike in October and a likely rate hike in either December or January.
