
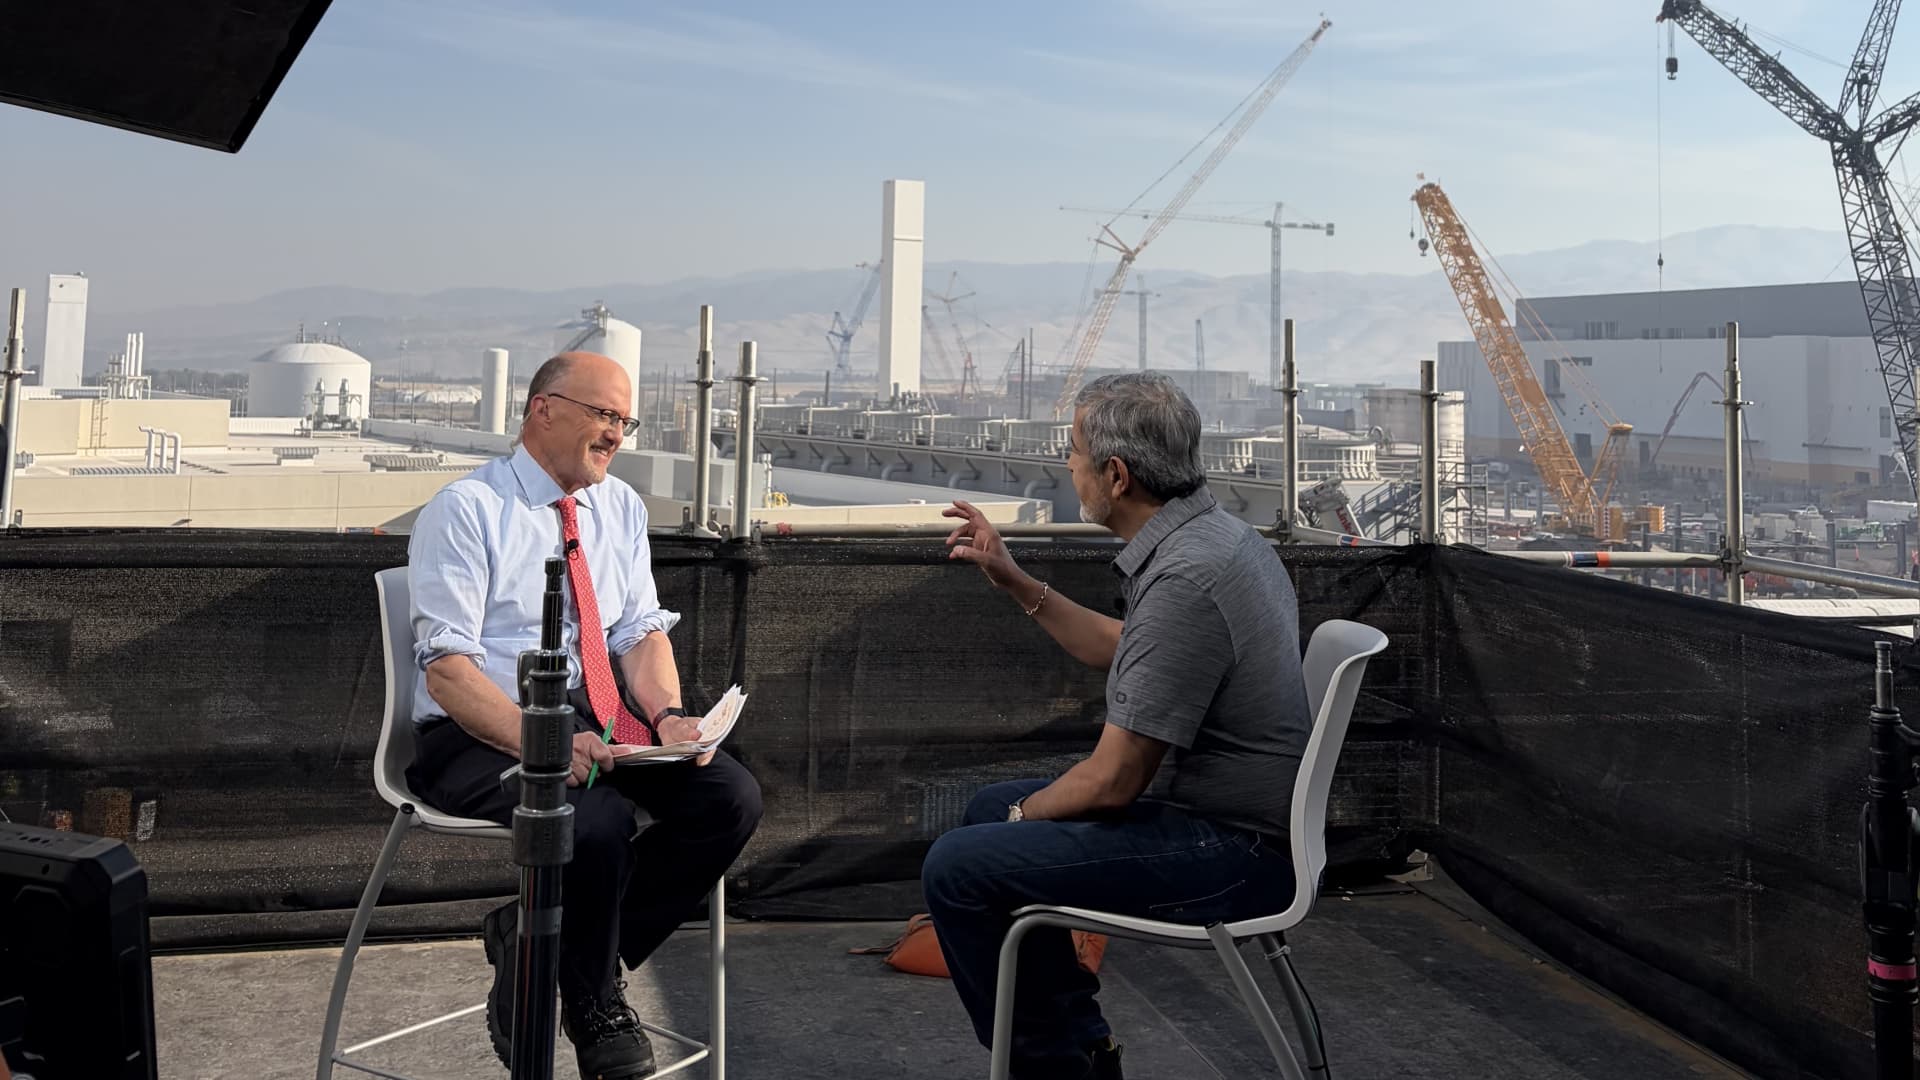
Micron on Wednesday night reported better-than-expected quarterly results and signaled another strong quarter in fiscal 2027 as demand for memory products continues to outstrip supply. Revenue for the fourth quarter of fiscal 2026, which ended Sept. 3, rose 379% from a year earlier to $54.23 billion, beating the consensus estimate of $51.07 billion, according to estimates compiled by LSEG. Adjusted earnings per share (EPS) rose 1,002% to $33.42, beating estimates of $31.61, according to LSEG data. MU YTD Mountain Micron YTD stock traded in a narrow range in after-hours trading, but settled near a flat line after management concluded its post-earnings conference call. The stock had a strong month in September, rising about 11%. For the year, Micron rose about 275%. However, it is down 12% from its record closing price of $1,213 on June 25th. Conclusion This year has been a record year for Micron. As supply conditions tightened and memory demand for AI applications skyrocketed, average selling prices rose healthily and revenue, gross margin, and EPS soared. Recall that there are two major products in the memory market. There is NAND, which is a storage memory like a flash drive. There is also Dynamic Random Access Memory (DRAM for short). This is considered working memory, similar to your computer’s RAM. There is also a special form of DRAM called HBM (High Bandwidth Memory). This is a key technology enabling modern AI workloads. AI accelerators perform the computations that power AI computing, but rely on HBM to store and serve data. To deploy AI efficiently and at scale, systems need higher memory bandwidth and larger memory capacity. Due to the increasing memory demands of AI systems, demand in the DRAM and NAND industries far exceeds supply, and no one knows when the two will strike a balance. Memory and storage supply and demand conditions remained tight in 2026, and Micron expects the situation to become even tighter in 2027 and 2028 as supply cannot keep up with demand. About 75% of Micron’s expected 2027 production has already been determined, and customers are already discussing 2028 allocations with the company. “The structural gap between DRAM supply and demand growth rates has resulted in continued supply tightness, and additional cleanroom capacity is needed to accelerate node migration supply growth and narrow the gap,” Sanjay Mehrotra, CEO of the company, said in prepared remarks. Adding a clean room refers to physically expanding manufacturing capacity by building and installing more equipment. Jim Cramer recently visited one of the company’s large semiconductor manufacturing sites (called fabs in the industry) under construction near the company’s headquarters in Boise, Idaho. “Even with the addition of the industry’s DRAM cleanroom space plans, strong demand trends, including new upside demands from customers, make it unclear when supply and demand will rebalance,” Mehrotra added. In this era of superintelligence, memory demands are fundamentally changing, and the products of three major companies – US-based Micron, South Korean companies Samsung and SK Hynix – are becoming increasingly differentiated. Memory still has to be considered a cyclical industry, with prices peaking and falling as demand is overestimated and supply catches up, but peak price concerns are why Micron trades at an incredibly low price-to-earnings ratio of about 6 times forward EPS estimates. This continued imbalance drives up prices every quarter, creating competition for customers to secure access to memory chips. Micron is increasingly signing strategic customer agreements (SCAs) to change its business model and give it better visibility into future revenues and prices. The goal of these SCAs is to move away from the boom-and-bust characterization of memory and create longer high-price cycles with more defined price ranges. Micron has signed 26 SCAs to date, up from 16 in the previous quarter. Typically, these contracts were to run from calendar year 2026 to the end of calendar year 2030. However, Micron said more customers want to secure supply beyond that date, and the company is responding to those requests by signing a one-year extension through 2031. To meet these customer commitments, Micron is committed to increasing capital expenditures to build new fabs and expand production. When companies plan large-scale capacity expansion programs, there are always risks due to shortages and price increases. In any cycle, the industry reaches a point where the addition of new capacity fuels fears of overconstruction and causes prices to plummet. However, Micron believes that the revenue visibility that SCA provides and the cash deposits required for these transactions gives it the confidence to continue investing to meet the surge in demand. There wasn’t anything new in terms of share buyback programs, but we think something big could be announced later this year. Under the CHIPS Act funding agreement, Micron is prohibited from repurchasing more than its stock-based compensation. These restrictions are scheduled to be eased in December. With $33 billion in free cash flow this quarter alone and expected to generate another $128 billion in the new fiscal year, according to FactSet, Micron could announce a stock repurchase program matching Nvidia’s recently-record-setting $150 billion increase to its previously authorized $85 billion program. The market is currently treating Micron’s beat and upside guidance as a good enough outcome to support the stock’s recent rally. Micron could see a lot of price movement after earnings, so we’ll see where the chips fall on Thursday morning. However, industry conditions in 2027 and 2028 are expected to be even more challenging than in 2026, Micron’s earnings should continue to grow, and a large share buyback program could further support the stock price. Increase price target from $1,100 to $1,200. Additionally, we reiterate our rating of 1, which is equivalent to Buy, which is consistent with the most recent rating we added to the position on September 3rd. Reasons to Own Micron should continue to benefit from increased demand for memory from AI, which is causing supply shortages and higher average selling prices. We believe the newly signed Strategic Customer Agreement (SCA) will provide more sustainable earnings than past memory cycles, while increased free cash flow will provide significant headroom for future share buybacks. Competitors: Samsung, SK Hynix Last Purchase Date: September 3, 2026 Start Date: August 11, 2026 Outlook Turning to the guide, Micron expects first quarter 2027 revenue to be $61.5 billion ± $1.5 billion. This is stronger than the consensus estimate of $57.02 billion, according to LSEG. For the full year, the company expects sequential quarterly revenue growth. Gross margin for the current quarter is expected to be approximately 86.25%, down slightly from the fourth-quarter performance of 87% and slightly below expectations of 86.31%, according to FactSet. While this may be a little disappointing, this drop is largely related to the company’s decision to increase employee compensation. This is an important distinction because we are more concerned about declines due to softening average selling prices. Allaying concerns over declining gross margins, management said it believes the first quarter will be the lower bound for gross margins this year. Finally, LSEG says the strong earnings outlook now calls for adjusted EPS of $38.15, plus or minus $1, beating the consensus estimate of $35.40. (Jim Cramer’s Charitable Trust is a long MU. See here for a complete list of stocks.) As a subscriber to Jim Cramer’s CNBC Investment Club, you will receive trade alerts before Jim makes a trade. After Jim sends a trade alert, he waits 45 minutes before buying or selling stocks in his charitable trust’s portfolio. If Jim talks about a stock on CNBC TV, he will issue a trade alert and then wait 72 hours before executing the trade. The above investment club information is subject to our Terms of Use and Privacy Policy, along with our disclaimer. No fiduciary duties or obligations exist or arise from your receipt of information provided in connection with the Investment Club. No specific results or benefits are guaranteed.
