
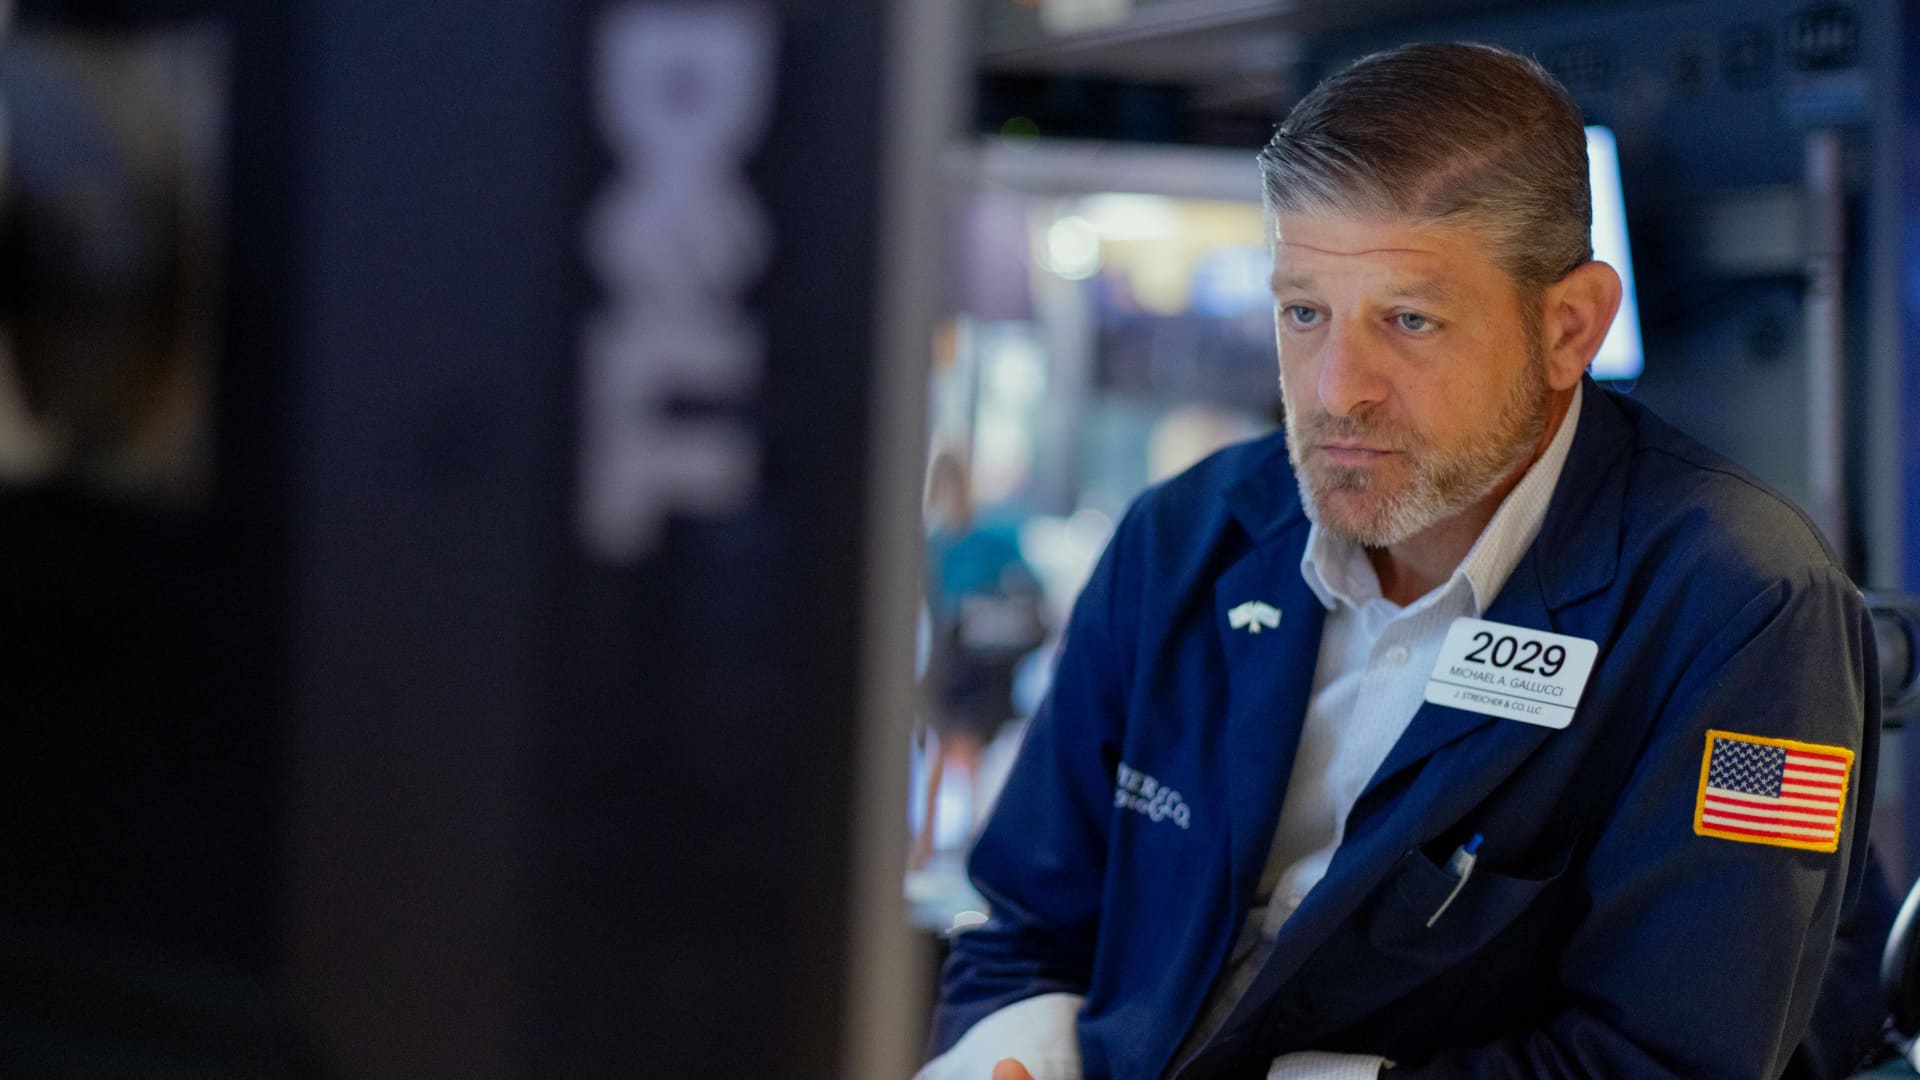
September 2, 2026 Trader at the New York Stock Exchange.
new york stock exchange
Borrowing costs for the U.S. government have risen to their highest levels in decades, raising concerns that the country’s growing debt burden could eventually trigger a fiscal crisis. Will it happen?
The benchmark 10-year Treasury yield is now firmly above 5%, and the government’s net interest cost is estimated at about $1.05 trillion in the first 11 months of fiscal 2026.
Experts have expressed concern about the vicious cycle of rising debt and rising yields. Maya McGuineas, chair of the Committee for a Responsible Federal Budget, a U.S. policy think tank, warned that higher borrowing costs risk becoming self-reinforcing as higher interest spending forces governments to borrow more.
“The real threat is a debt spiral. As interest begets debt and debt begets interest, eventually debt will spiral out of control. Fiscal crisis, once unthinkable, is now a distinct possibility,” McGuinius said in a statement last month after the 10-year Treasury yield rose above 5%.
The nightmare scenario is relatively simple. Investors demand higher yields to finance heavily indebted governments. These rate increases drive up Washington’s interest bill. Governments have to borrow more to pay off their debts. And investors demand even higher yields in response.
But some bond market experts say the U.S. is far from fiscal breaking point and say the recent rise in yields may have as much to do with the surprisingly resilient economy as concerns about government debt.
“The financial apocalypse has not yet arrived,” TD Securities strategists Gennady Goldberg and Molly Brooks said in a recent note.
The bank expects U.S. interest expenses to be about $1.1 trillion in fiscal year 2026 and continue to rise if interest rates remain high. If yields remain near current levels, financing costs will reach $1.4 trillion in 2027, $1.5 trillion in 2028 and $1.6 trillion in 2029, according to its projections.
A key cushion, analysts at the investment bank said, is that the U.S. government doesn’t have to immediately refinance its entire debt pile at today’s high interest rates.
The weighted average maturity of U.S. Treasuries is approximately 5.9 years, meaning higher borrowing costs are gradually reflected as existing debt matures and new debt is issued. According to TD Securities, the average coupon rate for Treasury securities excluding bills remains at 3.1%.
Perhaps more importantly, the average interest rate on U.S. Treasuries is about 3.4%, which remains below the economy’s nominal growth rate. U.S. nominal GDP grew at an annualized rate of 8.5% in the second quarter, according to the latest estimates from the U.S. Bureau of Economic Analysis. This will help keep the debt burden manageable even though the deficit remains high, TD said.
Matthew Rees, head of global fixed income strategy at L&G Asset Management, also said concerns about an impending U.S. financial crisis were “overblown.”
“There are legitimate concerns that the U.S., like many other advanced economies, will suffer from a negative feedback loop caused by increased fiscal burdens caused by higher yield costs as it refinances debt to finance deficits,” he told CNBC in an email.
“However, the United States still retains many of the US dollar’s ‘extraordinary privileges’ and much of its role as the most liquid and still highly rated economy. We are therefore far from a fiscal crisis.”
Not a crisis, but still
Rees said negative feedback loops become even more dangerous when nominal economic growth declines to low levels, causing debt to continue to rise relative to the size of the economy.
Still, high debt alone does not necessarily cause a crisis.
“It’s important to note that countries like Japan have been able to cope with significantly higher debt levels than the United States with very low nominal growth rates without falling into fiscal crisis,” Reese said.
According to the Congressional Budget Office, federal debt held by the public is expected to reach approximately 101% of GDP in fiscal 2026.
While this trajectory is enough to cause investors concern, TD Securities doesn’t see a financial crisis as imminent.
And government finances may not be the main reason why bond yields have skyrocketed so much.
TD cited strong economic growth, expectations for Fed rate hikes, rising oil prices, corporate bond issuance, fiscal concerns, and repositioning by fast money investors as factors contributing to the rise in yields.
Ian Lingen, head of U.S. rates strategy at BMO Capital Markets, also cited the resilience of the U.S. economy as a key factor in the rise in U.S. Treasury yields.
“All else being equal, investors are satisfied with the underlying performance of the real economy and share the Fed’s concerns about inflation,” Lingen wrote. He said the latest jobs data was “likely to provide further confirmation of the resilience of labor market conditions in the face of persistently high inflation and rising borrowing costs.”
Lingen added that the rise in long-term yields is “primarily a real interest rate story,” with investors pointing to the strength of actual and expected economic growth, among other factors, to explain the move.
Just 1% of respondents in the BMO survey said the labor market is where the first signs of obvious stress from rising real interest rates appear. Housing topped the list at 42%, followed by stocks at 26% and corporate credit at 21%.
But that could change if rising interest rates eventually start to cause significant damage to the economy and financial markets. “The only permanent constraint to further rises in bond yields will be incontrovertible evidence that the economy or risk assets are exhausted under pressure from rising borrowing costs,” Lingen said.
