
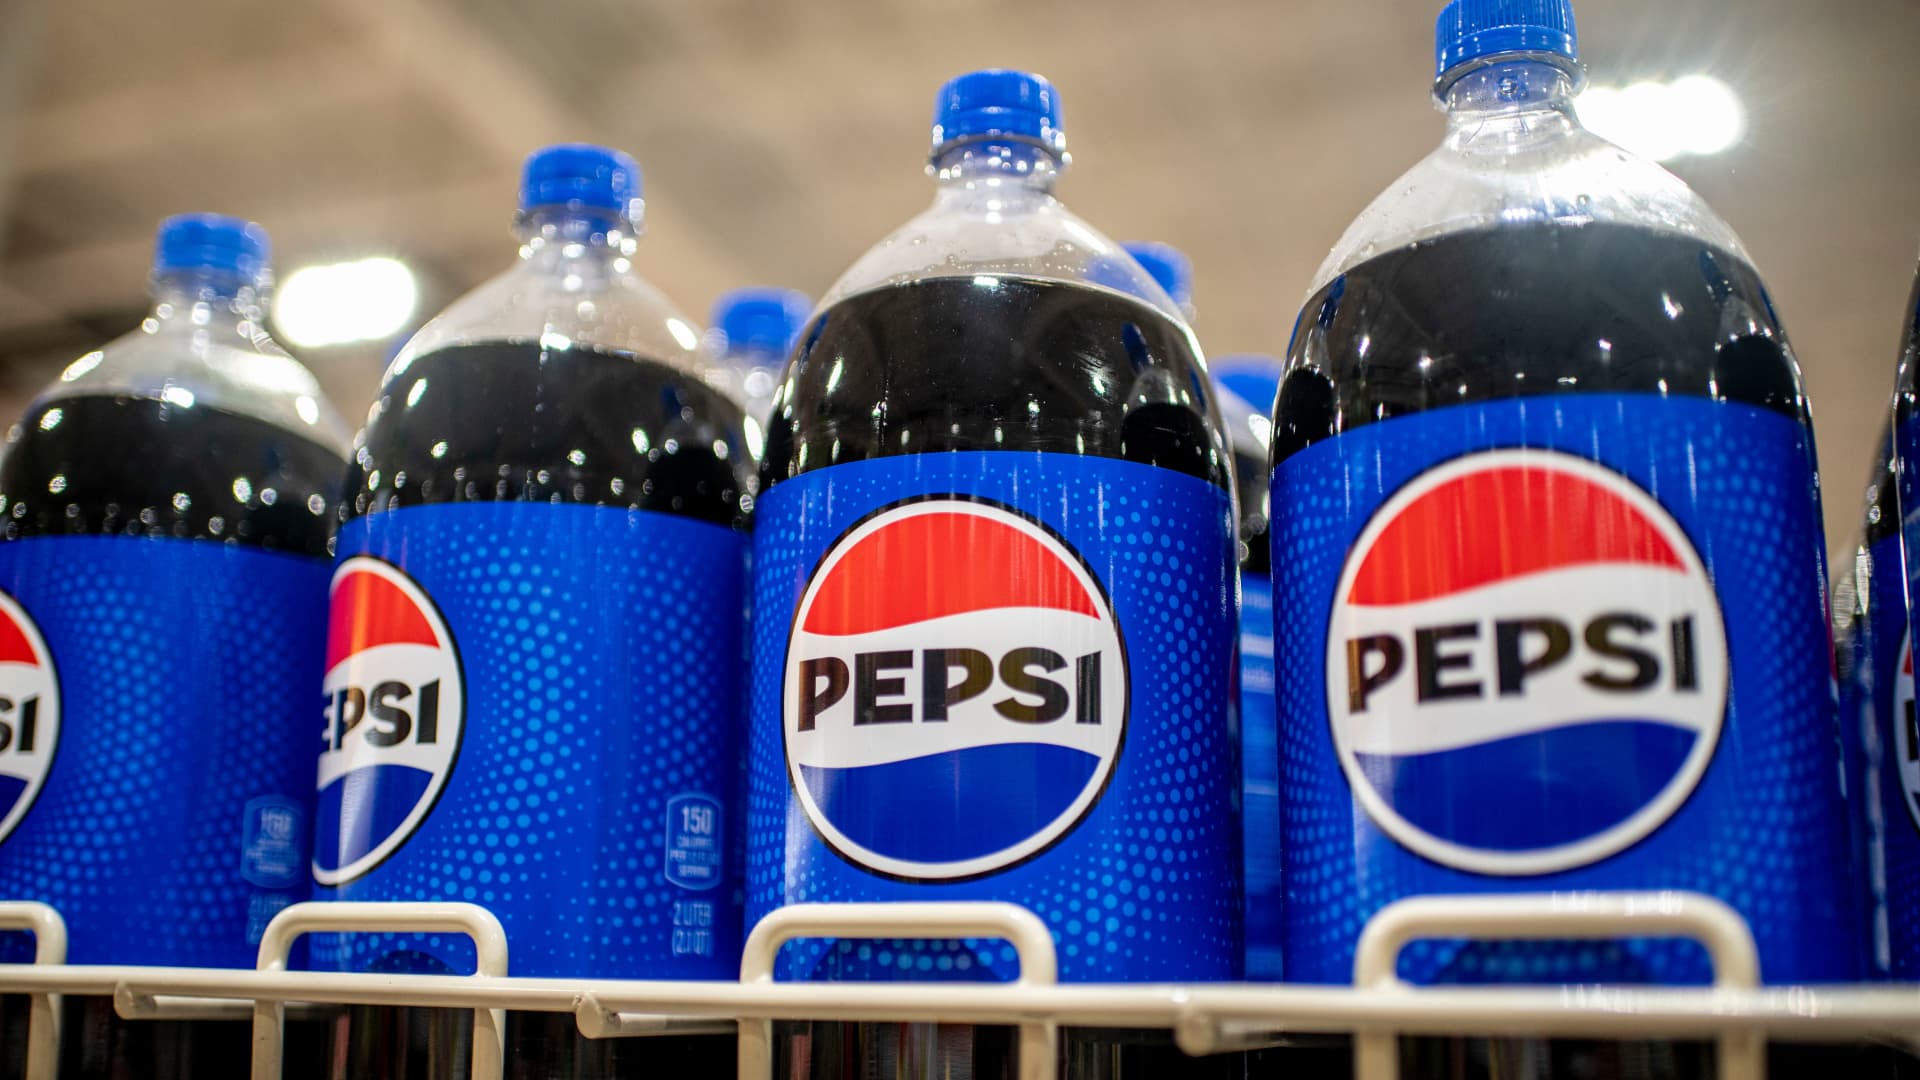
pepsico cut its profit outlook on Thursday, but CNBC’s Jim Cramer thinks there’s reason to be more optimistic about the beleaguered beverage and snack giant.
The company reported better-than-expected third-quarter profits and sales, but cut its full-year profit forecast as increased costs and investments to recover demand weighed on profit margins. The stock rose 3% following the report as investors focused on improving sales trends and a widely expected reduction in guidance.
“Despite facing so many worldly challenges, it’s too big of a leap to say PepsiCo is completely out of the woods here,” the “Mad Money” host said. But given the reason for the estimate cut and the stock’s relatively low valuation, he said, “I feel pretty good about this story. You could do a lot worse than buying PepsiCo here.”
PepsiCo stock has struggled since hitting an all-time high in May 2023, before concerns about the impact of GLP-1 weight loss drugs on snack consumption began to spread on Wall Street. PepsiCo shares have fallen nearly 10% in September alone as inflation, oil prices and rising interest rates have added pressure recently. Stocks closed Wednesday at their lowest since April 2020.
Mr. Kramer said the positive stock market reaction was due to two factors: improved sales momentum and a lower earnings outlook, which was already largely priced into the stock price.
“Wall Street didn’t care about the downward revisions to earnings estimates because everyone knew this was inevitable,” he said.
PepsiCo’s new earnings forecast calls for growth to range from 5% to 7% to 2.5% to 3.5%.
“Look, the new guidance could have been much worse,” Kramer said. “Many expected to hear that the company was being eaten alive by high costs. Instead, we heard great stories about how PEP is investing to maintain revenue growth.”
For Kramer, the distinction is important. PepsiCo is investing more in advertising, product innovation, and lower prices to attract consumers. These efforts, along with rising costs for fuel and packaging materials, are putting pressure on profit margins, but they appear to be contributing to a recovery in sales.
Organic revenue increased 3.1%, beating the FactSet consensus of 2.75%. It also marked the company’s strongest performance since Q4 2023. Importantly, the company maintained its organic revenue growth outlook at 3% and raised its reported revenue growth forecast to 6% versus previous guidance of 4% to 6%.
CEO Ramon Laguarta said the company is “acting with urgency to sustainably improve our performance in North America,” while also considering additional cost reductions to fund growth initiatives.
Cramer warned that PepsiCo still faces challenges from changing consumer habits, including the impact of weight loss drugs. But that’s nothing, he said, as the stock trades at about 15 times the median estimate for lower earnings and supports a dividend yield of about 4.61%.
