

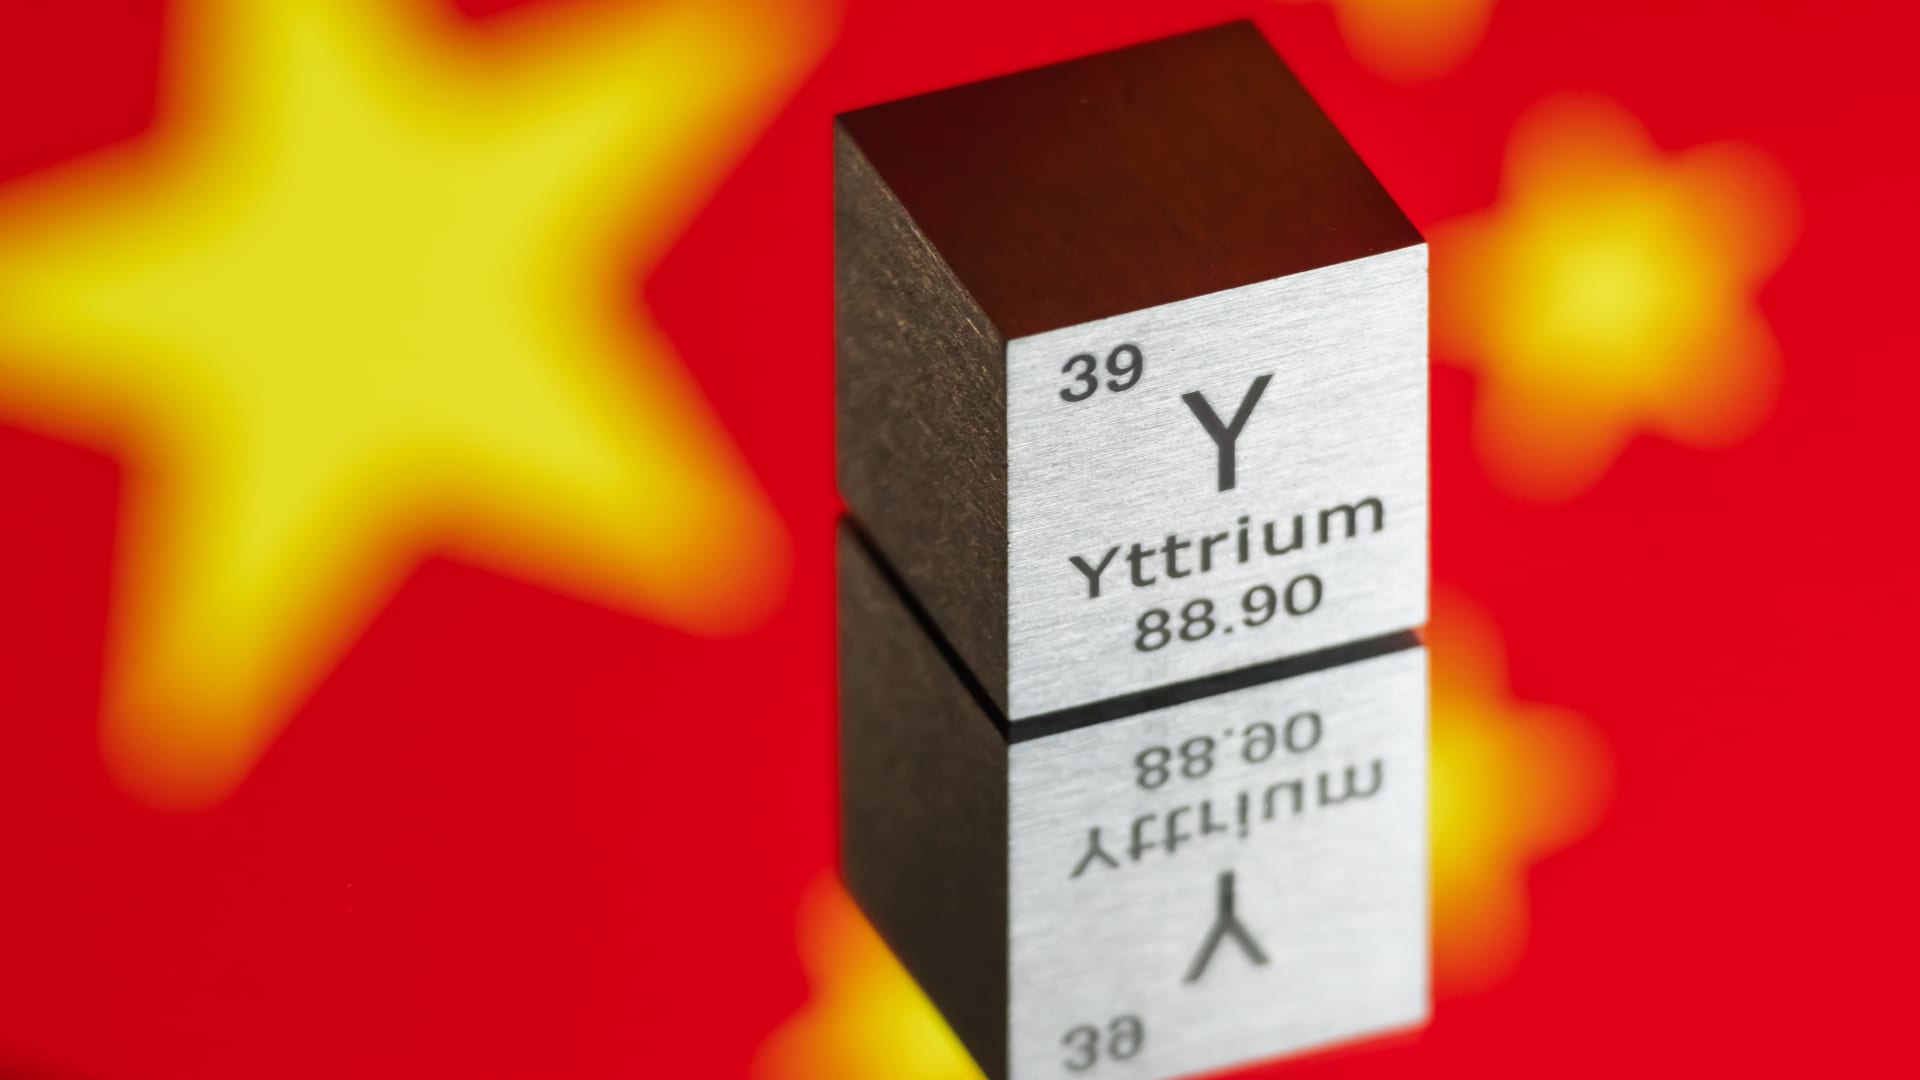
SHENZHEN, CHINA – SEPTEMBER 25: In this photo illustration, a metal cube model labeled with the chemical symbol, atomic number and atomic weight of yttrium is placed on a mirror surface with the model’s reflection and the Chinese flag visible on the mirror, on September 25, 2026 in Shenzhen city, Guangdong province, China.
Chen Xin | Getty Images News | Getty Images
China is mobilizing state-owned companies to expand ownership of overseas mines and tighten its grip on metals vital to electric cars, semiconductors and jet engines.
Analysts say the state-led push could give Beijing more influence over global supplies of critical minerals and who has access to them.
In place of corporate-level decision-making, “China is developing a nationally coordinated global mining strategy,” said Dan Wang, Eurasia’s China director, adding that this model would enable larger and more coordinated global mining investments.
In April, a specialized overseas bureau was established to oversee overseas investments by central state-owned enterprises. Several government agencies, ministries, and policy banks have been mobilized to lead overseas mining deals.
In late July, a mining investment vehicle was created to coordinate overseas deals and advise Chinese companies on compliance, risk management and market conditions amid rising geopolitical tensions and regulatory hurdles overseas.
Wang said increased centralization could curb unregulated competition among Chinese companies and strengthen their leverage over Western rivals and new entrants from countries such as Saudi Arabia and India, but lengthy vetting and approval processes could increase corruption risks and weigh on investment returns.
Chinese companies have been investing heavily in overseas mines for two decades, making big bets in places that Western miners have shunned, from Tajikistan to the Democratic Republic of Congo. This effort is gaining urgency as governments increasingly view critical minerals as sources of geopolitical influence.
China’s mineral acquisitions abroad reached $8.8 billion in the first three quarters of this year, already the highest annual total since at least 2018, according to a Rhodium Group report released Wednesday.
“Most of the acquisitions are focused on minerals that China lacks domestically,” said Armand Meyer, senior research analyst at Rhodium, pointing to lithium, nickel and cobalt during the mid-2010s electric vehicle boom and, in recent years, gold.
safety range
Eurasia said foreign investment in upstream critical minerals is likely to roughly double compared to the 2021-2025 period, as China doubles down on its overseas efforts to secure access and reserves it lacks at home.
The Chinese government treats 70% import dependence as an implicit red line, which puts copper, lithium, cobalt, nickel, bauxite and iron ore under severe national security constraints to expand supplies overseas, Wang said.
Even in places where dependence is low, the Chinese government wants more dependence. For gold, 50% is within the “safe” range, Wang said, but the government is still seeking additional access to high-grade resources. The pursuit of scale and “ultimately geopolitical strength” could override decisions around investment risk and profitability, he added.
Processing “exclusive”
However, this push is facing increasing resistance as host governments demand increased local processing. This stage is dominated by China and is an important checkpoint in the supply chain. More resource-rich countries are restricting exports of unprocessed minerals and requiring foreign partners to refine them locally.
Because of the high environmental costs of refining, countries have long shipped rare earths to China for processing, which would allow large-scale processing capacity to be built across China. The United States has abundant supplies of rare earths, but relies on China to refine them.
According to the International Energy Agency, China currently produces about 92% of the world’s refined rare earths.
If rivals build new (mineral) refineries, China could increase production, oversupplying the market and pushing prices below economic levels.
brad handler
Director, Payne Institute Energy Finance Research Institute
This allows the Chinese government to withhold supplies, flood the market to affect prices, and inject power, said Brad Handler, director of the Payne Institute’s Energy Finance Institute. “If rivals build new refineries, China could increase production, oversupplying the market and pushing prices below economic levels,” he said.
Since last year, China has restricted the export of seven types of medium and heavy rare earths, and requires exporters to obtain permits.
Japan has been the hardest hit and will reportedly feel the effects within months of yttrium being depleted. This element is used in screen displays and semiconductors, and is produced as a byproduct during the extraction of other rare earth metals.
China’s exports of yttrium oxide to Japan fell to 4,000 kilograms in September from 51,000 kilograms a year earlier, according to Chinese customs data. The price of oxide reportedly soared from about $9 per kilogram in China to about $1,150 per kilogram outside China (about 179 times the level two years ago).
Bedford said Japan spent 16 years building up its stockpile after China’s restrictions in 2010, but “the ability to separate yttrium and lutetium is virtually non-existent outside of China.”

But Rhodium says Chinese companies have adapted in recent years, increasing their investments in greenfields and locating processing capacity near mines rather than outright acquisitions.
Meyer noted that Indonesia’s ban on nickel ore exports has led Chinese companies to build smelting and refining capacity in the Southeast Asian country rather than shipping the ore back to China. “This is most evident when the host government requires local processing,” Meyer said.
