

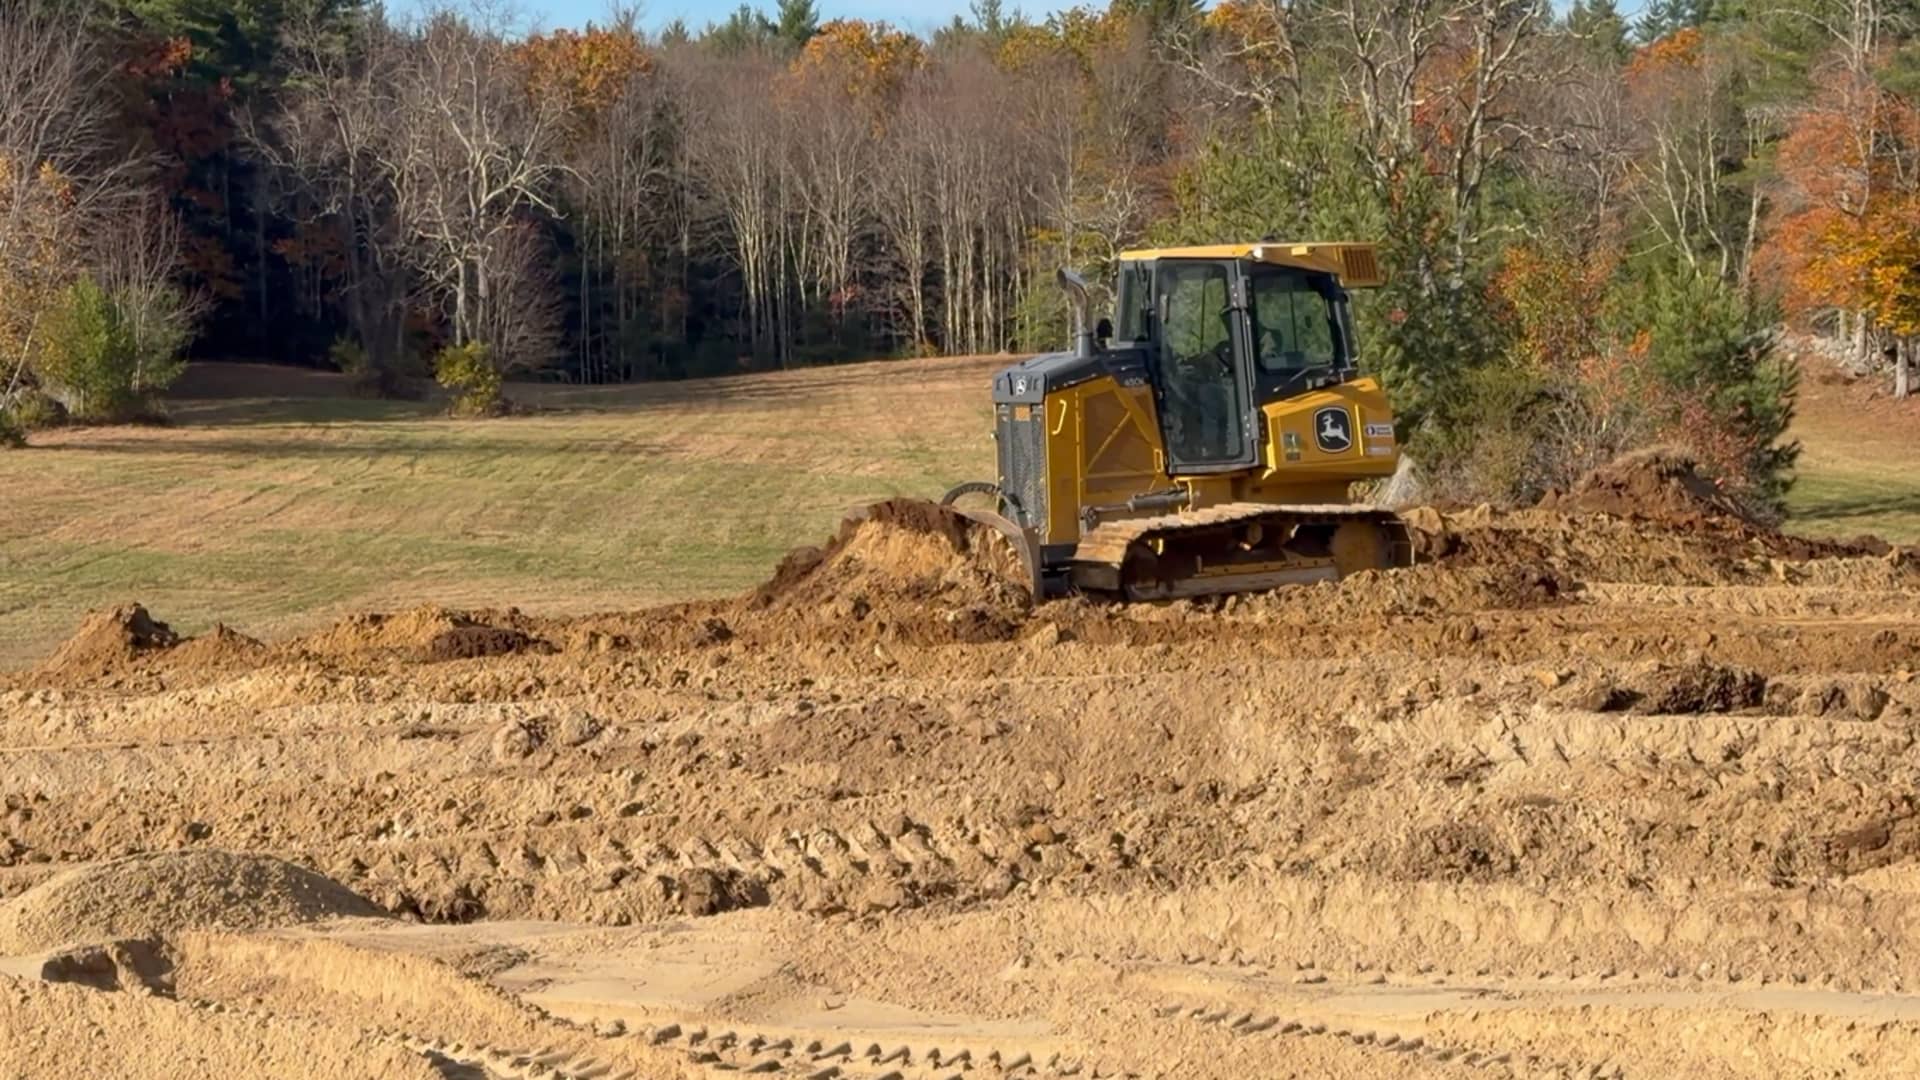

I’m a strong believer in investing in what you know and what you use. During a recent visit to my parents’ property in New Hampshire, my brother and I tackled some overdue maintenance. Having the right equipment on hand was critical to completing the work within the limited time available.
Michael Koo’s younger brother is operating a bulldozer rented from United Rentals in late October 2026.
Credit: Michael Khouw
He and I rented both a compact track loader (CTL, not pictured) and a bulldozer (pictured above). United Rentals (NYSE: URI) To accomplish heavier tasks.
For those who aren’t familiar with United Rentals, they can rapidly deploy heavy equipment to remote locations. This is why I believe it is suitable for options trading where the risks are clear and moderately bullish.
The good news is that United Rentals is currently trading below the market’s expected multiple. On a price-to-earnings ratio (PER) basis, it is approximately 17.3 times the current forecast, or approximately $61.10 per share, and on an enterprise value to EBITDA (EV/EBITDA) basis, the FY2027 EBITDA is approximately 8.8 times, or $9.25 billion. This is despite the fact that the company is compounding revenue, earnings, and EBITDA at a noticeably faster pace than the market-cap-weighted S&P 500. In effect, you can buy superior market-beating growth at a discounted market multiple.
Recent third-quarter results confirmed this trajectory. URI has revised its forecast upwards, showing solid underlying demand across its end markets, and is racing to catch up. Improving revenue forecasting is one of the most reliable and proven short-term investment factors. Stocks with positive forecast revisions tend to significantly outperform stocks with declining forecasts in the short term.
The macro context provides a solid foundation for this growth. We are currently in the midst of a broad-based nonresidential construction recovery, which is driving an environment of improving rental rates and resilience. While a potential slowdown in data center construction could certainly be a future headwind, broader infrastructure demand remains strong.
To have a balanced view, you need to be aware of the risks. While URI looks cheap compared to the broader market, it’s not necessarily cheap compared to its history. The company’s stock is currently trading at about 20% to 25% above its average multiple over the past five years. One could easily argue that historical multiples are simply too cheap for a business of this quality, scale, and capital efficiency. Still, the downside risk remains that the average reverts to historic “undervalued” levels.
This is where the options market comes into play. If you own a stock with solid momentum, fundamentals, and positive estimate revisions, but are hesitant to put too much weight into its historical valuation, adding to the stock completely unhedged may not always be the best move. Instead, selling a cash-covered put provides a highly strategic entry mechanism.
trade
URI’s implied volatility currently hovers in the 42% to 45% range, so the options market has priced in enough volatility to offer a reasonable premium. By selling a cash-covered put, we recognize the good and the bad. Appropriately hedges the risk from historical multiple increases while honoring aggressive growth, market share gains, and recent beat-and-raise quarters.

United Rentals (YTD)
If the stock price continues to rise, the put will expire worthless, giving you a high probability yield that easily exceeds that of a bond. If the stock price declines, perhaps toward its five-year average multiple, we will be allocated the stock at a lower effective cost basis, but if that happens, we may be able to write an upside covered call against it, further lowering the stock price. (This approach of entering a stock and writing a covered call once assigned is sometimes called the “wheel strategy”).
Therefore, we either acquire an attractive stock at the price we specify (short sale minus the premium collected on sale), or we simply collect a premium to take on that risk if the stock does not fall. For companies that provide the literal heavy lifting for infrastructure growth, this is a structural advantage worth trading.
Disclosure: Tidal owns/holds all securities mentioned in the article.
All opinions expressed by CNBC Pro contributors are solely their own and do not reflect the opinions of CNBC, its parent or affiliate companies, and may have been previously disseminated on television, radio, the Internet, or another medium. This content is provided as part of editorial output for informational purposes only and does not constitute financial, investment, tax, or legal advice or a recommendation to purchase any security or other financial asset. The content is general in nature and does not reflect any individual’s unique personal circumstances. The above may not be appropriate for your particular situation. Before making any financial decisions, you should strongly consider seeking the advice of a financial or investment advisor.
This content is provided for informational purposes only and does not constitute financial, investment, tax, or legal advice or a recommendation to purchase any security or other financial asset. The content is general in nature and does not reflect your unique personal circumstances. The above may not be appropriate for your particular situation. Before making any financial decisions, you should strongly consider seeking the advice of your own financial or investment advisor.
Click here for full disclaimer.
