

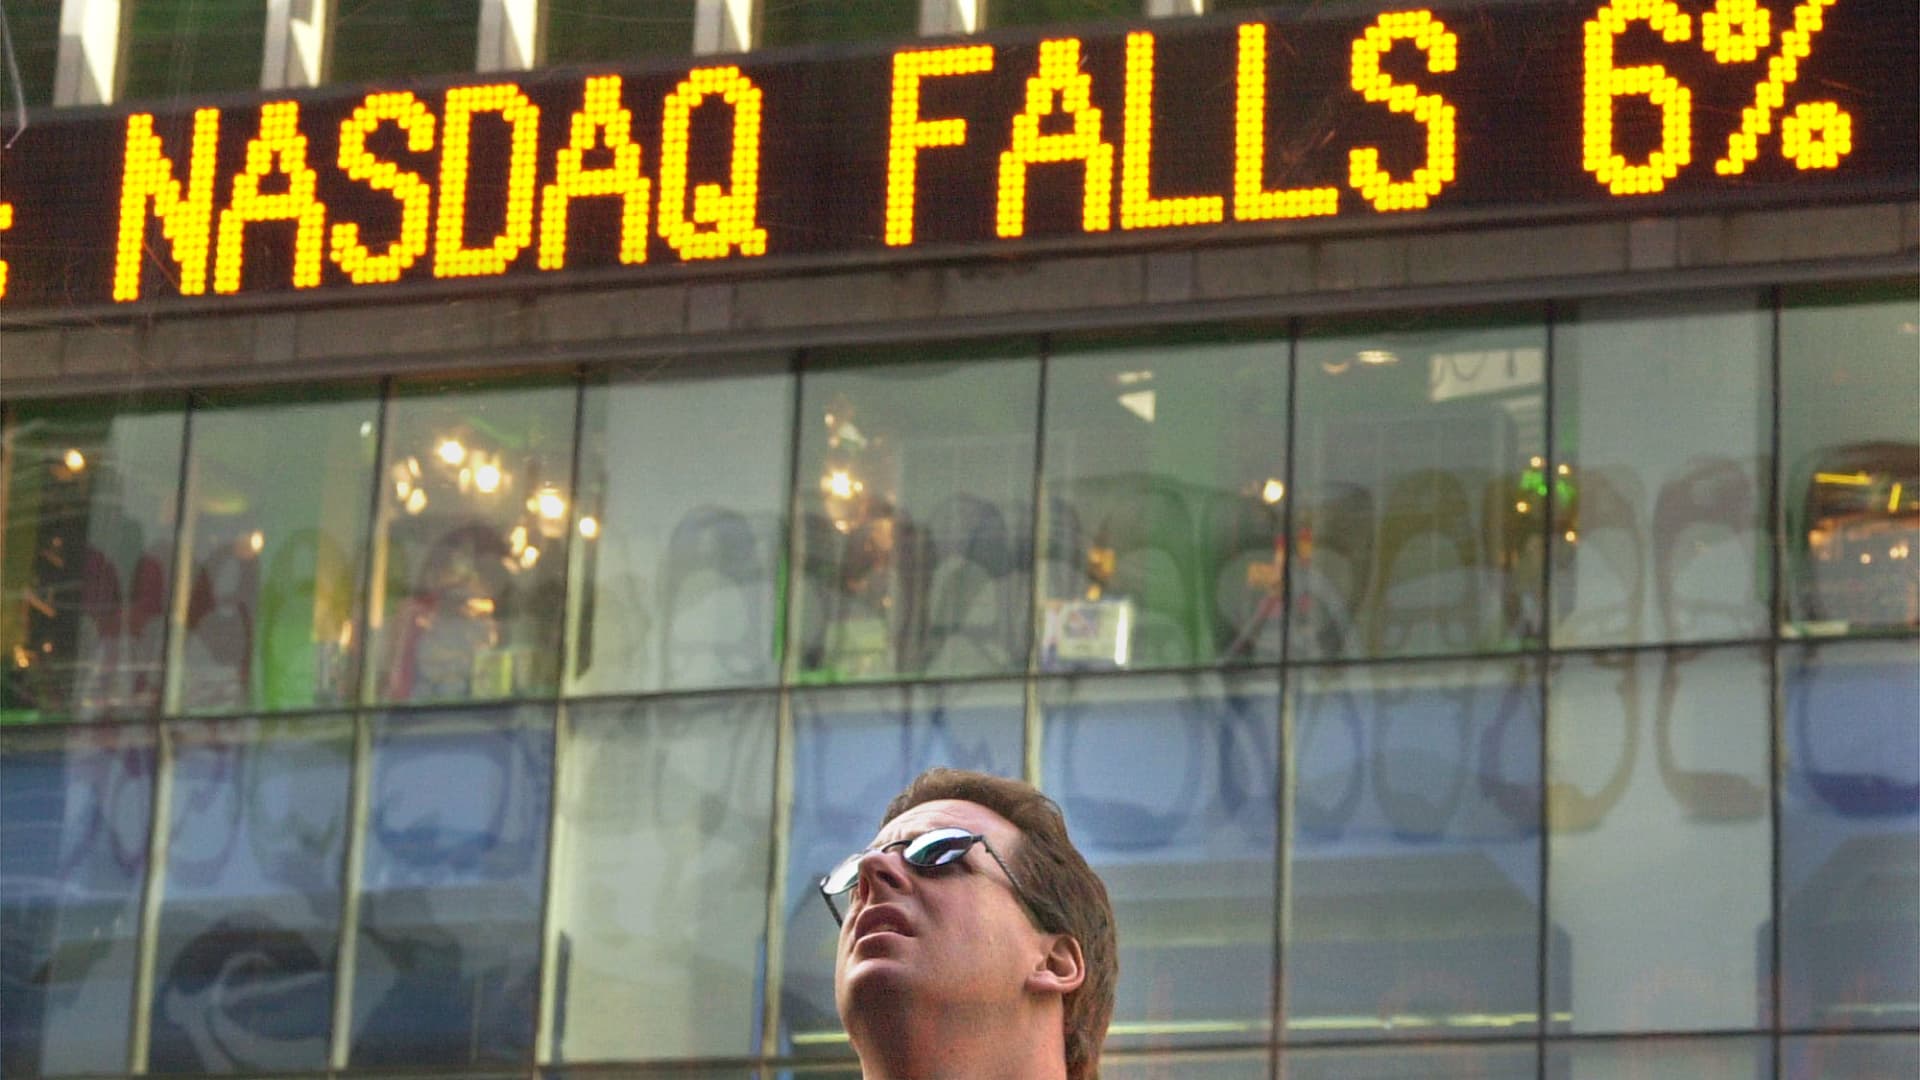
A man watches the stock index plummet at the Nasdaq Market site in Times Square, New York City, on December 20, 2000.
Chris Hondros | Hulton Archive | Getty Images
While baby boomers get all the attention when it comes to retirement, Gen Retirement by age 55 in the United States is mostly a vestige of the past, when defined benefit pension plans were funded. Currently, most people in the 50-55 age group are still thinking about 10-15 working years ahead. This extends the amount of time investors can continue to contribute to 401(k) plans and IRAs to grow their assets, making time on the market the biggest long-term benefit for investors. However, the closer an individual is to retirement, the more an ill-timed market crash can cause a serious setback.
Gen According to a study by the Alliance’s Retirement Income Research Institute, only 14% of Gen By generation, Gen Xers are the least financially prepared for retirement in almost every way. “While baby boomers dominate the headlines, Gen Xers face an even deeper retirement crisis,” the authors write.
This situation may make Gen Xers cautious about their retirement savings. High returns over a 10-year period have led many investors, especially those years from retirement, to S&P500 Using investment trusts and ETFs, I rode the record rise in the stock market until just before I retired. However, history is replete with examples of crashes that unfortunately occur at the worst possible time.
Amazon.com’s bubble stock chart is a good example. Investors who bought at the peak of the dot-com market in 1999 had to wait a full decade for the stock to regain its previous high and finally break a new record in late 2009. The broader S&P 500 index similarly tells the story of a slow road to recovery. After the index bottomed in October 2002 after the dot-com bust, it took nearly five years to return to new highs in 2007. That high couldn’t even hold as the Great Recession wiped it out almost immediately. Calculating from the bottom of the second crash in March 2009, it took another four years for the S&P 500 to finally permanently surpass its old 2007 peak in March 2013.

Depending on how you count, that’s anywhere from 4 to 13 years in the water. It all depends on which crash point and from which valley the measurements were taken. And for someone who is three to five years into retirement, that’s not an academic timeline.
Ernie Cave, a certified financial planner and founder of Cave Wealth Management, says what goes down will eventually come up, but when is important for retirees. “History shows that markets will recover, but retirees don’t have a choice whether that recovery takes a year or several years. If they are forced to sell their investments during a downturn to generate income, those stocks are lost forever and they cannot participate in the recovery,” Cave said. This is why what financial advisors call “chain of return” risk is so dangerous.
How to gradually move away from the S&P 500
Investors who are already thinking about retirement should avoid being surprised by the rise in the S&P 500 index and how well it performed for them.
“One of the biggest mistakes I see is investors going into retirement with almost all their money in an S&P 500 fund just because it has performed well over the past 10 years,” Cave said. He added that while the S&P 500 is a good long-term investment, it may not be a good place to store the money you’ll need during the first few years of retirement.
“The problem is not owning an S&P 500 fund. The problem is asking that same fund to pay next year’s bills and pay for retirement 25 years from now,” Cave said.
He advocates directing retirees to a variety of “war funds.”
“Typically, you want to protect about two years of expected portfolio distributions with cash or very short-term investments, and about five years of expected withdrawals with cash, Treasuries, CDs, and high-grade bonds. The remaining long-term assets can remain invested for growth,” Cave said.
Cave said the purpose of retirement funds is not to sell stocks or eliminate market declines. “This is to reduce the likelihood that retirees will be forced to sell long-term investments during their retirement,” he said.
Investors nearing retirement don’t necessarily need to significantly reduce their exposure to stocks, but they do need to more clearly differentiate between funds they can use immediately and funds that can remain invested until the next market cycle. “Retirement doesn’t eliminate the need for growth; it changes how much money you can afford to grow,” Cave said.
Some Gen Xers are literally on track for retirement, which they hope will limit their exposure to market volatility. A glide path is when investors gradually move their portfolio from stocks to bonds toward retirement, reducing exposure to market declines during the most damaging periods.
“The glide path gradually changes the portfolio as clients approach retirement,” said Elias Friedman, CFP and founder of Kadima Wealth.
erect a temporary tent
Another shield against market crashes is the bond tent. This is a strategy that temporarily increases bond holdings just before and in the years following retirement, when the risk of market declines is most high.
“Both options can reduce the likelihood of having to sell stocks after a significant stock market decline. In my experience, clients are accustomed to a glide path approach to investing,” Friedman said.
Friedman said rolling back the bond tent is not about waiting for some signal that the danger has passed. No one can judge that moment with certainty, and attempting to do so is market timing otherwise known as market timing.
“Clients have many options for how to address this risk, for example, consider a ladder of bonds or CDs, or short- to intermediate-term securities. They don’t have to put all their money back into the market at once,” Friedman said. “Smart customers will do this tactically, as well as rebalancing their portfolios from time to time. This can help reduce some of the risk.”
Regardless of the path, Friedman says the transition should be gradual, rather than a major relocation at the time of retirement. “Think of it like driving cross-country on the highway and then hitting the brakes. We find that gradually slowing down makes the drive less stressful and more comfortable,” he said.
But this market is different from past markets in at least one important way, said Asher Rogovi, chief investment officer at Magnifina, a registered investment adviser. It’s AI and the growing prominence of a small number of tech stocks in the S&P 500.
“Traditionally, 20 to 30 individual stocks provided sufficient protection against company-specific risks. Today, an estimated 40 to 50 percent of the market value of the S&P 500 is accounted for by companies related to a single theme: AI,” Rogovi said.
If the past is prologue, Rogovi said, this may mean it doesn’t end well. “We’ve seen this story before. We saw similar levels of index concentration in the dot-com bubble, and the aftermath should give us pause,” he said. “Capitalization-weighted indexes come with concentration risk, especially if they had invested the same amount in each company in the S&P 500. They could have avoided much of the decline and reached new highs years earlier,” Rogovi said. S&P created an equal-weighted version of the index in 2003, and many funds and ETFs now offer the option of equal-weighting their core S&P 500 exposure.
But Rogovi believes there is no pure stock strategy that can completely avoid market crashes, so the most important decision for people nearing retirement is whether to split between stocks and bonds. “Most people know more about stocks than bonds, and that’s where investment advisors can prove invaluable. By combining fixed income allocation with disciplined rebalancing and value investing, advisors can build portfolios that can withstand volatility and protect their clients’ retirement,” he said.
Mike Dunlop, CFP and co-founder of Ignite Planning in Cedar Falls, Iowa, says the biggest danger for Gen Xers right now is the concentration of companies in S&P 500 funds. “Right now, seven of those cases account for more than 30% of the total. For people aged 50 to 55, the real risk is not the crash, but the risk of a mistimed crash or back-to-back returns,” Dunlop said.
“If the market drops 30% the year you retire and you take out money to live on that year, you’ll be selling at rock bottom to buy groceries and gas, and you’ll never get a chance to get that part back,” he said. “There is no need for those nearing retirement to give up on the lost decade,” he added.
His fee-only financial planning firm is moving some of its clients’ assets away from their core S&P 500 and stock market index funds and reallocating them into large-cap value stocks — “You’re just not betting your entire retirement savings on the top seven stocks in the same stock market,” Dunlop said.
