

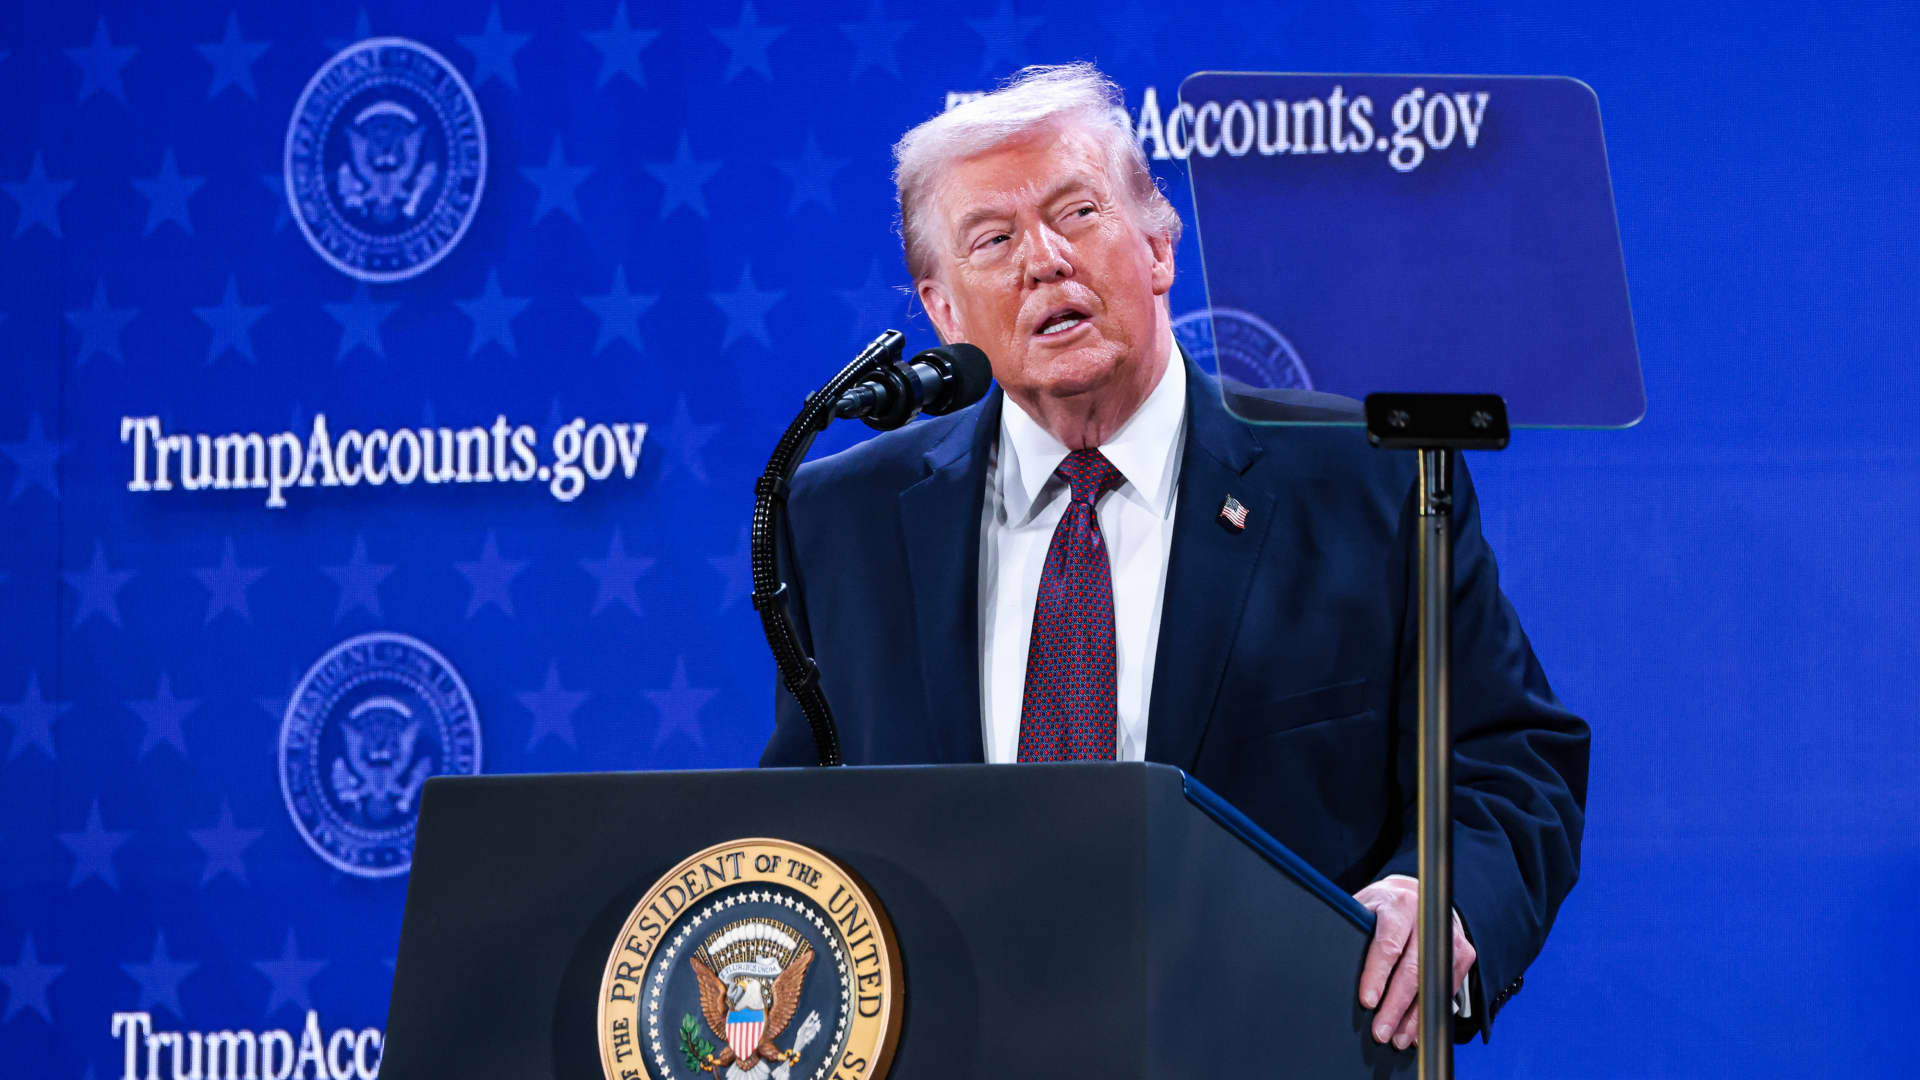
U.S. President Donald Trump speaks at the Trump Account Launch Summit on Wednesday, January 28, 2026 in Washington, DC.
Valerie Preche | Bloomberg | Getty Images
The U.S. Treasury and IRS this week proposed regulations for how employers and employees can fund Trump Accounts, a new tax-deferred investment option for children.
The proposed regulations outline how certain employer contributions to Trump accounts can be excluded from an employee’s gross income. Employers can also allow employees to fund dependent children’s accounts with pre-tax dollars directly from their paychecks.
Treasury Secretary Scott Bessent said in a statement Tuesday that the Trump account, also known as a 530A account, “offers American families a new way to build wealth from day one.”
“The Treasury Department today announced guidance to help families grow their Trump Accounts by allowing employers to contribute up to $2,500 per year tax-free for employee dependents and giving employees the option to contribute pre-tax dollars directly to those accounts,” Bessent said.
The announcement follows notices of proposed rulemaking from the Treasury Department and IRS on Monday detailing how employers can open Trump accounts. The proposal will be subject to public comment and a public hearing scheduled for October before the agency finalizes the rules.
Who can contribute to a Trump account
Trump accounts are available to any U.S. child under 18 with a Social Security number.
Children born between 2025 and 2028 can receive a one-time $1,000 deposit from the Treasury as part of a pilot program designed to jump-start long-term savings.
Approximately 7 million children have enrolled so far, Bessent said in remarks at the Financial Literacy and Education Committee meeting on July 27.
Once the account is opened, a parent, guardian, grandparent, etc. can contribute up to $5,000 per year up to the year before the beneficiary turns 18. As part of the $5,000 limit, employers can contribute up to $2,500 per worker per year.
As of Tuesday, more than 50 companies had pledged to donate to the Trump account on behalf of their employees, with some offering to match the government’s $1,000 in seed money, according to the Treasury Department.
While there are still some unanswered questions, employers now have a much better understanding of the governance and compliance framework, said Melissa Elbert, a wealth solutions partner at Aon, a retirement consultant for employers.
A Mercer poll of about 350 U.S. employers conducted in April found that only about 4% of companies expect to implement Trump account contribution programs in 2026 or 2027, and two-thirds have decided not to make contributions to these accounts. Others were undecided.
Employer interest is likely to increase following Treasury Department guidance, Elbert said. “We’ve seen early adoption, but I think more companies are looking to adopt and this guidance will help,” she said.
