
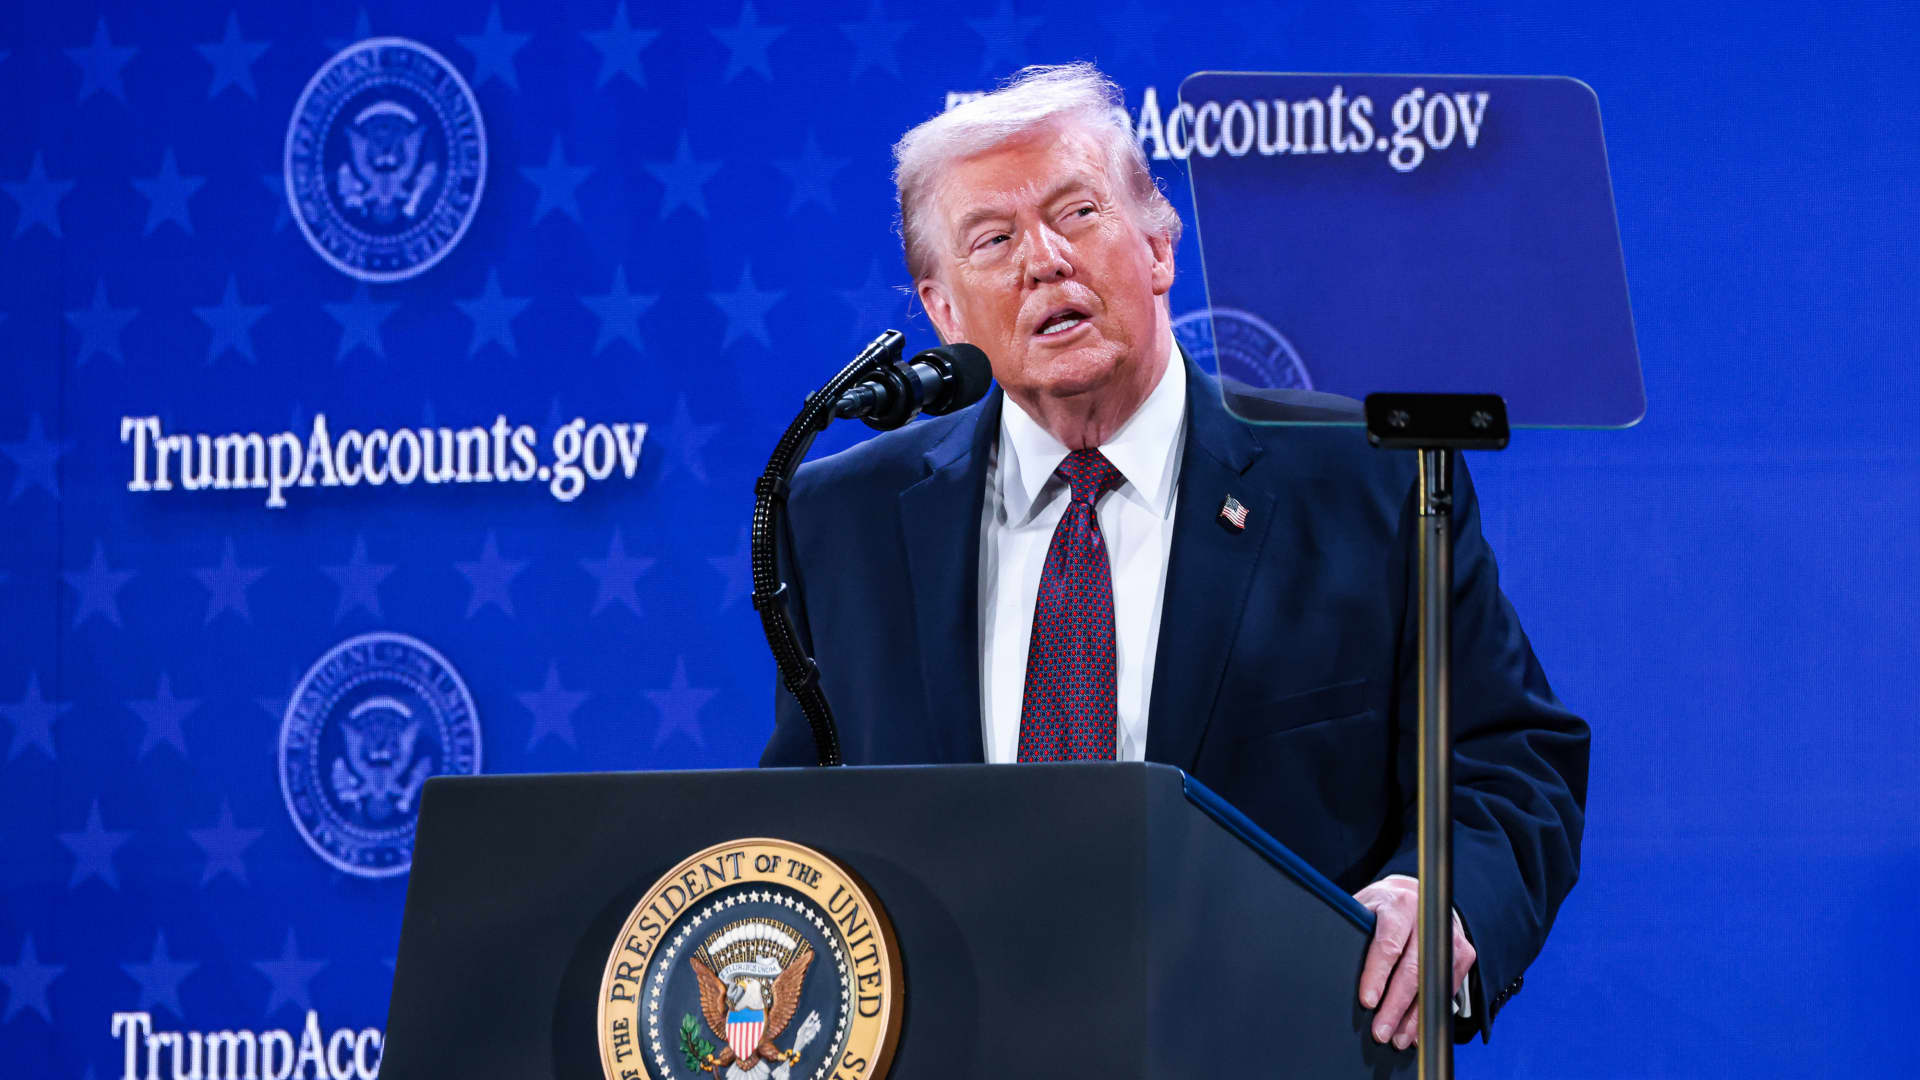
U.S. President Donald Trump speaks at the Trump Account Launch Summit on Wednesday, January 28, 2026 in Washington, DC.
Valerie Preche | Bloomberg | Getty Images
As the end of the year approaches, millions of families face new deadlines. December 31st will be the last chance to donate to the Trump account in 2026.
The deadline also applies to employers that provide benefits to employees in Trump accounts, such as through direct contributions or salary deferrals.
Tom Oseven, director of tax content and government relations at the National Association of Tax Professionals, said workers should check their benefits before their Trump account reaches the annual limit because company deposits and employee deferrals count toward the annual limit.
“We want to make sure we don’t spend too much money,” Oseven said. If you don’t, you could be hit with a hefty penalty of 6% per year on excess contributions until the funds are removed, plus 100% of the earnings from those funds upon withdrawal.
The Trump Account (also known as a 530A account), which opened on July 4, is a new tax-deferred investment option for children aimed at helping the next generation build wealth.
The Trump account contribution limit for 2026 is $5,000, which includes deposits from family members, businesses and others. This limit does not include philanthropic contributions such as $1,000 seed money from the Treasury Department or $250 grants from the Dell Foundation for children born between 2025 and 2028.
In August, the Treasury Department and IRS released proposed regulations that included early guidance for companies that offer Trump account benefits to their employees. Public comments are being accepted, and the agencies plan to hold public hearings in October before finalizing the rules.
April Walker, senior manager of tax and ethics at the American Institute of Certified Public Accountants, said the proposed regulations “clarified some things,” but other questions remain.
In the meantime, here’s what small businesses and employees need to know about Trump Account benefits in 2026.
How Trump Account Employer Contributions Work
There are two ways companies can participate in contributing to the Trump account.
In 2026, employers can contribute up to $2,500 per employee, which will not be counted as the worker’s income but will still be subject to payroll taxes. Alternatively, companies can set up a program to fund the account from employees’ pre-tax paychecks.
Employer contribution limits and other guidelines for Trump Accounts apply to both large and small businesses.
“The Trump Account provides small businesses with new, low-cost tax benefits they can use to attract and retain workers, invest in their employees’ families, help workers share in America’s growth, and strengthen Main Street over the long term,” a Treasury Department spokesperson told CNBC in an email.
“Every competitive advantage is important when it comes to attracting and retaining talent,” Kelly Loeffler of the Small Business Administration told CNBC.

But company participation may be limited in the first few years, according to a Mercer survey of about 350 U.S. employers conducted in April. The poll found that only 4% of those surveyed plan to implement a Trump Account donation program in 2026 or 2027.
Trump account rules for self-employed people
Ben Henry Moreland, a certified financial planner at advisor platform Kitces.com, says one of the most common questions is whether a self-employed person can open a Trump account on behalf of their child and make employer contributions to the account. The answer is no.
According to proposed regulations released by the Treasury Department in August, contributions to Trump accounts would not be excluded from “owner-employee” income if the owner is a sole proprietor, partner, or 2% or more shareholder in an S corporation.
“If you have an employee, you can set up a Trump Account donation program and donate to the employee or the employee’s children, but you cannot donate from there to your own children,” Henry Moreland said. “You have to follow some pretty strict rules.”
According to the Treasury Department, several steps are required for an employer to establish a Trump Account Contribution Program, including written plan documentation, certification steps, employee notification, and reporting.
“This is very similar to other types of employer plans,” said the AICPA’s Walker.
In addition, there are so-called “non-discrimination rules” that employers must follow, she said. Generally, these guidelines do not allow corporate tax reductions if benefits favor executives or high earners.
“Essentially, it says that contributions to these Trump accounts should not unduly favor highly compensated employees who are owners over everyone else in the company,” Henry Moreland said.
