

France’s parliament will begin deliberating its 2027 budget on Tuesday, as high budget deficits, rising debt and student protests increase the political cost of fiscal consolidation.
The eurozone’s second-largest economy is heading toward a debt crisis, and continental Europe risks being dragged into one unless it sustainably reduces its national deficits, many market observers say.
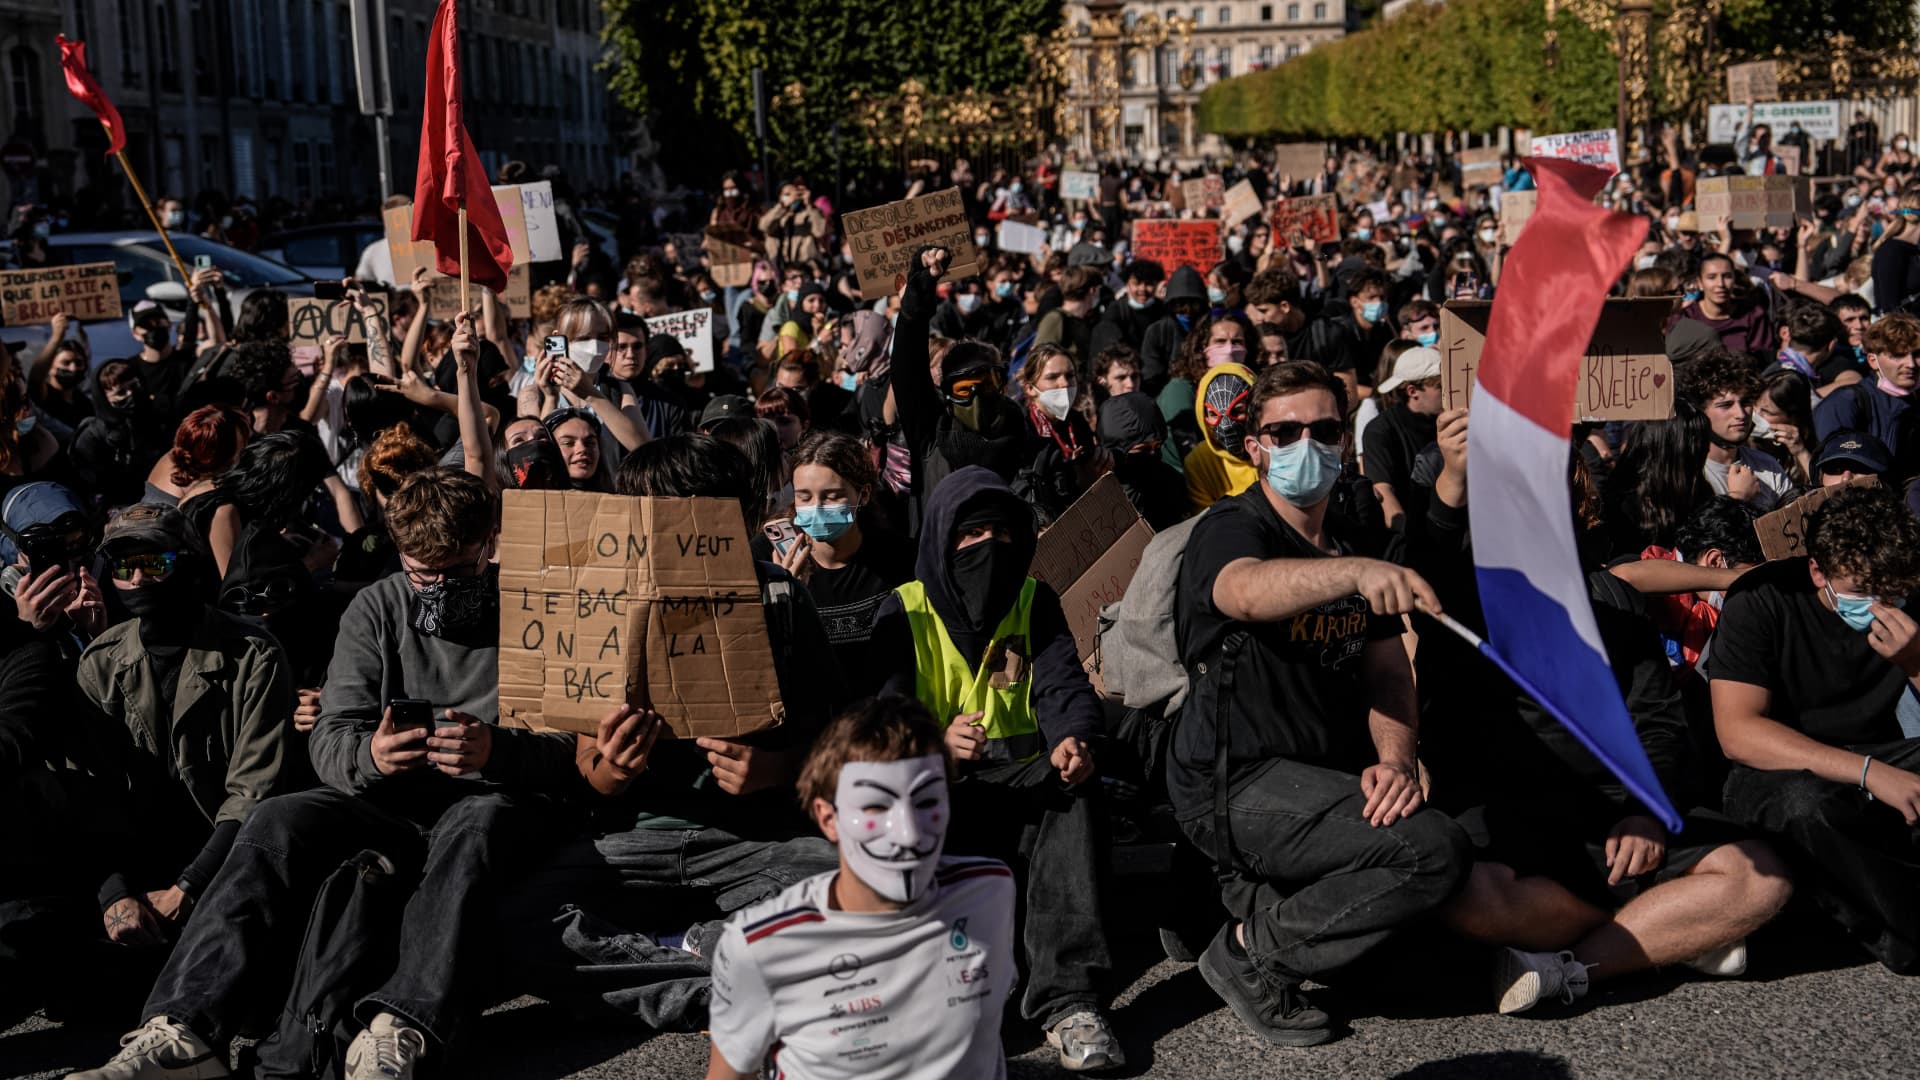
France has had one of Europe’s highest budget deficits as a percentage of GDP for nearly a decade under President Emmanuel Macron, even as thousands have taken to the streets to protest years of underfunding of public services, particularly education.
Government spending remains well above other countries on social protection, particularly in politically sensitive areas such as pensions and health care, but tepid economic growth has not been able to compensate.

Economic and political uncertainty in France is weighing on the euro as presidential elections loom next year and parliamentarians prove reluctant to compromise.
Borrowing costs for the French government have risen to the highest level in nearly a quarter of a century, as the French government’s failure to consolidate its fiscal health has led to instability in the bond market.
The widening gap between French and German bond yields has raised questions about whether the European Central Bank will have to take the expensive and politically controversial step of intervening to stabilize markets. This could stave off the panic that would tear apart the monetary union, but the legacy of the sovereign debt crisis that has hit countries such as Greece, Ireland, Portugal, Spain and Italy will require drastic action from France.
“The ECB will not intervene just to ‘bail out’ France. If there is a crisis in Europe, it will intervene in some way, but it will not save a country that cannot save itself,” Antonio Fatas, a professor of economics at INSEAD Business School, said in an email.
These graphs illustrate France’s challenge.
read more:

