
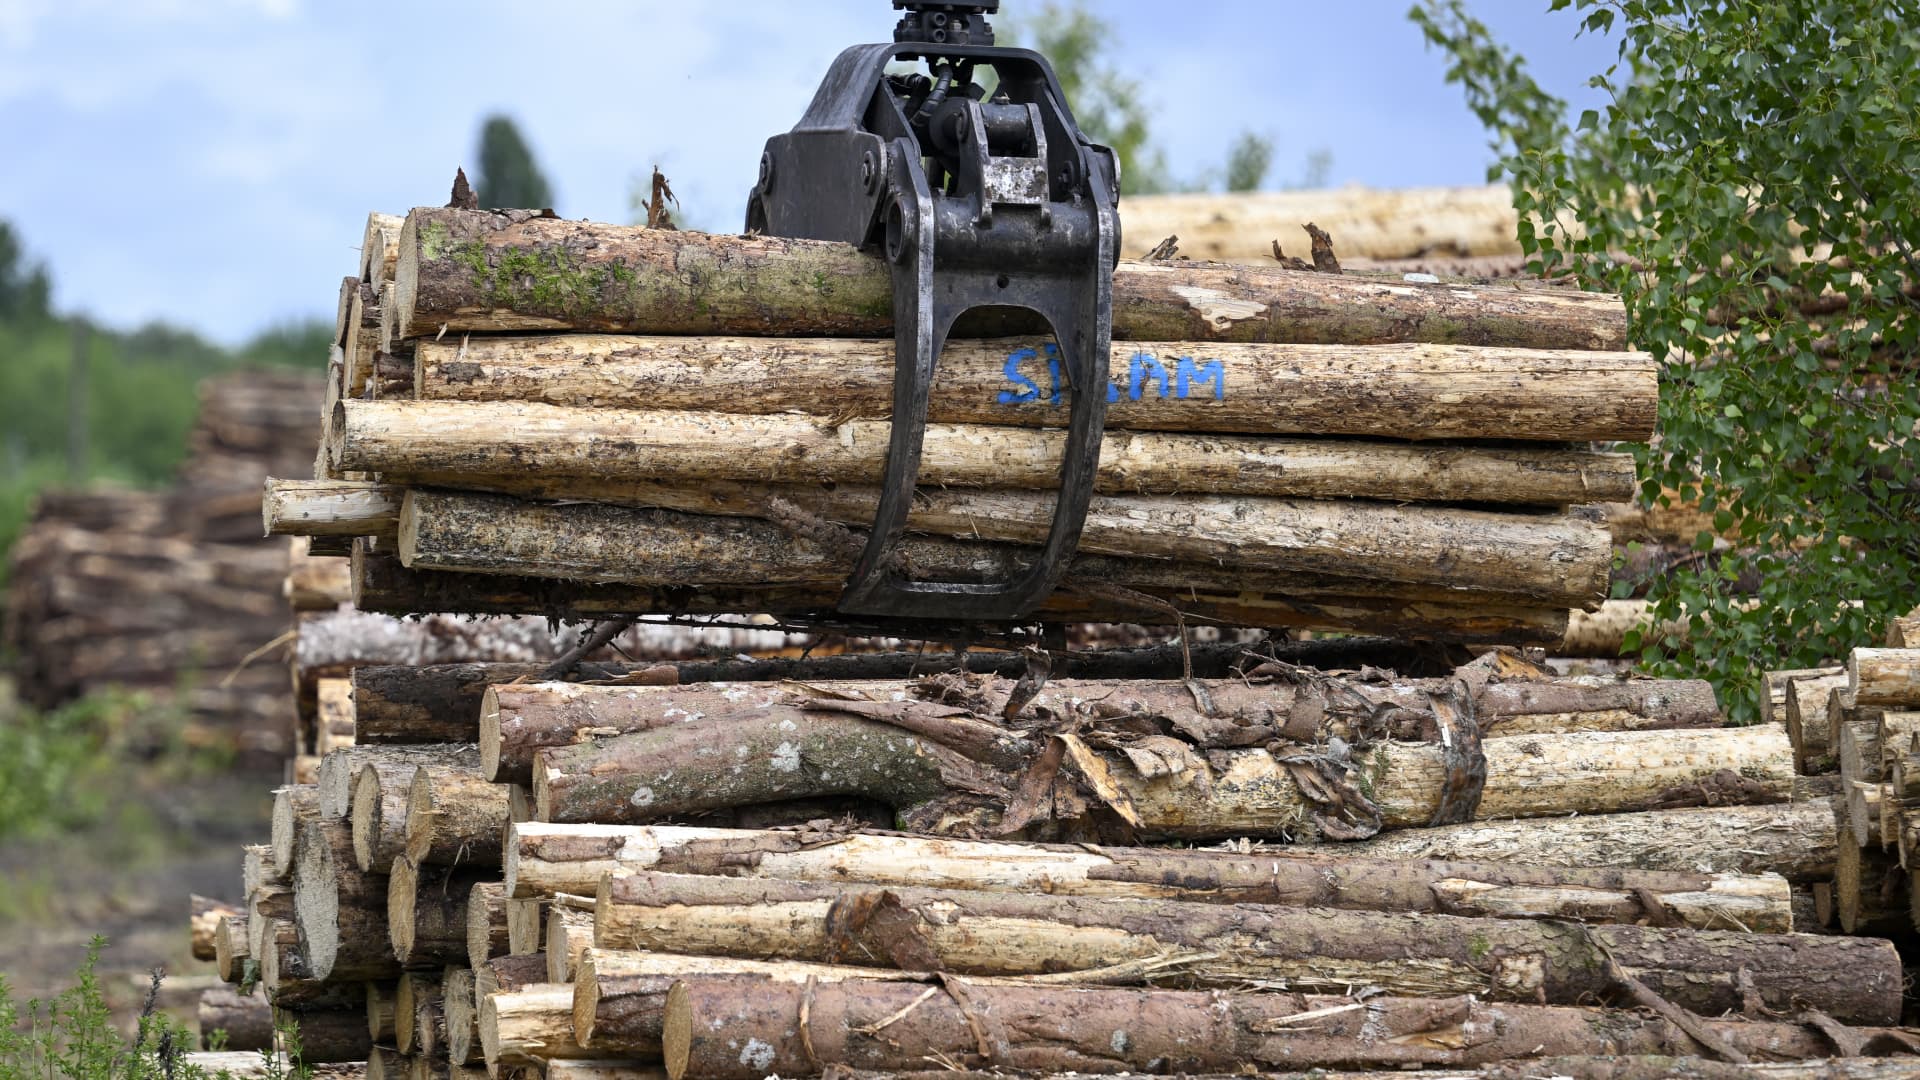
Jean-Christophe Verhagen | AFP | Getty Images
When the economy and market seem unstable, gold and national debt It is a traditional place to deposit money. These days, some investors are turning their attention to something more grounded: wood.
This pitch is easy to like. It’s a back-to-basics natural asset that grows naturally, matures into a harvest, and can all be turned into cash while being used to hunt, pitch tents, and forage.
Institutional investors are buying forest land at a rate of 1 million acres a year, according to Bank of America, and some financial advisers say retail investors, including young Americans who are seeing higher prices in the housing market, are also eyeing the asset class. But there is no rush to do so, and investors who already own forest land warn that it may not be very profitable in the short term.
“Timber is a very low-return investment. I cut back on it,” said Pat Dorn, founder of Anchor Investment Management, a fee-only advisory firm in Columbia, South Carolina, and former president of the South Carolina Forestry Association. Dorn owns 2,500 acres of woodland in South Carolina’s booming northern region. Dorn said the problem is that there is currently more timber being grown than is needed for a depressed housing economy.
“Supply exceeds demand and that causes prices to plateau. Timber is not an investment at this point,” Dorn said.
Nationally, the Bureau of Labor Statistics’ Producer Price Index for logs, bolts, lumber, pulpwood and wood chips rose in September, but prices have mostly been trending downward since summer 2022. It measures the price producers receive for their products, rather than the value of forest land or investment returns. In the very long term, prices have increased significantly.
Financial institutions note that it is one of the asset classes that is of particular interest to long-term investors.
Ken Shepherd, head of specialty asset management at Bank of America Private Bank, said timberlands are not a strategic asset class that can be easily entered or exited based on short-term market conditions. “We view this as a strategic, long-term investment supported by several favorable long-term trends, including the continued expansion of the wood industry in the southern United States and growing demand for wood products beyond traditional architectural uses,” said Shepherd.
For example, demand for wood pellets used in bioenergy is controversial but is increasing significantly, he said. In addition, forestland values are benefiting from strong demand from recreational and lifestyle buyers, supporting land prices beyond income derived from timber harvesting.
The National Council of Real Estate Investment Fiduciaries’ Timberland Real Estate Index, which tracks privately held timber properties in the United States that are owned at least in part on behalf of institutional investors, had a total return of 0.95% in the second quarter of 2026, consisting of 0.34% income and 0.61% appreciation.
Timberland management leads acquisition
Bank of America reported in its 2026 outlook that it expects the pace of purchases to continue at 1 million acres per year for the third consecutive year.
Timber managers acquired 55% of all acres transferred in 2025, but only 15% was sold, according to Bank of America. Educational institutions are playing the long game. Large forest managers are buying for pension funds and endowments that can wait decades, which could bet on a long-term recovery in the currently depressed U.S. housing market, which could favor timber pricing. However, individual business owners who survive in today’s market see things differently.
Dorn pointed out that lumber companies buy immature trees for pulpwood, which is used to make paper towels and notebook paper, and it can take 12 to 14 years for those trees to reach maturity. The different types of trees made with chip-and-saws take a little longer, but the big prize of wood cut for housing can take 25 years. “That’s the best value,” he said.
Dorn said the amount paid to landowners for standing trees varies depending on what the trees are used for. Pine pulp lumber is made up of wood that has been ground into paper or packaging, while pine lumber is made up of large trees that have been cut into lumber for home construction. Hardwood lumber, on the other hand, consists of oak and other large trees used for flooring, furniture, and pallets. Because each product serves a different set of buyers, some products may rise while others fall.

Performance of timber futures on CME.
Statewide average pine pulpwood stump prices (the amount buyers pay landowners for standing timber) fell about 33% from $5.67 per ton in the third quarter of 2025 to $3.79 per ton in the third quarter of 2026, according to data from the South Carolina Forestry Commission. During the same period, the price of pine lumber fell about 6%, from $22.78 to $21.47 per ton, while the price of hardwood lumber rose about 40%, from $16.04 to $22.52.
Historically, pulpwood prices have reached $12 to $18 per ton, Dorn said, while softwood was in the $35 to $40 range 20 years ago. He said since pine saw lumber is cut as lumber for new homes, prices tend to follow home construction, so those prices could recover once the housing market recovers.
Dorn says strategically placed timber may not be a bad investment, but it’s more about the land itself than the timber. “The reward is in the land, not the timber,” Dorn said.
He advises anyone looking to invest in woodland to look for prime land outside of growing metropolitan areas, where new areas may emerge as local populations continue to expand. “If you buy land near a growing metropolitan area and want to hold on to it, continuing to generate income through timber while you hold the land is a reasonable way to generate very low returns,” he said.
Ownership risks are extensive.
Michael Martin, a Western New York timber owner and vice president of market strategy at brokerage trading block Trading Block, says timberlands may be a good long-term investment, but the reality of ownership belies the romantic image of acres of untouched woodland. It’s not as passive an investment class as it seems.
Direct ownership is highly illiquid and involves management costs, property taxes, logging costs, exposure to local timber markets, and risks such as wildfire, pests, disease, and trespass hunting and logging.
And when it comes time to harvest the wood, you need to make sure you get the best deal. “If you don’t get competitive bids and just choose a small local business, you don’t necessarily know if you’re going to get the best price,” Martin says.
He also said lumber prices are very regional and can affect whether it’s a solid investment.
“I always check stump reports because lumber prices are very localized. An oak tree in Western New York may have a completely different value than an oak tree in the Adirondacks,” Martin said.
Additionally, by partially logging the area every 10 years or so, we barely cover our property taxes. “At the end of the day, there is very little break-even,” he added.
Some people in the local real estate and investment markets say young buyers are curious, although direct evidence is hard to find.
“As a millennial and a real estate agent, I understand the appeal. I’ve considered buying a Timberland myself,” said Jake Kennedy, a Nashville-based real estate agent, noting that his generation has experienced the dot-com crash, the Great Recession, a pandemic, wild swings in home prices, and now inflation. “One of the lessons we learned is that scarcity matters when it comes to where you put your money,” Kennedy said, adding that more IPOs could be announced or new cryptocurrencies created, for example.
“But we can’t produce another 500 acres,” Kennedy said. “Wood itself is a resource that takes decades to grow, and there is something reassuring about owning a tangible asset,” he added. But he also cautioned that wood’s durability doesn’t mean it’s profitable. Trees are fickle and can be subject to many fluctuations.
Kennedy said people he spoke to believe Timberland is a relatively safe place to park their money because the demand for wood products hasn’t gone away. “In the meantime, hunting is a common activity, literally while owners are waiting for their investments to grow and mature,” he said.
“I don’t think my generation will suddenly give up their homes and become timber kings. But I think we’re much more interested in alternative places to accumulate wealth than previous generations,” he added.
Timber ETF provides access to asset class
For many Millennials, homeownership is becoming increasingly difficult due to rising home prices, rising mortgage rates, and limited inventory in many markets. “As a result, some investors are looking for alternative ways to participate in real assets and potentially build equity without buying a home directly,” said Nadeem Kassam, chief investment strategist at Manoor Private Wealth Counsel.
Beyond direct or institutional ownership, there are timber ETFs and timber-focused funds that offer exposure to themes closely tied to long-term housing demand and construction activity, but they remain very niche investments in an ETF market currently worth trillions of dollars.
Mr. Kassam is a member of the iShares Global Timber and Forestry ETF (wood), with approximately $260 million in assets and the Invesco MSCI Global Timber ETF (cut), with assets of approximately $30 million.
“This investment deal is supported by persistent housing shortages in many regions of the United States and growing bipartisan support for policies aimed at increasing housing supply and improving affordability. If these efforts lead to increased housing construction over the long term, demand for lumber and wood products could benefit,” Kassam said.
However, he noted that investors need to understand that timber ETFs are not direct investments in forest land. Neither ETF owns trees.
“Most publicly traded companies are involved in timber, forest products, timber manufacturing and other parts of the housing value chain,” Kassam said, explaining that while the benefits are liquidity and accessibility, profits are not determined solely by timber prices.
WOOD’s largest holdings include: Weyerhaeusera major forest owner along with Brazilian pulp producers SuzanoNine Dragons Paper and west fraser timber. CUT is Svenska Cellulosa, UPM, Stora Enso, avery denison. WOOD has had net inflows of approximately $73 million over the past year, according to the ETF database.
“For investors priced out of the housing market, the Timber ETF may offer a way to participate in the long-term housing and construction story through a diversified and liquid investment vehicle. The key is to recognize that you are purchasing exposure to companies that benefit from housing-related demand, rather than direct ownership of land or residential real estate,” Kassam said.
Junyi Liu, an economics professor at Soka University in the US who studies international and development economics, said there are no signs of a boom, but forestlands have unusual characteristics as an alternative asset.
“Benefits can come from increases in biological growth, timber prices, land prices, and owners may have the option to delay logging if timber prices are unfavorable,” Liu said. But for individual investors, Liu added, it’s a much different story than “a simple ‘tree grows while you wait’ investment story.”

