
A portion of this article was published in CNBC’s Inside Wealth newsletter, a weekly guide for high-net-worth investors and consumers. Sign up to receive future editions directly to your inbox.
Family offices continued to increase their holdings in the third quarter, although they hedged their artificial intelligence deals with bigger financial bets, according to the CNBC Family Office Portfolio Tracker.
The family office increased its allocation to public equities to 36.4% of its portfolio in the third quarter, up from 35.6% in the second quarter, according to Tracker. The company’s stake is up sharply from 33.6% in 2024, a significant increase for a family office that rarely deviates from its long-term financial allocation.
CNBC Family Office Portfolio Tracker uses data from Addepar. Addepar is a foundational data and artificial intelligence platform used by financial professionals around the world, with over $10 trillion currently in its platform. Unlike surveys, Addepar’s data is aggregated and anonymized by examining, in real time, a portfolio of hundreds of single-family offices representing more than $1.4 trillion in total family office assets.
Whether due to passive market gains or aggressive buying, the increase in allocations to stocks shows that family offices are not retreating from the market despite growing concerns about the AI bubble and the downturn in tech stocks.
“We have been studying family offices for over 15 years and have demonstrated time and time again that family offices take a long-term view,” said Eric Poirier, CEO of Addepar. “But they prefer to stay invested. So thematically with the AI breakthrough, they remain exposed and risk-on.”
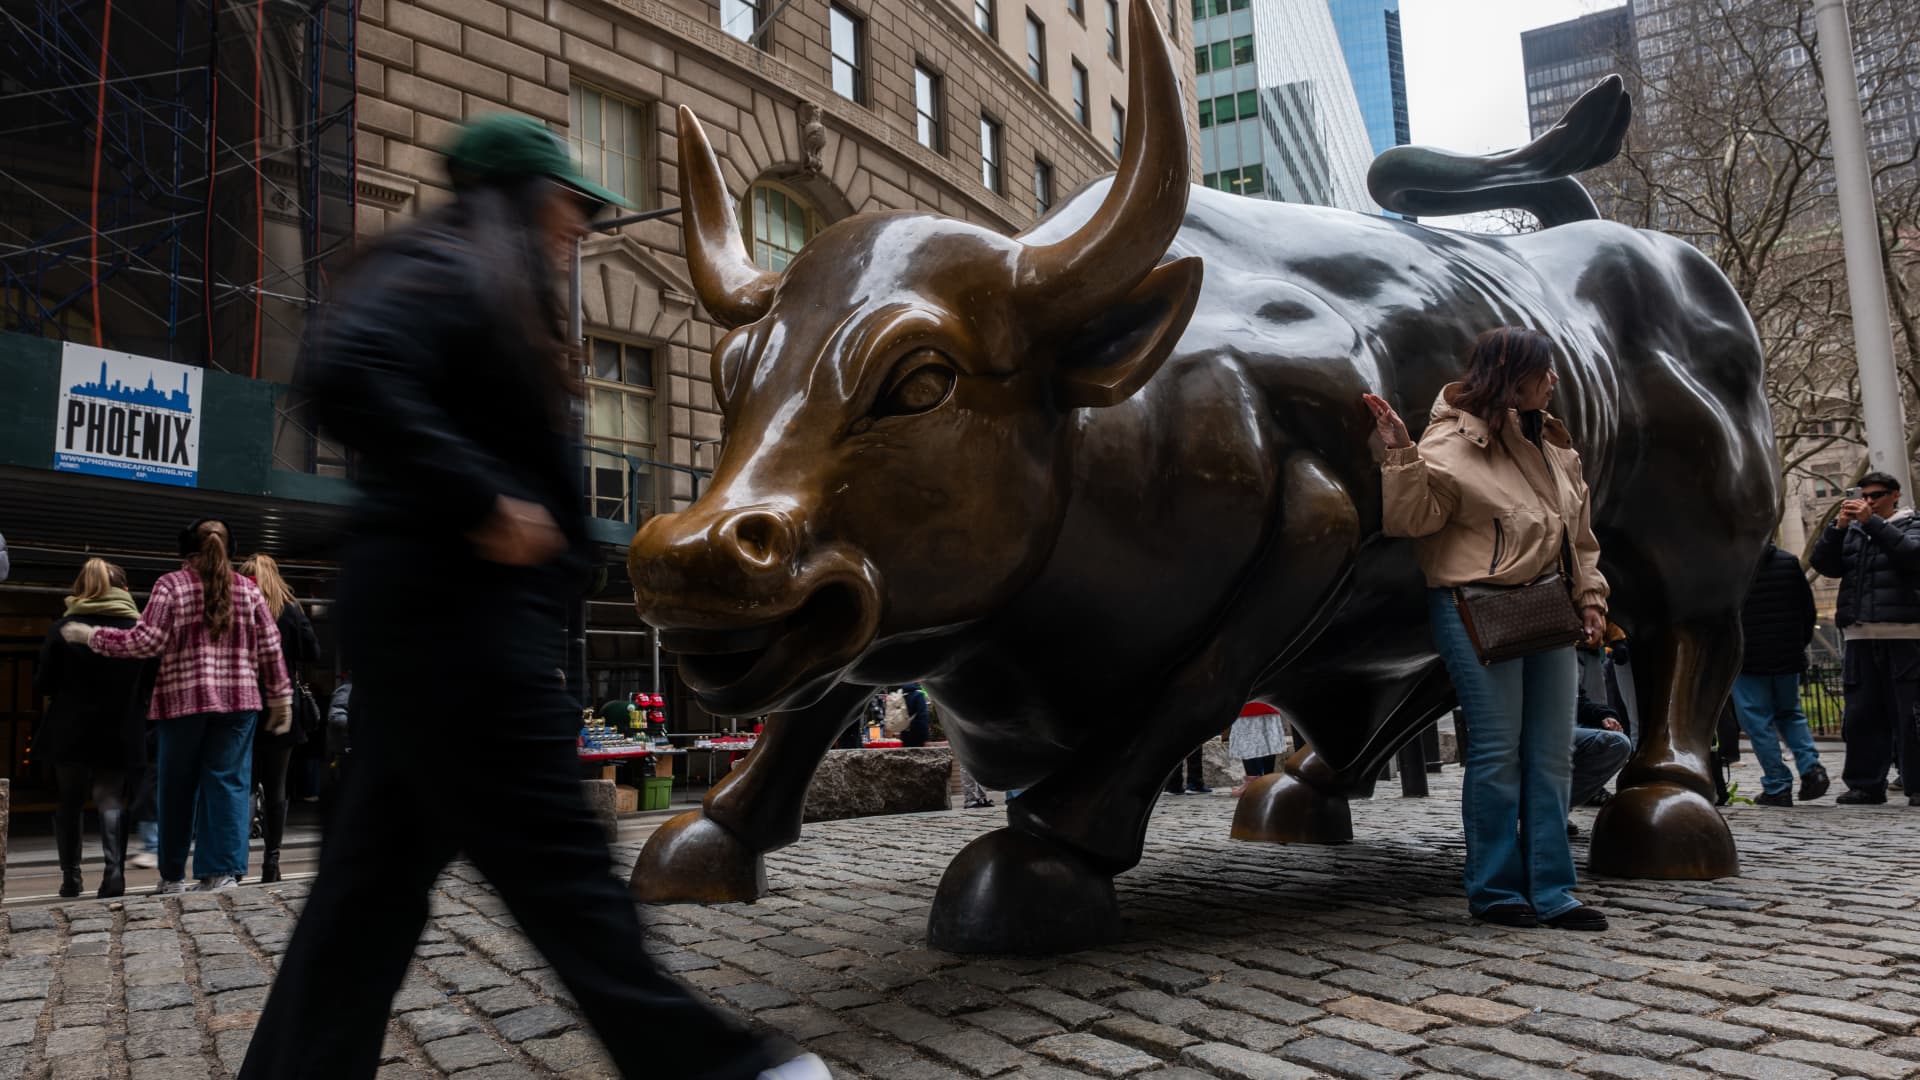
Wall Street bulls stand in the financial district of the New York Stock Exchange (NYSE) in Manhattan, New York City, March 19, 2026.
Spencer Pratt | Getty Images
At the same time, family offices are hedging their bets on technology. Compared to the broader S&P 500 index, family offices have lower exposure to AI stocks, according to Adepar. While tech stocks make up 40% of the S&P market capitalization, family offices allocate an average of 28% of their stock portfolios to tech stocks, according to Tracker.
They partially offset technology risks financially. Financial services makes up 11% of the S&P, while the average allocation to family offices is 18%. Poirier said the low technology weight and high financial exposure suggests family offices see financials as a potential offset to AI risks.
“Although AI trade is fading to some extent, it remains at considerable risk,” he said.
Family offices also continue to reduce their exposure to alternative investments. Alternatives accounted for 47% of the portfolio, down from 48.5% a year ago. The biggest decline was in real estate, which fell to 7.2% from 9.4% in Q3 2025. Rising interest rates are thought to have caused the valuations of many real estate portfolios and funds to fall, accounting for most of the decline.
Hedge funds also fell to 7.5% from 8.9% a year earlier, as many funds dealt with more volatile stock markets and falling tech stocks. Investments in private credit decreased slightly to 1% of the portfolio. The companies’ private equity holdings decreased for the second consecutive quarter, accounting for 6.4% of their portfolios.
Allocations to private companies (companies owned directly rather than through private equity funds) also fell. Family office holdings by private companies decreased by 0.3% to 15.7%, likely due to a slight decline in valuations. Still, private companies remain by far the largest segment within alternatives, as family offices continue to focus on direct investments.
Family offices’ cash piles increased slightly (8.6%), suggesting they want to have adequate dry powder on hand in case of a market correction or crisis.
The big question for family offices this year and next is how to deal with rising yields and inflation concerns. At the beginning of the year, some bet on infrastructure and real estate to protect against inflation, but oil prices pushed yields higher faster than most expected.
Family office bond holdings increased steadily for three consecutive quarters, reaching 8.1% in the third quarter.
“Family offices tend to be able to withstand market fluctuations better than other investors,” Poirier said. “However, their response to the historic rise in bonds and interest rates has been even more modest than the average over the past five years.”
