
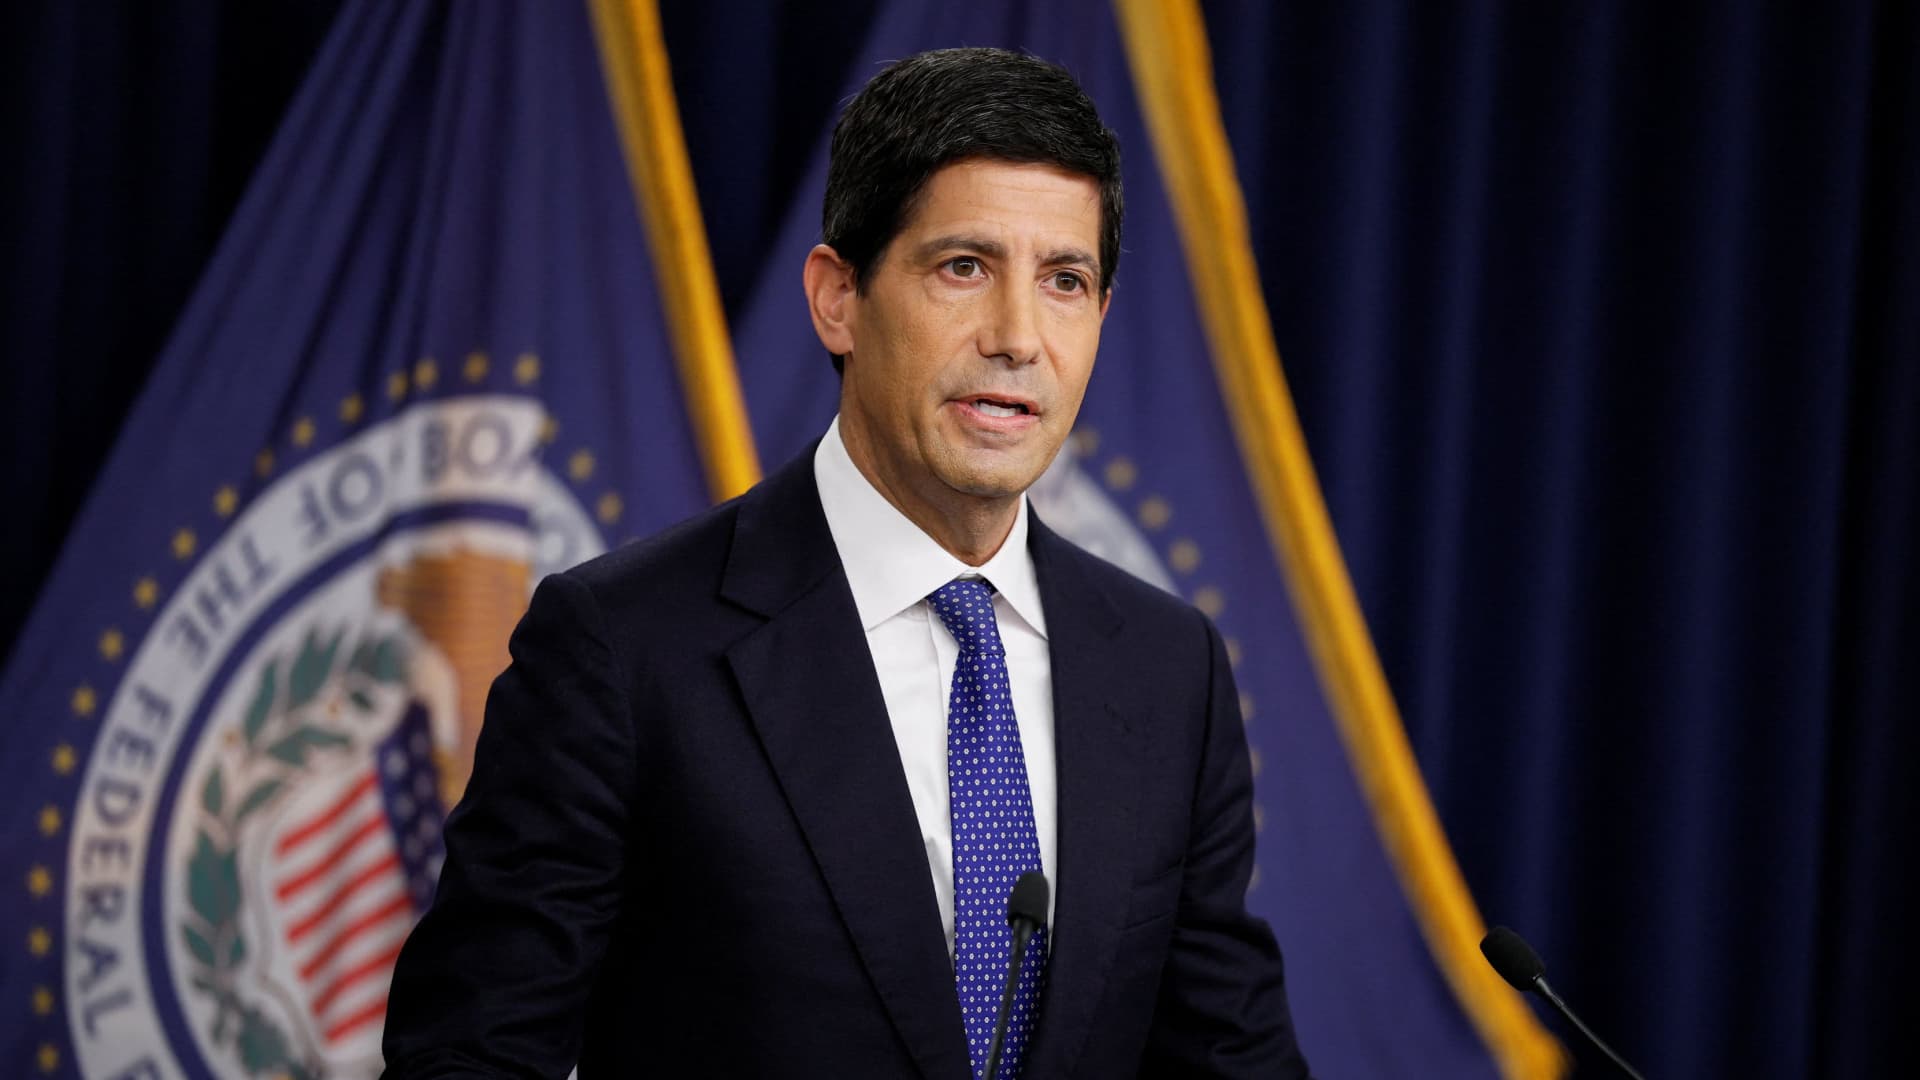
Federal Reserve Chairman Kevin Warsh holds a press conference after two days of Federal Open Market Committee (FOMC) meetings at the Federal Reserve Board in Washington, DC, USA on September 16, 2026.
Evan Vucci | Reuters
Traders overwhelmingly believe the U.S. Federal Reserve will not raise interest rates when it meets later this month. But that judgment is based, in part, on assumptions about how the Fed communicates that may no longer hold true under a new chairman. Kevin Warsh leaves room to maneuver for the hike in case he chooses to do so.
To be clear, Mr. Warsh made it clear Friday morning at an International Monetary Fund event in Bangkok that he was not suggesting a decision one way or the other. Still, his comments reinforce the market’s belief that the Fed will pause rate hikes, and as of Friday morning, futures markets were pegging the probability of an October rate hike at 15%. The decision followed remarks from other Fed chairmen, including top aides to traditional chairs, who indicated they felt comfortable holding the meeting.
Investors have good reason to hope the Fed will wait. But there are also cases in the inflation statistics that Mr. Warsh could bring to the Federal Open Market Committee on Oct. 28 to push for a rate hike. Investors are overlooking that case based on years of past experience with the Fed.
But the chairman has repeatedly rejected the practice of communicating his plans to the market before the committee meets. This raises the possibility that investors are becoming dangerously complacent about the likelihood of a rate hike in October.
That complacency is based on several grounds. One is that the Speaker’s executives are his spokespeople, or at least do not contradict him in public. That may have been the case in the past, but it may not be the case now.
In recent weeks, Fed Vice Chairman Philip Jefferson and New York Fed President John Williams have made statements suggesting there is little urgency to raise rates. The market quickly rallied in favor of holding October.
Mr. Warsh, Mr. Jefferson and Mr. Williams make up an informal decision-making team at the top of the Fed known as the Troika. Mr. Warsh could probably coordinate with the Troika, even if he is not confident in communicating his views. But outsiders are unsure whether the traditional practices surrounding the New York Fed’s president and vice chair’s public statements have survived the change in leadership.
Another assumption is that Mr. Warsh broadly accepts the FOMC’s economic views. “The world is broadly in line with our expectations,” Warsh said in Bangkok, regarding the economic situation since September.

This could be read as saying that relatively high inflation readings from the Consumer Price Index and Producer Price Index in recent days do not negate the views expressed in the Fed’s latest economic outlook summary released at the end of its September meeting. At the time, the median Fed official believed there would be one more rate hike in 2026, leaving room for a pause in October and another hike in December.
However, Warsh went out of his way to disavow SEP at a press conference in September. “That’s not my prediction,” he told reporters.
Warsh detailed his unique view of the economy in a high-profile speech in Jackson Hole, Wyoming, in late August. He said the economy is growing strongly and that inflation is more of a concern than the job market. Following Warsh’s strongly hawkish views, the FOMC unanimously decided to raise interest rates in September. His hawkish position depended largely on what he viewed as lax credit conditions.
The Chicago Fed’s National Financial Conditions Index has increased by about 0.05 points since Jackson Hole, but remains negative, indicating that although financial conditions have tightened, overall conditions remain lax.
Does Warsh believe the market has done the job for him? Is it enough to “undo a certain amount of adjustments”, as he said Thursday? We can speculate on these answers, but we won’t really know until the FOMC press conference.
Next is the inflation data. In the year to September, the consumer price index rose 3.7% and the producer price index rose 6.3%. The new data suggests that core personal consumption spending, the next measure of inflation recommended by the Fed, will be 3.1% year over year. Comprehensive PCE, which is affected by energy prices, will be even higher.
Warsh went out of his way to say numbers at that level are problematic. Economists questioned whether Mr. Warsh would allow inflation to exceed 2%, but Mr. Warsh made it clear in Jackson Hole that there should be “no misunderstanding.” The Fed’s 2% PCE target is “a solid fixed goal.”
Warsh is clearly learning on the job. He may be beginning to understand that the Fed chair cannot act alone and must rely on the support of the FOMC staff and other members to do his job. Similarly, he may find that the market is not sending clear signals independent of the Fed.
However, the truth in these matters is still not guaranteed. Mr. Warsh could come into the October meeting prepared to shore up shaky committee members based on growing demand for AI investments and warmer inflation statistics. Alternatively, after evaluating the committee’s opinion, you could sit in the middle of the committee and move closer to the center.
Warsh still has the potential to surprise us, and it would be dangerous to assume otherwise.
