
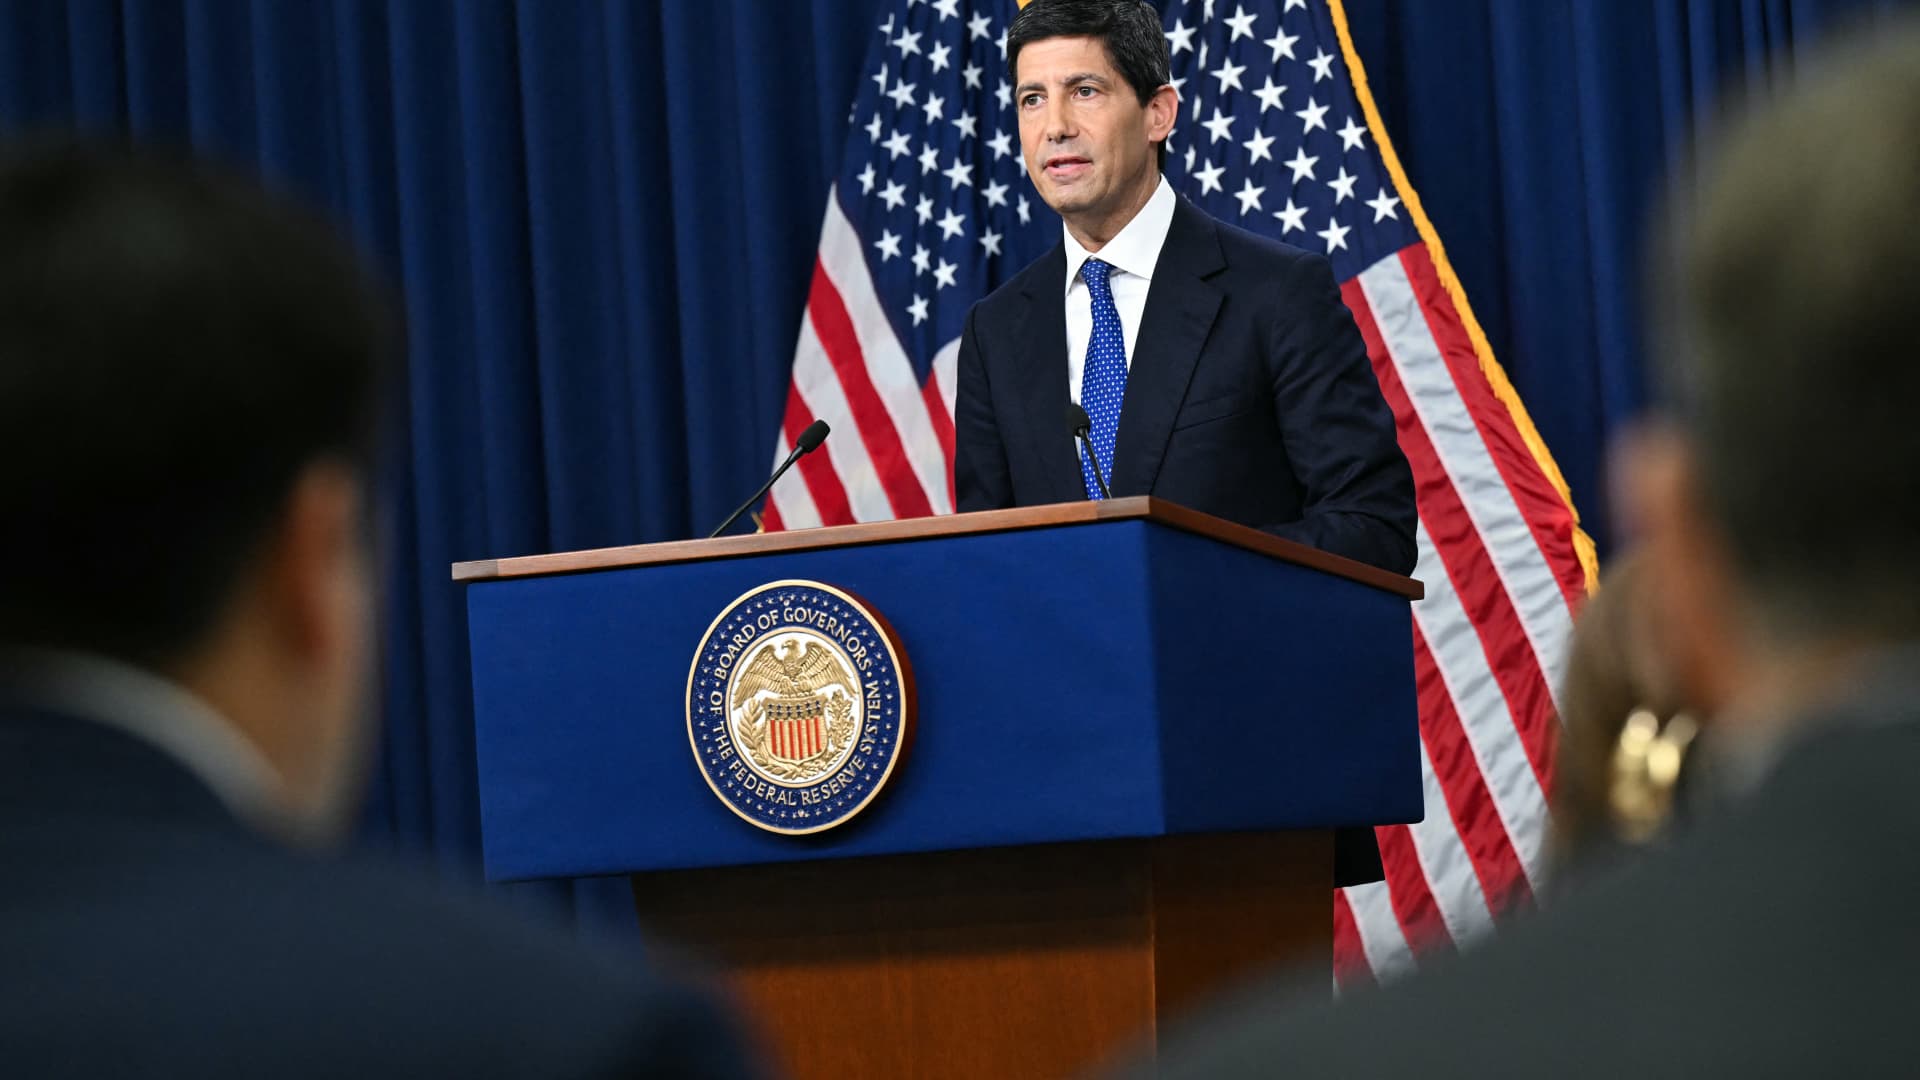
U.S. Federal Reserve Chairman Kevin Warsh speaks during a press conference at the William McChesney Martin Jr. Federal Reserve Building on September 16, 2026 in Washington, DC.
Saul Loeb | AFP | Getty Images
The Fed has a lot of work to do. But that won’t be possible in October.
That’s a key finding in CNBC’s latest Fed survey of 30 fund managers, strategists and economists, which found that 93% expect a pause at the Fed’s board meeting this week, and 76% expect a rate hike at its next meeting in December. More than half of respondents said they would raise interest rates by an average of about two times next year.
“Their reluctance to raise rates after a long period of generous monetary and fiscal policy, with nominal GDP hovering between 6% and 8% and leading indicators of inflation moving uniformly from warm to hot, is unfathomable,” said Richard Bernstein, global head of macro investing at Janus Henderson Investors.
More than 40% say the Fed needs to slow growth below potential to solve the inflation problem. In contrast, 27% said the Fed does not need to slow the economy, and 23% said the Fed needs to slow the economy slightly.
The survey, conducted by CNBC before each Fed meeting, found that 70% believe inflation is a broader problem than simply rising energy prices. The U.S. crude oil benchmark is expected to reach $88 a barrel in six months, up from $82 in the September survey but below the current level of $101.
When asked what the Fed should do at this meeting, 30% said it should raise rates now. Survey respondents expect at least two Fed voters to oppose the decision to keep rates unchanged.
“The aggregate demand data (probably above 7%…) and the inflation data point to a strong need for rate hikes,” said John Riding, chief economic adviser at Briand Capital.
Not everyone agrees. Some people are concerned about the economic slowdown.
“The Iran war is escalating, real wages are falling, interest rates are rising, and the AI-powered stock market looks volatile,” said Mark Zandi, chief economist at Moody’s Analytics. “Inflation is high but shows little sign of taking hold. Now is not the time for the Fed to raise rates again.”
Among a number of shocks and challenges, including high inflation, expected Fed rate hikes, and persistently high oil prices, respondents still see economic growth as above potential or at a level that does not cause inflation or deflation. This year’s GDP forecast has risen to 2.4%. Although this has declined slightly since the previous survey, it is still above the potential growth rate of 2.2% in 2027. The growth rate in 2025 was 2.05%.
In total, respondents put a 26% risk that the U.S. will enter a recession next year, down from 29% in the previous survey.
The outlook for the S&P 500 index this year is stable at around 7,600, but next year’s outlook is 8,033, down from 8,274 in the previous survey. The index closed at 7,676 on Monday.
The unemployment rate is expected to remain flat at 4.2% for the remainder of the year, but rise to 4.4% by 2027. The consumer price index is expected to fall to 3.6% from the current pace of 3.7% in September, but will fall significantly next year to 2.6%.
The biggest risks are the continuation of the Iran war and the bursting of the artificial intelligence bubble.
“Fed Chairman Warsh needs to reiterate this belief in future conversations with President Trump. The quickest way to lower U.S. inflation is to eliminate tariffs and end the Iran war,” said Rob Morgan, senior vice president and market strategist at Mosaic.
When it comes to high bond yields, about the same percentage of respondents say high inflation, high growth, high debt issuance, and expectations for higher federal funds rates are the causes. When asked specifically about which supply is causing the bigger problem, 50% cited government debt and 13% cited debt to fund AI buildout. However, a third said both contributed equally to the rise in yields.
On average, respondents expect the 10-year Treasury yield to remain above 5% this year, but to decline slightly to 4.8% in 2027.
“As stubborn inflation persists amid energy and trade pressures… benchmark Treasury yields above 5% represent a new range rather than an anomaly,” said Subodh Kumar, president of Subodh Kumar & Associates.
Parliamentary elections are also seen as a market risk, with 63% saying there is a market risk from legal challenges that could increase uncertainty about which party controls parliament.
“The potential for prolonged election uncertainty is one of the biggest short-term risks to markets, and we all know how markets hate uncertainty,” said John Donaldson, director of fixed income at Haverford Trust.
More than half of respondents said the most likely outcome of next week’s congressional elections is for Democrats to control both chambers, up from 29% in the previous survey. 40% believe Democrats will eventually control the House, but not the Senate.
While most people expect little change in personal and corporate taxes as a result of the election, 41% expect the budget deficit to widen. But that concern is not related to which party is expected to control Congress. Individual growth projections also differed little based on which party respondents thought would control Congress.
