
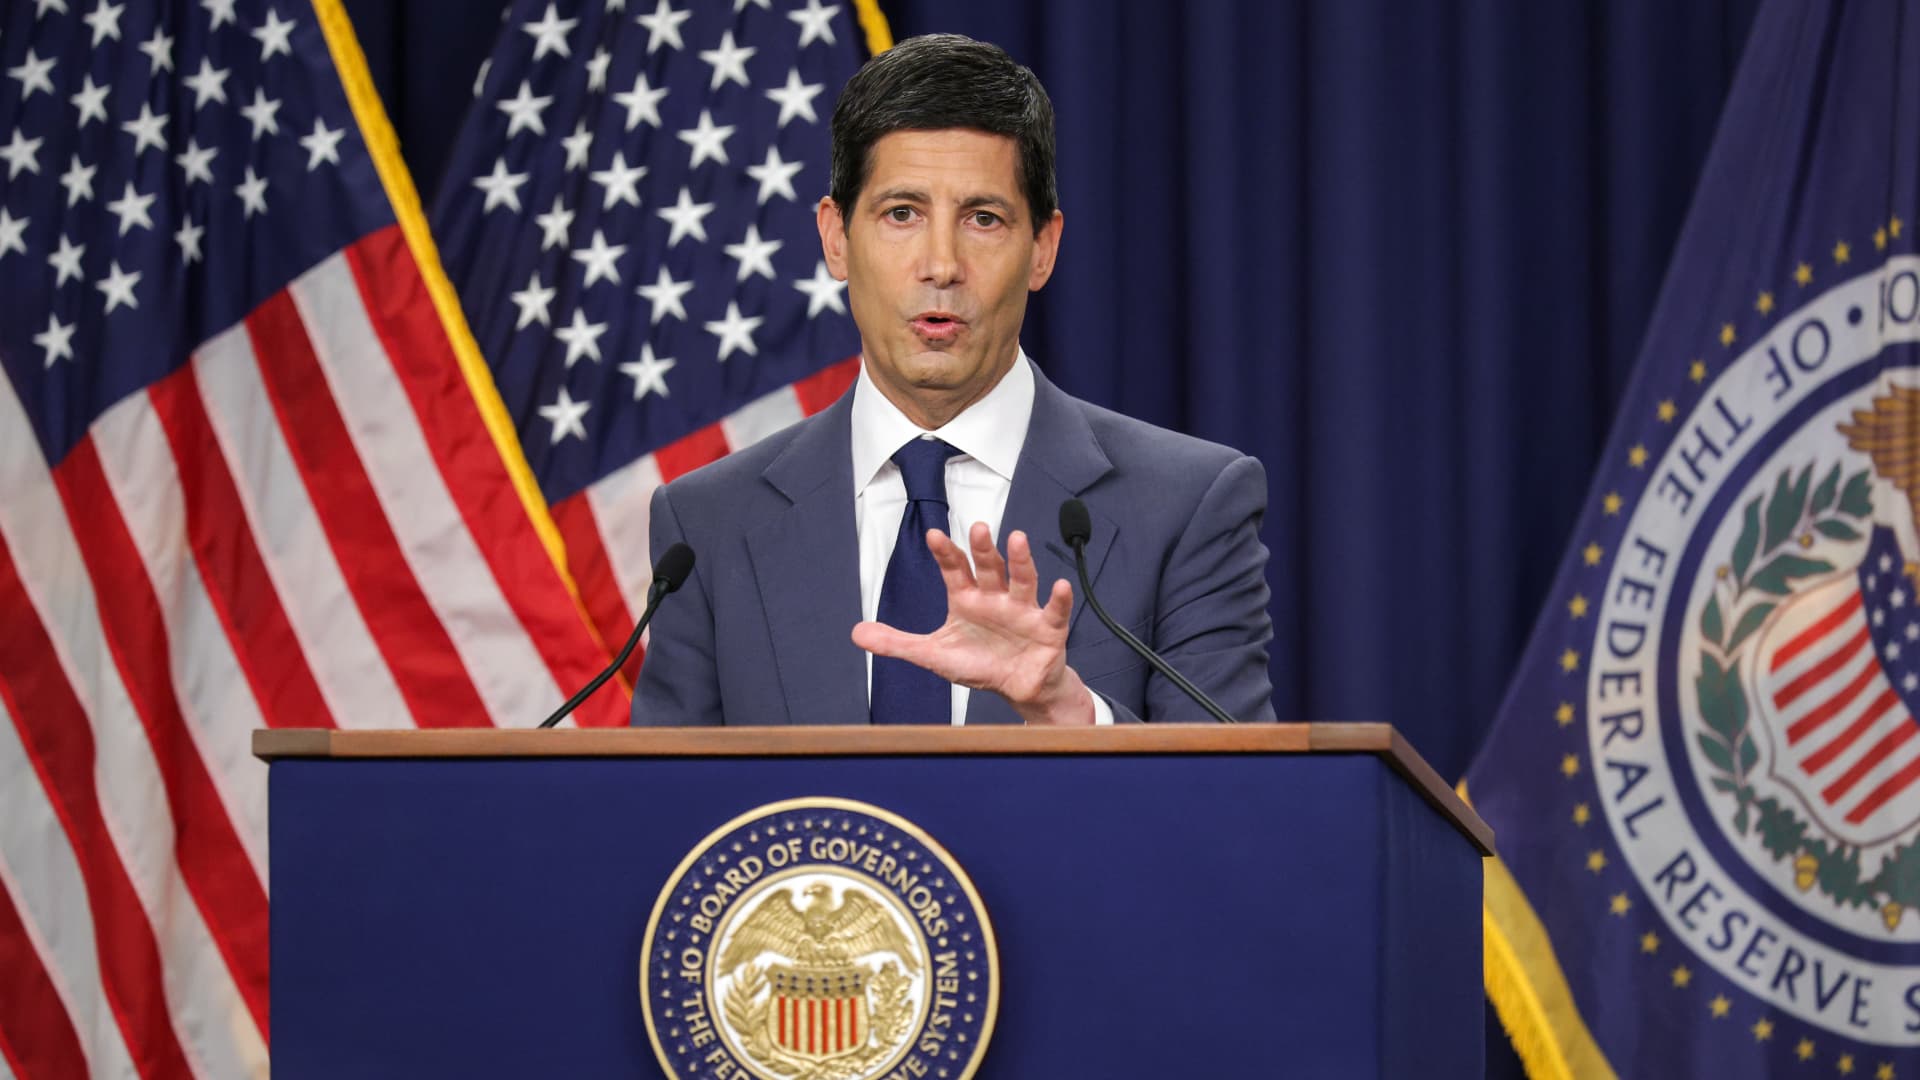
Federal Reserve Chairman Kevin Warsh answers questions during a press conference after the Federal Open Market Committee at Federal Reserve Headquarters in Washington, DC, October 28, 2026.
Alex Wong | Getty Images News | Getty Images
Kevin Warsh has proven himself.
The Fed chairman’s press conference on Wednesday was a sharp contrast to his early days in office, when he often seemed cornered. He has shown he is willing to let the market guess where he ends up, at least to some extent. He then used that authority to begin restructuring the organization.
Mr. Warsh was appointed by the president, who said lowering interest rates was a litmus test for selection as Fed chairman. When the Federal Open Market Committee chose to keep interest rates unchanged in June and July, even though inflation remained well above the Fed’s 2% target, many commentators questioned the new chairman’s credibility. Then, the FOMC’s decision to raise interest rates in September, coupled with Mr. Warsh’s very hawkish view of the economy, sent the market swinging sharply in the opposite direction. Investors thought the Fed would be locked in a rate hike this week until two senior officials came forward and deliberately tried to temper market expectations.
This week, Warsh forgot all about that. He dismissed expectations that the Fed was moving in any direction, saying, “If we come to a firm conclusion about how we conduct monetary policy, we will announce it in a big way today.”
But Warsh also strongly hinted at the current preference for interest rates to rise. “The overall financial situation is tight, but I don’t want to say it’s tight, I can’t say that,” he said.
He was keeping his options open, laying the intellectual groundwork for a rate hike in December in case inflation remains robust.
Mr. Warsh declined to confirm the widespread assumption in the market that officials who spoke to the market were doing so at his direction. Fed insiders say the Fed vice chair typically coordinates messaging with the Fed chair.
“It’s not the FOMC committee that I know that would suggest that I’m some kind of omniscient person who is sending a message,” Warsh said. Still, the market got the message that the Fed will not raise rates this week. If Mr. Warsh wants to provide taboo positive guidance through his lieutenants, he now has a plausible deniability.
This is Warsh’s MO. He is intellectually flexible and very focused on achieving his goals.
For example, one of the goals of the task force he formed to initiate policy changes is to change the way the Fed measures inflation. But that wasn’t possible while his commitment to fighting it was questioned. The rate hike in September is a big response to skeptics who say he is not serious about curbing price increases, and he is prepared to raise rates further if necessary.
“If you think we’re okay with an inflation target of less than half that, I want you to stop doing that,” Warsh said Wednesday. The target is to remain flat at 2%. His comments are a recipe for higher interest rates as long as the economy is doing well.
Mr. Warsh and the FOMC will have a wealth of new data to make their case before their next meeting in December. That, in turn, could help him argue that productivity is rising and further growth is possible without inflation.
Meanwhile, Mr. Warsh’s other changes at the Fed are starting to take effect. On Wednesday, he announced plans to reduce the number of interest rate votes scheduled at the FOMC over the next two years. The Fed will continue to meet eight times a year, but will omit voting on interest rate changes at its first meeting in 2027 and its second meeting in 2028. This move has the effect of devaluing a significant portion of Fedospeak. Markets won’t pay much attention to comments from minor regional Fed presidents, which come less than three months before a decision to cut interest rates. Regional presidents will also receive one less vote in their annual rotation as FOMC decision makers.
The Fed Chairman has the authority to convene an impromptu meeting at any time if he determines that a change in interest rates is necessary.
The Mariner S. Eccles Federal Reserve Building under construction in Washington, DC, on September 15, 2026.
Mehmet Ethel | Anadolu | Getty Images
But there are risks to Warsh’s way of doing business, especially as he retreats further behind the curtain. Supporters of Fed transparency believe daylight will bring more rigor to officials’ claims.
Robert Sockin, chief U.S. economist at asset management firm PGIM, said that may already be a problem. He is in the camp that thinks inflation is too hot to justify the Fed’s decision not to raise rates this week.
“The more data we have, the better, but Mr. Warsh did not fully explain why this context does not justify raising rates, especially given his comments that he thinks financial conditions have tightened, but he does not say they have tightened,” Sockin said.
Holding it in place would be a “policy error,” Sockin said, adding, “If the Fed were to raise rates more gradually, that would probably mean they would have to raise rates more mechanically, which would mechanically increase recession risk.”
The full results of Mr. Warsh’s approach may not become clear for months. This gives him more room to take steps to restructure the Fed. But it also means that the consequences of waiting for tightening may not become apparent until it is too late.
