

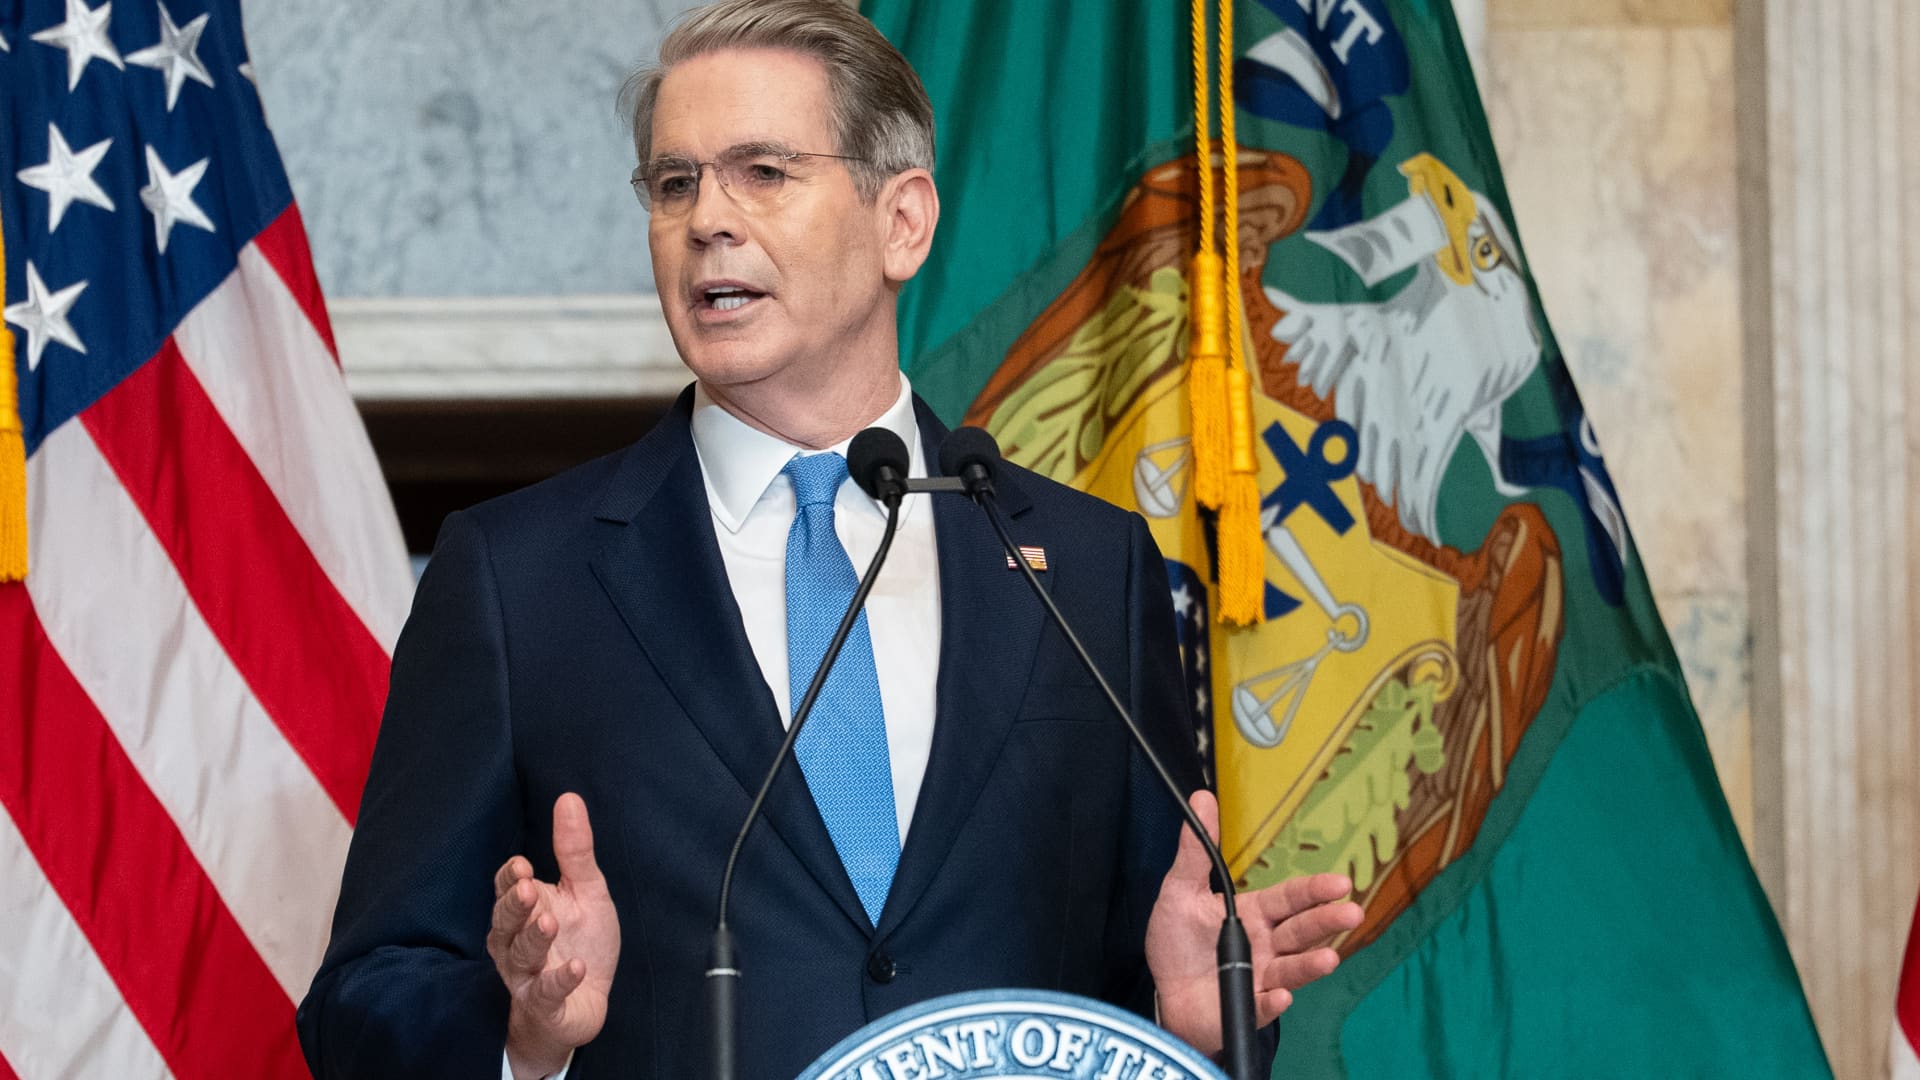
U.S. Treasury Secretary Scott Bessent delivers remarks at the launch of Cultivating Future Accounts at the U.S. Department of the Treasury, Thursday, June 11, 2026, in Washington, DC, USA.
Aaron Schwartz | Bloomberg | Getty Images
Treasury Secretary Scott Bessent is in the midst of a historic effort to push long-term Treasury yields down. He could also complicate the job of his Fed counterpart, Chairman Kevin Warsh.
The Treasury Department announced Wednesday that it would expand buybacks of long-term government bonds, raising the cap on purchases from $2 billion to at least $4 billion. The intervention helped stem the sell-off in the U.S. bond market that has pushed yields to uncomfortable levels in recent days. The stock selloff dominated global headlines as investors worried that rising U.S. bond yields would worsen the consumer affordability crisis, complicate corporate borrowing plans, threaten stock market profits and make ballooning government debt more expensive to finance.
Although the buybacks are small compared to the outstanding bonds, many in the market interpreted the Treasury’s new buyback plan as a powerful symbol of Mr. Bessent’s longstanding efforts to lower yields on 10-year Treasuries and other maturities.
But bond traders and economists say doing so risks accelerating inflation and makes the cost of financing the nation’s $32.2 trillion in debt more sensitive to potential rises in interest rates. This would put pressure on an independent Fed to support the administration’s policies.
“The logic of populism is gradually moving to a stage where the logic of populism demands that central banks support fiscal goals,” said Joseph Brusuelas, principal and chief economist at RSM US.
President Donald Trump has asked the Fed to lower interest rates to ease the burden of financing the federal debt while also increasing the debt. According to the Congressional Budget Office, this year’s federal budget deficit is expected to reach $2.1 trillion.
“That will cause market distortions, and the kind of intervention we saw this morning will make Kevin Warsh’s life even more difficult,” Brusuelas said.
Stated purpose: market liquidity
Officially, bond buybacks are aimed at improving market liquidity for less traded instruments, in other words, ensuring there are enough buyers and sellers in a given market to establish reliable prices. In this case, the Ministry of Finance aimed to remove long-term maturities between 10 and 30 years from the market.
The market has been calling on the Treasury Department to expand share buybacks for many years. Newly issued bonds tend to trade with healthy liquidity, but maturities shorter than the original issue period may result in a lack of buyers later on. For example, a 30-year Treasury note issued in May 2020 with 24 years left to maturity traded at about 45 cents on the dollar on Wednesday. Removing these so-called off-the-run securities from the market frees up financial institutions’ balance sheets to buy more liquid stocks, which could put downward pressure on interest rates.
The Treasury Department is not paying down debt or implementing a quantitative easing program like the Fed.
“The Fed can print money and buy whatever it wants,” said Brij Khurana, a fixed income portfolio manager in Wellington. “The Treasury doesn’t have that capacity. The Treasury needs to issue more notes to fund share buybacks,” he said.
But that’s where Bessent’s actions are so controversial. The Ministry of Finance is expected to manipulate the yield curve by replacing long-term government bonds with short-term government bonds, rather than replacing them with long-term government bonds.
While this is expected by market participants, the Treasury itself did not specify in its announcement how it would finance the share buyback. The ministry did not respond to requests for comment.
The bond selling quickly reversed due to the announced share buybacks. Bond prices move inversely to yields.
Since the outbreak of the Iran war, 10-year Treasury yields have risen nearly 70 basis points, recently peaking at 4.74%, and 30-year mortgage rates have risen to about 6.75%. After news of the Treasury’s stock buyback broke, the 10-year bond yield fell to 4.63% and ended the day at 4.65%.
Bessent criticizes Yellen
The share buybacks follow two other recent actions that effectively stopped long-term Treasury yields from rising.
Bessent used Treasury funds in July to support Japan’s troubled currency, the yen, but chose to sell euros rather than dollars in the trade. He also urged the Fed to expand its facilities to allow Japan to lend rather than sell its bond holdings in case of future intervention.
And on August 5, the Treasury announced that it plans to continue its recent practice of issuing relatively more short-term debt compared to long-term trends.
This appears to contradict the recommendations of his own Treasury Borrowing Advisory Committee. Treasury bills currently account for 22.2% of Treasury debt, above the rough 20% limit recommended by TBAC, a nonpolitical association of market experts.
In 2024, Bessent criticized her predecessor, Treasury Secretary Janet Yellen, for adopting a similar policy of increasing the issuance of Treasury bills. He chalked it up to Yellen’s focus on market size to limit the cost of overspending. Warsh similarly criticized the Fed’s bond purchases, saying they keep yields low and open the door to excessive spending by Congress and the administration.
TBAC also warned the department against politicizing stock buybacks. TBAC said in July 2025 that share buybacks are useful when the purpose is to solve market liquidity problems, but not when they change the so-called debt profile or change the debt balance between long-term and short-term redemptions.
“The committee feels strongly that issuance is a key tool for managing the debt situation,” the minutes stated.
How it could backfire
How the Treasury manages its large Treasury debt profile can have significant implications for taxpayers. The federal government made $963 billion in net interest payments in the first 10 months of fiscal year 2026, according to the Congressional Budget Office. Debt repayments account for about 15% of fiscal spending.
As the maturities of the federal debt are further shortened, its payments become more sensitive to rising and falling interest rates. If the Fed chooses to raise rates, the government’s interest payments will rise rapidly. Bessent’s decision to issue more short-term debt could backfire.
Also, suppressing long-term interest rates could increase economic activity and increase the threat of inflation. “The risk that inflation will remain high is increasing, and the Fed will need to continue raising interest rates,” Khurana said.
The dollar fell nearly 0.8% against a basket of other currencies on Wednesday following Bessent’s buyback. Khurana said imports could become more expensive and inflation could rise.
At the Fed, Warsh left investors uncertain about his future plans after his most recent press conference on July 29. He said he was concerned about inflation, which has been above the Fed’s 2% target for more than five years, but he did not raise rates and did not say explicitly what would prompt him to change his mind. He also indicated that he believes the market has done the job for him in driving up long-term bond yields.
Bruelas also noted that Warsh wants unfiltered messages from bond prices to make policy decisions more closely tied to market interest rates. But Mr. Bessent’s efforts to push down long-term yields through a variety of interventions threatens to cloud those signals.
Warsh’s comments spurred a sell-off in long-term bonds.
Mr. Warsh will have an opportunity to address these issues next week at the central bank’s annual meeting in Jackson Hole, Wyoming.
But Brusuelas said the Fed will likely face long-term pressure to align its policy with the Treasury Department.
“I think this is a path that will lead to major policy mistakes over time,” he said.
