
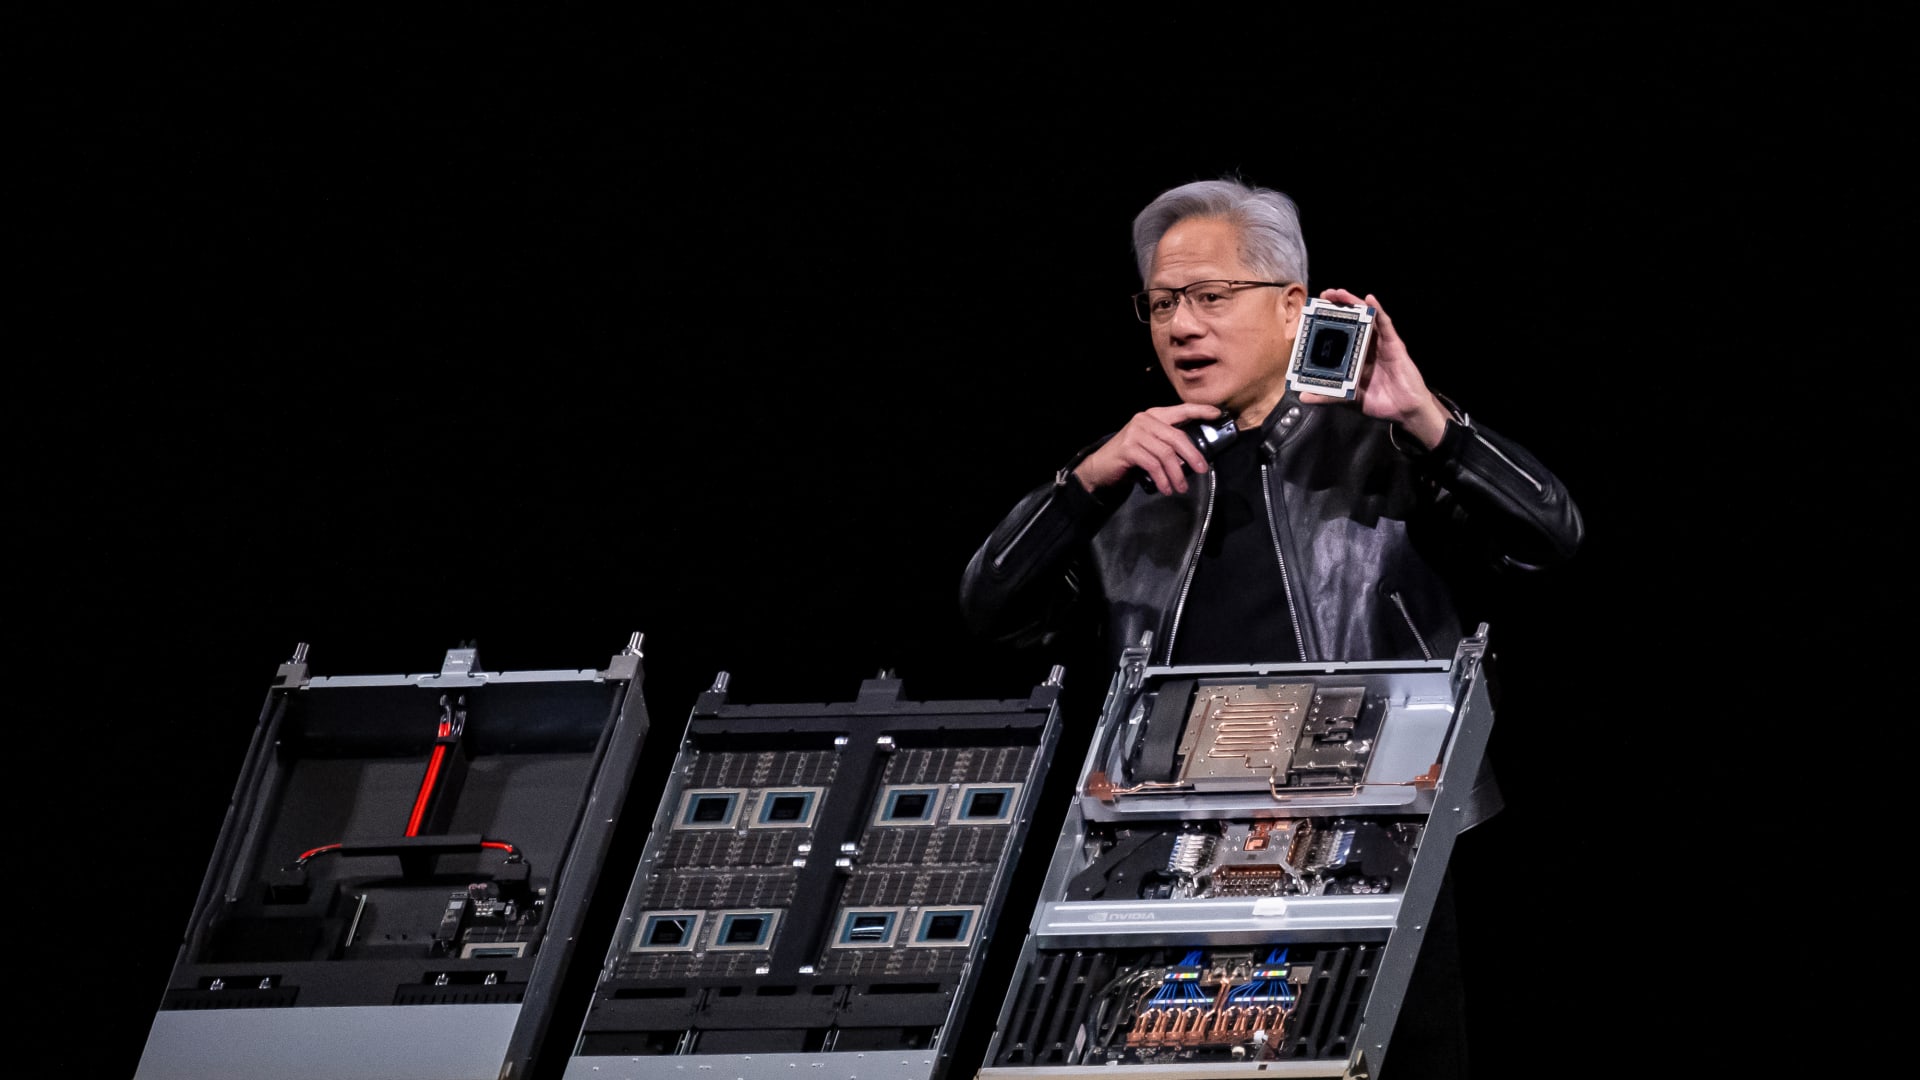
Nvidia Corp. CEO Jensen speaks while holding a Spectrum-X Ethernet photonics chip next to, from left, a BlueField-4 STX storage tray, a Vera CPU compute tray, and a Spectrum-X Ethernet photonics switch system during the keynote address at the Nvidia GTC conference on Monday, March 16, 2026 in San Jose, California, USA. Mr. Fan.
Bloomberg | Bloomberg | Getty Images
Nvidia is a revenue driver of the artificial intelligence boom, filling data centers with graphics processing units and powering some of the largest AI models.
But if there’s one persistent concern among investors about NVIDIA’s ability to further expand its $5 trillion market capitalization, it’s customer concentration. Nvidia is counting on a group known as hyperscalers — Amazon, google and microsoft These companies buy GPUs in bulk for their workloads and sell access to them through their massive cloud businesses, resulting in huge profits.
In addition to that meta and space xhas become a large buyer by building its own models, while also starting to rent out some of Nvidia’s capacity to other companies that need it quickly.
Nvidia changed its financial reporting methodology in its last earnings call in May, separating hyperscalers from the rest of the group and now grouping them as AI Cloud, Industrial and Enterprise, or ACIE. Nvidia hasn’t said which companies fall into the former group, but CEO Jensen Huang has defined the group pretty clearly.
“Of course, the easiest to enter the market are the hyperscalers, because there are only five or six hyperscalers,” Huang said on an earnings call in May. “The rest of the companies, the rest of the industry, represents 250,000 companies around the world.”

After the bell Wednesday, the ACIE portion of the customer base will be under the microscope as Wall Street prepares for Nvidia’s fiscal second-quarter earnings report. In the first quarter, the two segments were roughly equivalent, with Nvidia reporting hyperscaler sales of $37.9 billion and ACIE sales of nearly $37.5 billion. Nvidia highlighted that ACIE’s revenue increased 31% sequentially, outpacing the hyperscaler’s 12% growth.
Skepticism is starting to permeate stock prices. The stock fell 2.9% on Monday, the seventh straight day of losses and the longest losing streak since 2022. During that time, the stock price fell 7.5%.
Nvidia stakeholders want the company to become less dependent on some customers and are also concerned about whether those companies will be able to increase spending further. Amazon and Alphabet turned cash flow negative in the second quarter, and Meta’s cash generation fell more than 90% from a year earlier. SpaceX, Elon Musk’s publicly traded company, and tesla — Reported negative free cash flow as it pursues AI expansion.
“Behind the scenes, this story is about investors’ concerns about how sustainable Nvidia’s operations are, and the hyperscaler feels it can’t do better,” Gene Munster, managing partner at Deepwater Asset Management, said in an interview. “They want to see other segments start to move.”
Other businesses grow faster
In May, Nvidia published a revised history for the past nine quarters on its website showing that hyperscalers accounted for about 55% of data center revenue over the past year. The hyperscaler’s revenue increased 115% year-over-year in the most recent quarter, outpacing ACIE customers’ 74% growth.
Analysts expect the trend to reverse in the future. According to StreetAccount, the ACIE side of the business is expected to grow 149% annually over the past year to $43 billion in the second quarter, while the hyperscaler’s revenue could rise 83% to $43.6 billion. Munster said one potential big driver of the hyperscaler business is SpaceX, which aims to rapidly build out Nvidia-based data centers over the next year.
In total, analysts expect Nvidia’s revenue to nearly double from a year ago to $92.2 billion, according to LSEG. Data centers will continue to account for the majority of sales, with the sector expected to reach $86.3 billion, based on Street Account estimates. This is 94% of the total, up from 92% in the first quarter.
Analysts expect full-year sales to rise 83% to $396 billion, but growth will slow to 44% next year, LSEG said.
In its efforts to diversify, Nvidia is being proactive rather than waiting for new customers to arrive. Nvidia recognizes that few companies have the cash or balance sheets to support the purchase of rack-scale systems, and is working with Wall Street to turn GPUs into an asset class.
Earlier this month, NVIDIA, along with six major financial companies, announced a program that could raise up to $500 billion from investors who view chips as investable assets similar to real estate. Huang said such projects could allow more companies to borrow money at low interest rates to buy GPUs, since the chips are profitable.
Nvidia said in the announcement that it had signed a memorandum of understanding with the investment firm. Almost no specific details are provided.
“There’s a lot of headlines, a lot of big numbers, but we still don’t have a lot of details about how this is going to work,” Bernstein analyst Stacey Rasgon told CNBC last week. “We can give it some color to help put investors’ minds at ease.”
Another important number in Nvidia’s earnings report is its Vera Rubin system sales, which have recently begun to increase. Earlier this year, Huang told attendees at the company’s GTC conference that he expects current-generation Blackwell and Vera Rubin sales to reach $1 trillion by 2027.
If Vera Rubin proves even more successful than expected, questions about the long tail of its customer base may allay.
Analysts at KeyBanc, which recommends buying the stock, said in a note over the weekend: “We expect NVIDIA to post strong operating results and guidance, with increased Rubin GPU shipments being the primary driver of upside.”
Watch: Inside Nvidia’s Vera Rubin AI system

