
For years, subscription businesses have benefited from a simple fact of consumer behavior. That said, people are far better off signing up than canceling.
They forget what they were a part of. They continue to pay even if they stop using the service. A $9 or $15 monthly fee can disappear on your credit card statement for months or even years.
With the launch this month of Meta Muse, an AI personal agent that can handle tasks across multiple areas of personal life, it quickly became clear that subscription bloat was an easy target.
Muse helps consumers identify and cancel subscriptions. Subscription management services have been around for years, but Muse could bring that functionality to a broader range of personal assistants, making it easier to find and cancel forgotten recurring charges.
And timing is important. Nearly half (44%) of U.S. consumers will increase their subscription spending in 2025, increasing average annual spending to $1,887, or about $157 per month, according to a report released in April by Mastercard and FT Strategies. Subscription spending in July increased 7.7% year over year, outpacing overall card spending, with entertainment and retail subscriptions accounting for about 43% of the total, according to Bank of America payments data.
Neil Mahoney, a professor of economics at Stanford University and director of the Stanford Economic Policy Institute, looked at how much profit subscription companies make if consumers don’t cancel.
“We found that when faced with a decision, people were about four times more likely to cancel,” Mahoney said, citing data from the 2025 American Economic Review paper “Subscription Sales,” co-authored with Stanford University economists Rylan Einav and Ben Klopak.
In the world of AI agents, this distinction is important.
Researchers at Stanford University estimate that consumer inertia, where people forget or put off canceling, and cancellation friction, where ending a subscription takes a lot of time and effort, can roughly double revenue for sellers. Mahoney said AI personal agents could undermine both. But not all subscriptions are equally vulnerable. He said physical subscriptions, such as pet food, are hard to forget when they keep arriving at your door, but digital services like credit monitoring can quietly keep charging you long after you’ve stopped thinking about them.
Ultimately, this intervention of AI personal agents into consumer psychology could have an impact far beyond subscriptions, impacting decision-making deep within the core financial services that banks take for granted today.
“Muse and similar agent-based AI assistants could automatically direct household cash into accounts paying between 3.3% and 5.0%, rather than the national average of 0.1% for checking accounts,” Torsten Slok, Apollo’s chief economist, wrote in an analysis last week. “If households use AI agents to optimize the rate of return on their cash balances, banks could lose a large portion of the cheap deposits they rely on for loans, which would be problematic for the entire financial system.”
“So much of life is becoming a recurring bill.”
Consumers were already becoming more willing to cut back on their subscriptions.
ScribeUp, which builds subscription management technology into banking apps for banks, credit unions and fintech companies, says members are now 1.8 times more likely to initiate a cancellation than they were a year ago.
“We’re seeing more and more recurring bills in our lives, and those bills are getting higher every year, making it increasingly difficult for consumers to understand everything they’re paying for,” said Jordan Mackler, co-founder and CEO of the company. He said this increase predates ScribeUp’s new AI capabilities and reflects broader changes in consumer behavior.
According to the company, the median ScribeUp user currently makes 12 or more subscription payments, and one in four makes 20 or more payments. Additionally, the percentage of users with 8 or more users has increased from 62% to 71% over the past year.
Rising prices could accelerate withdrawals. Mackler said cancellations at individual merchants could jump by as much as 50% as prices rise. Mackler said health and fitness subscriptions are seeing the biggest jump in cancellation activity, with a 3.8x increase year-over-year, followed by video streaming at 2.2x, news and media at 2.1x, and music streaming at 1.9x.
Mackler said ScribeUp is increasing the number of subscriptions that AI helps consumers manage. The company currently tracks approximately 200,000 individual recurring billers. Before adding new agent capabilities this year, we were able to automate cancellations for only a few hundred large subscription companies.
The average monthly fee for a canceled subscription is $17.39, and Mackler says that with ScribeUp, users save an average of more than $300 a year in recurring fees they didn’t know they were paying or no longer need.
Will there be an end to the costly economy of forgetting?
Subscription companies are already dealing with significant customer churn. Mastercard reports that the average monthly churn rate (the percentage of subscribers who cancel or do not renew in a given month) is 20%. However, more than half of the U.S. subscription companies surveyed said at least 10% of their subscription base is inactive, meaning those customers are still subscribed but not actively using their services.
As consumers gain more control over their recurring fees, subscription companies may need to compete harder to maintain their rates.
Hitee Chandra Jha, principal product manager at Zendesk, which specializes in product-led growth and customer retention, said companies may need to make the value more visible to customers before they reach the cancellation screen.
For some businesses, that may mean treating cancellations as high-stakes events. Jha said streaming services might be better off offering pauses once customers have finished watching a series rather than desperate discounts. Fitness app users who achieve their goals could be moved to a maintenance tier or offered another avenue to stay engaged, she said.
Data from subscription management company Recurly suggests this kind of flexibility can work. The 2026 Subscription Status report, based on more than 2,200 companies and 76 million unique subscribers, found that usage of the “Pause before Cancel” option spiked 337%, with 3 out of 4 paused customers eventually returning.
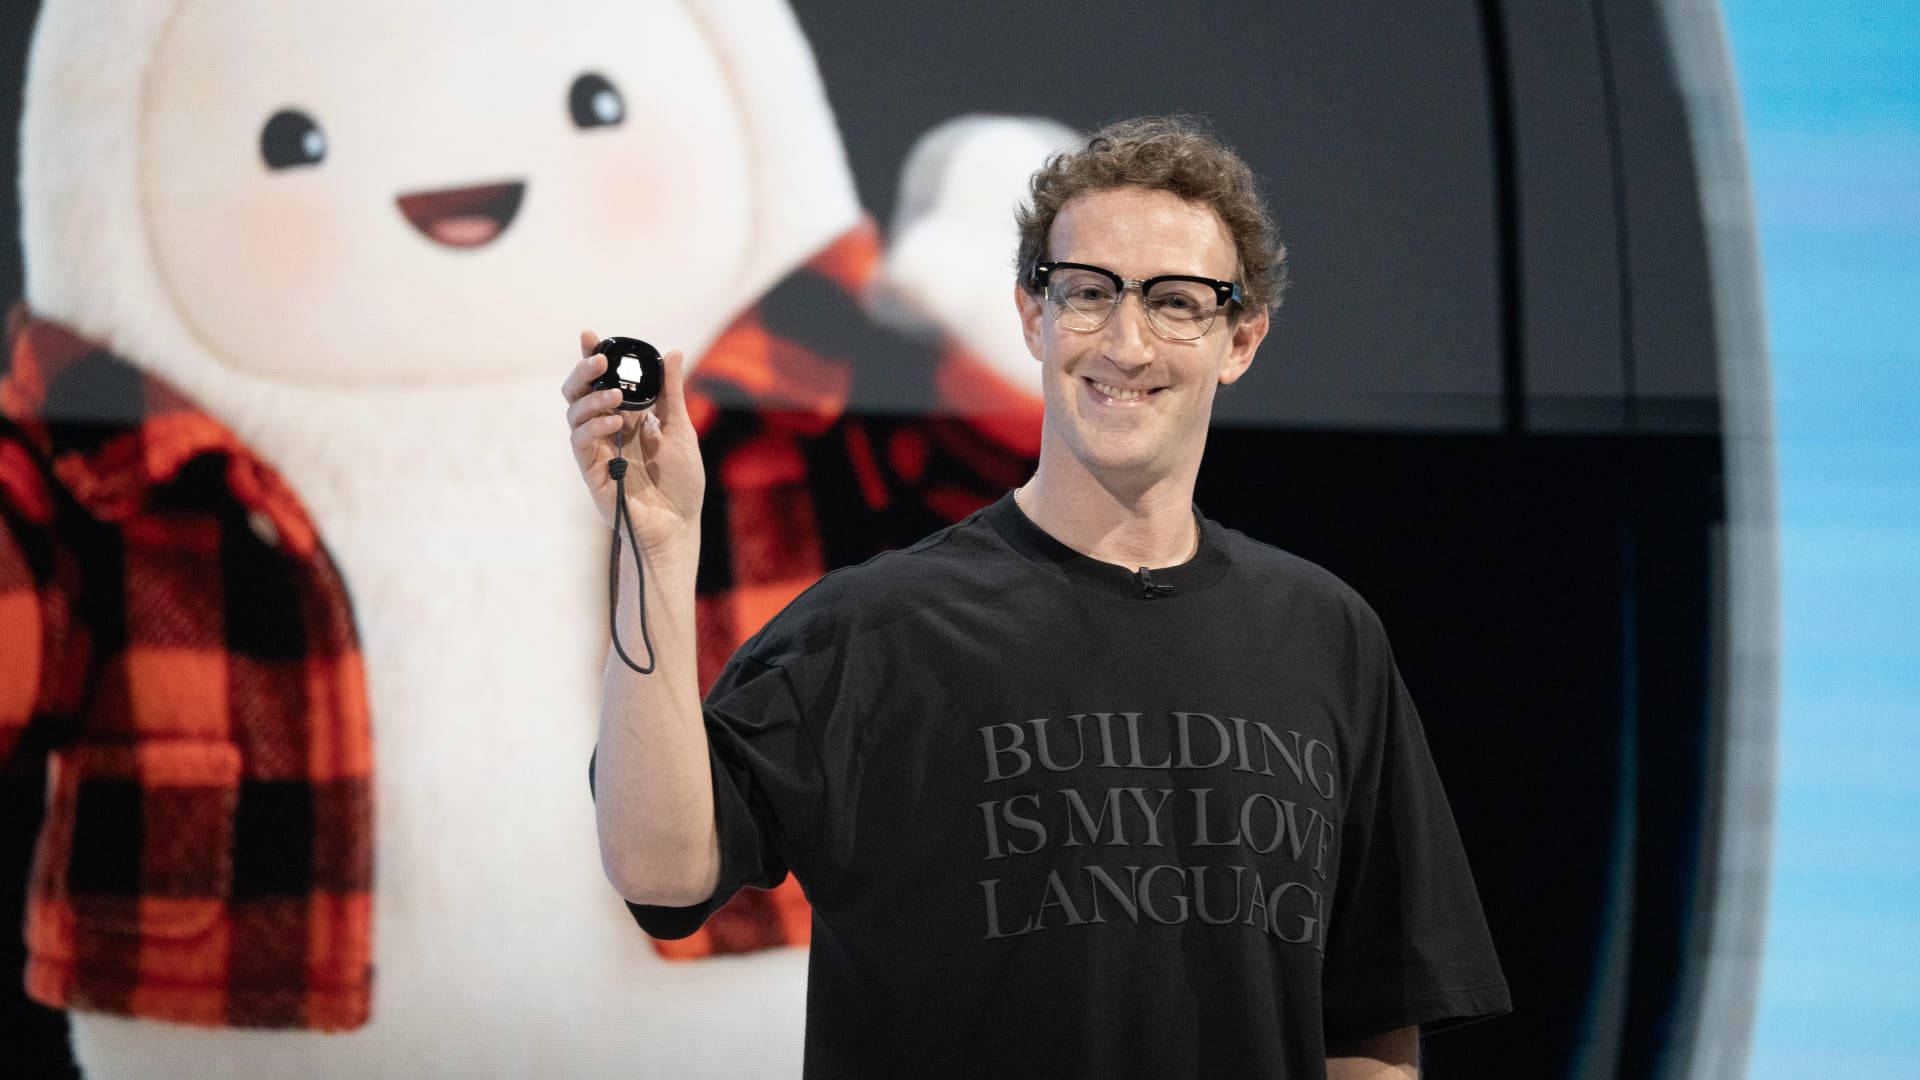
Meta CEO Mark Zuckerberg envisions Muse as the “centerpiece” of an AI strategy surrounded by unproven consumer hardware, from augmented reality glasses to devices like the Muse Charm keychain fob, but the bet is that the market has recently rewarded the company’s efforts.
AI is facing backlash from Amazon, which has blocked Muse from shopping on its site, saying the agent’s access violates its terms of service. There are also major privacy concerns when giving AI access to financial information. However, according to data from Recurly, 43% of consumers said they were satisfied with AI-powered subscription management.
“Treatment of cancellations as a transition rather than just a loss is the difference between a mature retention strategy and a defensive one,” Jha said. “The best defense against AI cancellation is not friction,” she added.
Mastercard’s research points in the same direction. Of the consumers surveyed, 74% said they would be more likely to subscribe if it was easy to cancel, and 70% said they would be more likely to resubscribe. Additionally, 34% said they would continue with their subscription if given the option to pause rather than cancel.
Rather than ending subscription growth, AI may put additional pressure on companies to find new ways to convince customers of value.
ScribeUp found that when users trust that the recurring charges in their account are actually the charges they selected, they feel more comfortable with their subscription overall and their total subscription spend increases.
“When consumers trust that they can easily see, manage and cancel their recurring charges, our data shows they may increase their overall recurring spending and be more willing to try new services in the first place,” Mackler said.
Mahoney said a healthier market would lead to companies offering more ways for consumers to stay on their terms, rather than relying on ways to slow consumer behavior. “When people are locked into subscriptions they don’t want or can’t get out of, market power is limited and companies have no incentive to offer high-quality products at low prices. Companies can only rely on a fixed installed base,” he said.
When people stop paying for things they no longer need, whether it’s AI or consumer behavior, and use that money for other things, “it’s good for consumers, it’s good for the market, it’s good for the companies that make the products that people want,” Mahoney said. “That’s economics working the way it’s supposed to work.”
