
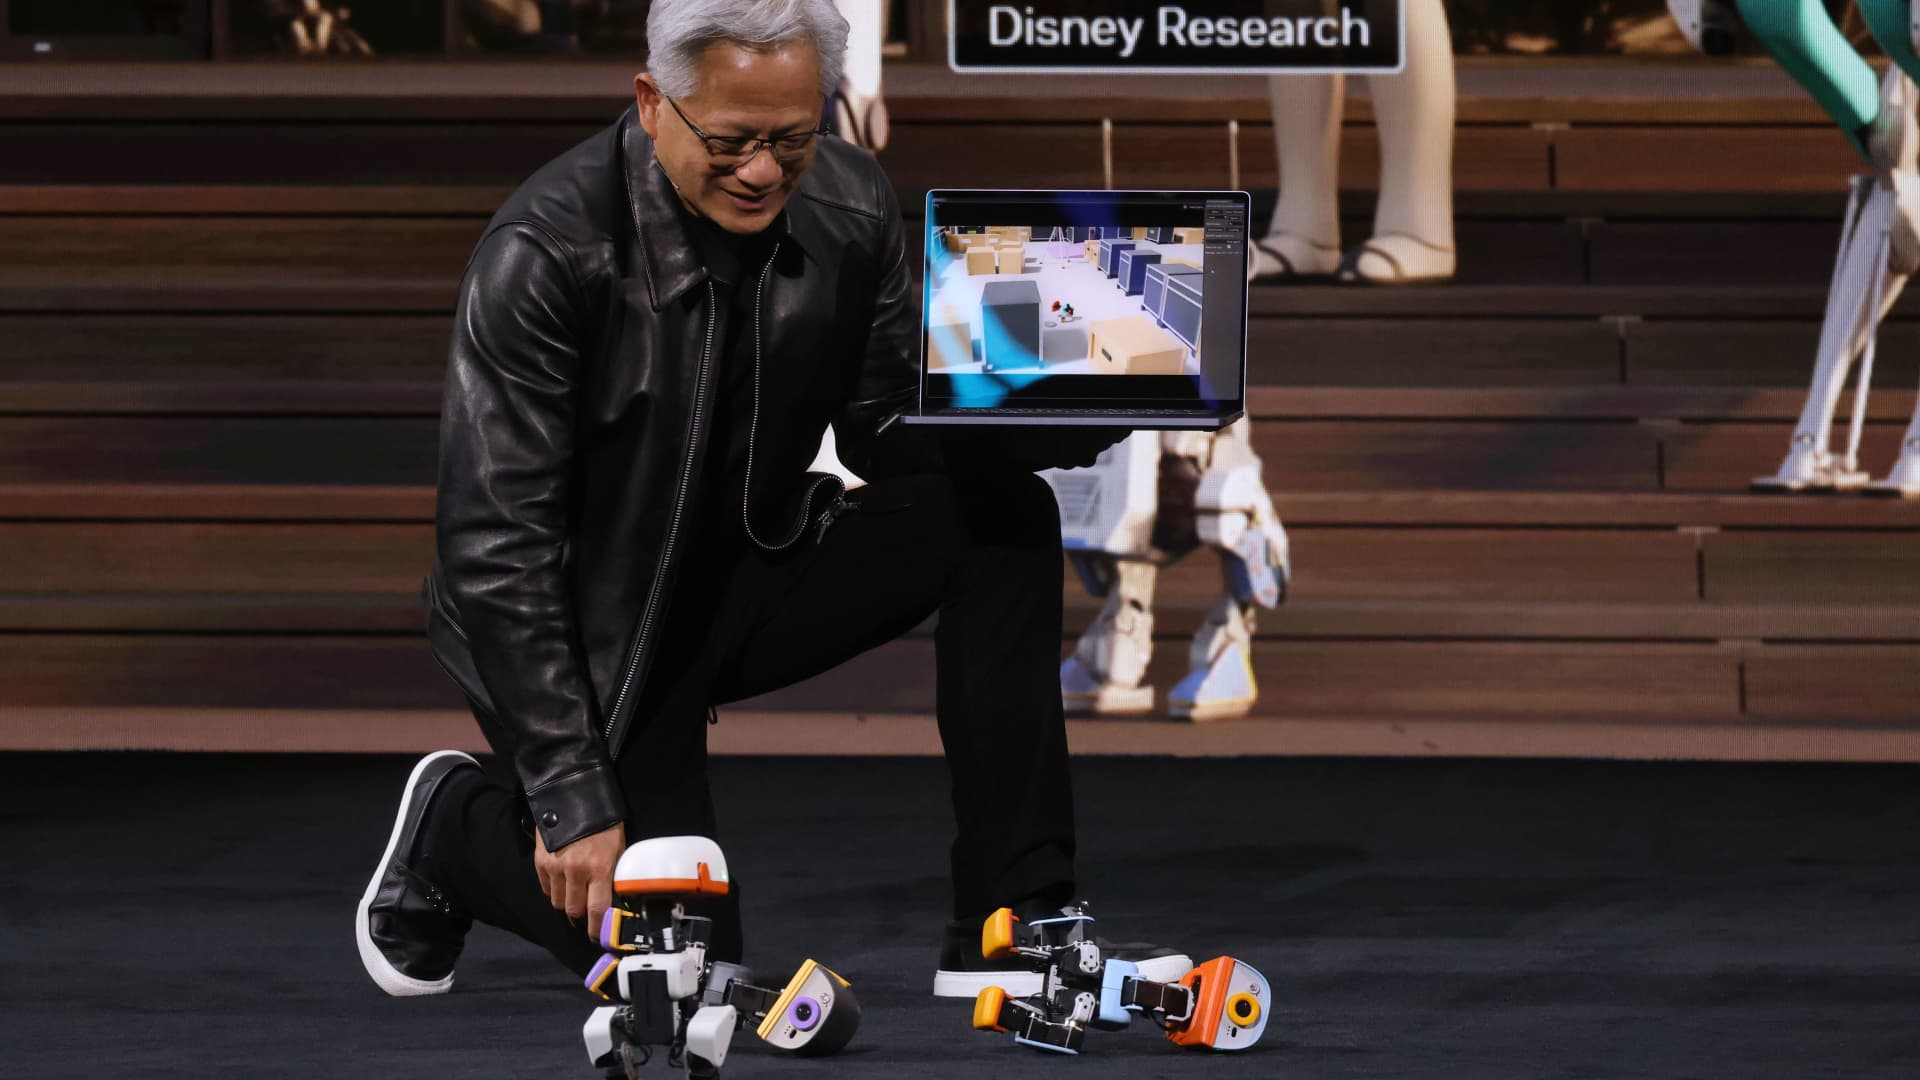
NVIDIA CEO Jensen Huang will deliver a keynote address at the Berlin GPU Technology Conference (GTC) on October 21, 2026 in Berlin, Germany, introducing the new NVIDIA Vera Rubin DSX Pod Full-Stack Modular AI Factory.
Sean Gallup Getty Images
Nvidia’s The company, which has emerged as a global financier of AI buildouts, is facing its first major stress test as credit markets for its major partners tighten.
After developing the chips that underpinned the early stages of the generative artificial intelligence era, Nvidia turned to using its financial muscle to fund AI model developers, data center companies, and a host of so-called neo-clouds. CEO Jensen Huang’s strategy was not only to build cutting-edge technology, but also to help customers invest and obtain financing, making his system reach more people.
This means taking full advantage of Nvidia’s investment-grade credit rating and providing backstop guarantees to OpenAI’s megaprojects, allowing them to finance their construction work at low interest rates.
As of its last quarterly financial report in July, Nvidia had guaranteed up to $105 billion in chips, land and power for a planned 10 gigawatt OpenAI data center in Ohio, as well as $36 billion in off-balance sheet AI cloud contracts, or backstops, for Neocloud. The company has signed on as a tenant for $20 billion in future data center leases, which will later be transferred to a third party.
For most of these transactions, Nvidia does not have to pay unless a participant in the project defaults.
“If the demand for computing doesn’t meet these very high expectations, we’re going to have a problem,” David Trainer, founder and CEO of financial research firm New Constructs, said in an interview.
Nvidia declined to comment for this story.

Market conditions may soon test Nvidia’s mettle. Neocloud share coreweave, Nevius and Airenall cash-burning companies in Nvidia’s portfolio are down at least 30% this month. The group’s largest, Coreweave, has seen spreads on its credit default swaps soar above 11% as investors are forced to pay for default insurance.
Nvidia is helping other neoclouds face challenges.
The company has investments in Australian AI cloud provider Firmus, which abruptly withdrew its IPO plans this month, as well as Britain’s Nscale and SoftBank-backed SB Energy. The companies filed to go public in the U.S. in September, but have not provided updates on their plans for several weeks.
Nvidia ended a third straight week of declines on Wall Street on Friday, with its stock dropping 7.6% in October, its worst pace since November of last year.
Speaking to CNBC this Thursday, Hwang reiterated his confidence in the market, calling the demand for NeoCloud “unexpected.”
“What the middle class lacks is working capital to drive growth,” Huang told CNBC’s Arjun Karpal on the sidelines of the company’s GTC conference in Berlin. “There is so much demand in so many areas of AI that there is a shortage of capital.”
Nvidia has acquired stakes in dozens of companies, including major investments in OpenAI and Anthropic. As of the second quarter, the portfolio was valued at $99 billion.
Building an ecosystem
Investors told CNBC that the big question surrounding Nvidia is how it will use its cash reserves and $5 trillion market capitalization to get more chips into customers’ hands, and how much risk it will take on in the process.
Nvidia graphics processing units are essential for training and deploying AI models. Revenue reached $216 billion in the most recent fiscal year, an almost 8x increase since OpenAI launched ChatGPT in late 2022.
Before the AI boom, Nvidia sold graphics cards that fit into standard server racks or PCs. Its modern systems are much larger and more expensive. Nvidia’s flagship Vera Rubin product is a 7-foot rack with 72 GPUs that weighs as much as a pickup truck. According to some sources, its cost is more than $7 million morgan stanley estimate.
Nvidia still dominates the AI chip market, but competition is coming from: googlerenting tensor processing units (TPUs) within a large cloud service. advanced micro devicelaunched its first AI rack called Helios in July.

Cash is another big advantage for Nvidia. The company generated $70 billion in free cash flow in the first half of the year, compared to AMD’s total of just over $4 billion, and Google’s parent company, Alphabet, went negative in cash flow in the second quarter as it financed a restructuring.
This is a huge advantage for Nvidia as it builds its ecosystem. The company currently offers a full-service platform with software, services, integrated hardware, and financing assistance for many customers.
Nvidia’s most recent August quarterly financial report outlined more than $500 billion in off-balance sheet commitments over the next few years, the majority of which mature by fiscal year 2029. That same month, Huang announced a partnership with six major asset managers in a $500 billion financing aimed at treating computing infrastructure as an asset class.
The deal, in addition to the stake NVIDIA acquired as a limited partner in a private equity fund, committed the financial company to up to $125 billion in GPU financing residual value guarantees. The firm has seeded Brookfield’s first AI Infrastructure Partners fund with $2 billion, which aims to raise $10 billion in total capital, and also seeded KKR’s Helix Digital Infrastructure (an $11 billion vehicle) and Valor Equity Partners’ $5.4 billion dedicated computing fund with an unconfirmed amount.
“We used to make chips that we sold, but these are technology components that people buy and use,” Huang told CNBC when the deal was announced in August. “But now Nvidia’s AI Factory platform is truly an investable asset.”
Huang employs marketing philosophy to enhance the unique value of its equipment.
“We’re the most rentable. We’re fungible and durable,” he said on a podcast with investor Brad Gerstner published last week.
20 Years of Ohio Hardware
While Nvidia waits for Wall Street firms to bring in investors to expand its GPU financing pool, the chipmaker is already aggressively pushing for record-sized deals in the AI infrastructure space.
Nvidia’s single biggest guarantee is for OpenAI’s upcoming facility in Pike County, Ohio, which could be the world’s largest data center. The contract requires Nvidia hardware to be used for at least 20 years.
If OpenAI runs into trouble, the transition from chips to capital carries significant risks.
If OpenAI defaults on payments or faces bankruptcy, Nvidia can either take over the lease, find a new tenant or ask landlord SB Energy to sell the facility, guaranteeing it will pay the difference between the latter two deals by up to $105 billion if the release or sale is less than the reserve price. Nvidia may also pay SB Energy a lump sum. On the other hand, if OpenAI posts its own collateral or achieves a sufficiently high credit rating, Nvidia’s guarantee will end.
Nvidia’s investment in CoreWeave includes equity and a promise to buy the company’s computing for up to $6.3 billion if no other takers are found.
Nvidia’s backstops take many forms, including guaranteeing a minimum resale price for the chip or a minimum hourly take-back price in case the lender has to recover the asset. For Sharon AI and other neoclouds, Nvidia’s deal comes with a revenue-sharing agreement.
“While we believe these AI cloud partners have strong customer demand and strong sales pipelines, they are constrained by the extensive infrastructure required to meet that demand,” Nvidia said in its quarterly report.

This month’s CoreWeave and Nebius
Huang said this week that CoreWeave doesn’t need an Nvidia backstop and neocloud’s cost of capital is falling. CoreWeave’s total debt is approximately $51.6 billion, of which approximately $35 billion is in notes, bonds, and loans. Yields on corporate bonds due in 2031 and 2032 have exceeded 15%.
Brian Statland, portfolio manager at Equity Armor Investments, said the market volatility reflects concerns about business stability.
CoreWeave and other neoclouds “are going to have contracts going forward, and everything looks good and good on the financial statements, but will those contracts be stable?” Statland said. “Won’t it break someday?”
Nvidia says its financial support will help customers build the infrastructure needed to meet strong demand for its chips. Increased computing power could also help AI labs develop new models and services, creating further demand for Nvidia products.
Gene Munster, founder of Deepwater Asset Management, told CNBC last month that “next year we’re looking at $700 billion in revenue.” “This will allow them to provide funding to some of their customers.”
Nvidia’s credit backstop has largely been effective over the past 6-12 months. The company’s last annual report, published in February, made no mention of the AI cloud agreement.
Warren Hosseinion, co-founder of AI infrastructure startup Computing Labs, said Nvidia doesn’t want to be in the shoes of an insurance company, but “we’re going to play that role until the market and the industry catch up.”
“They kind of control how things work,” Hosseinion said. The company is tokenizing GPUs to open up a pool of capital to neo-cloud operators. “They have to be very careful about the pace at which they release their technology, because a lot of that will dictate how the market moves around that technology.”
Not a “perfect panacea”
Nvidia is actively seeking insurance companies to cover some of the risk associated with the potential loss of GPU value.
“Insurers still don’t have a complete panacea for this problem,” said Tom Hord, executive director of product innovation at global insurance group Howden. “But they will probably show up and be helpful in the right situation, and that will open up some business deals.”
The net present value of Nvidia’s off-balance sheet debt in fiscal year 2026 totaled more than $153 billion, an increase of more than $100 billion from last year, according to research by New Constructs.
Such liabilities are increasing across AI transactions, primarily in the form of lease obligations. Rating agencies such as Moody’s are sounding the alarm. According to the agency, guarantees will become the fastest growing type of off-balance sheet financing arrangement in 2026.
Moody’s doesn’t count guarantees as debt when rating corporate buyers, but it’s “something we constantly monitor,” said David Gonzalez, a vice president at Moody’s.
“There is no comprehensive real approach because these are proprietary advanced structures,” he said. Gonzalez said the chips will likely hold “value in excess of their contractual residual value” in the near future, which will reduce risk in many of Nvidia’s financing structures.
Still, how much exposure an investment-grade AI player can handle is “an issue that we’re constantly evaluating every day,” Gonzalez said.
“That’s the center of all our discussions right now,” he said.
—CNBC’s Seema Mody contributed to this report.
Watch: CNBC’s full interview with Nvidia CEO Jensen Huang
