

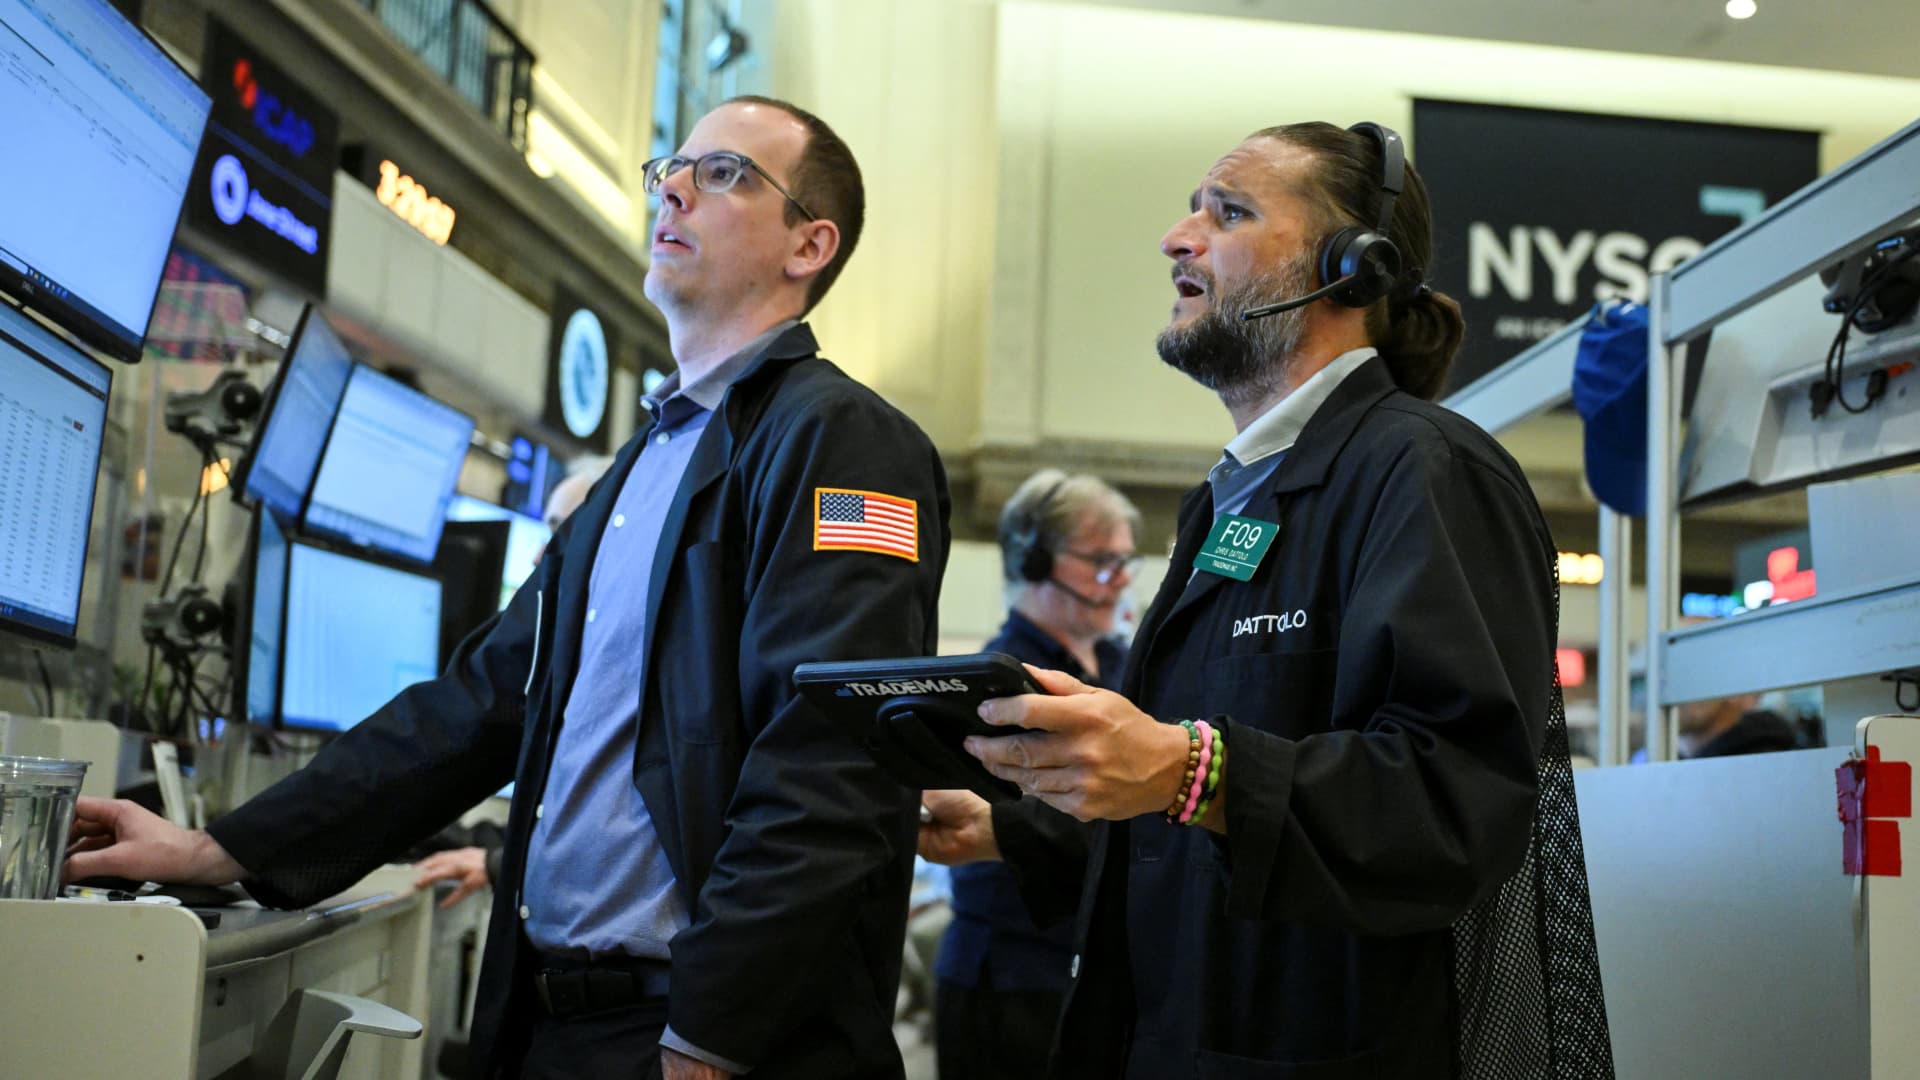
Traders work on the floor of the New York Stock Exchange (NYSE) on July 23, 2026 in New York.
Angela Weiss | AFP | Getty Images
It’s been a volatile year for global markets, rewarding some trades and punishing others.
CNBC asked six investors about the biggest risks they perceive and how they are positioning their portfolios in response. Despite differing views on the biggest threats to the market, investors repeatedly returned to the same response: diversify beyond this year’s biggest winners.
Disappearing American exceptionalism
Chris Rush, investment manager at IBOSS, told CNBC that the biggest risk investors are taking is “focusing too much on past winners and missing out on other opportunities around the world.”
“It’s easy to focus on short-term noise,” he says. “However, we believe concentration is a greater risk as US stocks already make up a large portion of global portfolios. While US exceptionalism is also starting to fade from the levels seen before 2025, the Magnificent Seven’s rising debt levels increase the risk of continuing to chase the same companies.”

Real estate investment trusts, which Rush says have been “unpopular for many years, are becoming increasingly attractive from a valuation perspective” are among the assets the team is leveraging, along with UK equities and listed shares in Asia and emerging markets, to grow their portfolios.
“Investors are understandably focused on AI winners South Korea and Taiwan, but we think China continues to be well-positioned, having performed particularly well during the recent pullback,” he said.
“Don’t die trying to be a hero.”
Ben Kumar, head of wealth, investment and public policy strategy at UK asset management firm 7IM, told CNBC that the big challenge for investors this year is “not managing overall volatility, but managing specific volatility.”
“The winners and losers have been changing over time,” he explained. “Overall, the wins were greater than the losses…but it was very difficult to be too exposed to a particular theme, sector or style.”
Kumar pointed out that energy stocks have had two periods of best and worst performance this year, and the same is true for IT stocks.
“At some points everything went well, and at all times nothing went right,” he said. “Across sectors and regions, diversification has played a huge role. And if, like us, you’re willing to not go all in on the winners (and risk being a loser), you could have had a pretty good year.”
“You don’t have to be a hero in this market, just keep getting wide exposure at your convenience,” he added. “Don’t die trying to be a hero.”
Warning against complacency
Ben Seeger Scott, chief investment officer at London-based Forbis Mathers, told CNBC that “two powerful forces” are pulling markets in opposite directions: the Iran war and strong U.S. corporate earnings, and there is a risk that markets will become complacent with events in the Middle East, inflationary pressures and changes in AI trade.
“We’ve been more sophisticated with our portfolio, reducing some of our overweight in equity risk (while maintaining a slight overweight), moving from a market-cap weighted exposure to an equal weight exposure, and rotating mega-cap technology stocks into regular U.S. stocks,” he said.

Stocks and government bonds have soared this year, benefiting some trades and hurting others.
“Unpleasant trade-off”
Charlie Ambler, co-chief investment officer and partner at Saltus, said the team’s view is that the biggest risk to the portfolio is policy lock-in around interest rates.
“Central banks are struggling to keep long-term interest rates under control just as economies are absorbing massive AI infrastructure developments, which are capital-intensive and bordering on inflationary,” he said. “The problem is that it’s becoming harder to extract the necessary tonic in the form of higher short-term interest rates.”
He said policymakers had to make “uncomfortable trade-offs” between controlling inflation and maintaining financial stability, and that portfolios “need to be positioned with the possibility that they might not be quite right.”
Ambler also said the team’s response to uncertainty is to “broaden the scope.”
“Rather than concentrating risk in areas that have delivered recent returns, we’re increasing our exposure to stocks, bonds and alternative products,” he told CNBC. “Particularly in alternatives, there is a focus on assets whose returns simply do not track the stock or bond markets.”
Steve Bryce, global chief investment officer at Standard Chartered, said the biggest cyclical risk was that something disrupted the global AI boom, and the biggest structural risk was the outlook for fiscal policy and inflation.
Bryce warned against taking a “barbell approach” to the current market, holding too much cash and investing heavily in growth areas.
“The former is very profitable, but the latter is not optimal in our opinion because it is likely to erode purchasing power in this area,” he told CNBC. “We therefore advocate for investors to have a more diversified portfolio by increasing allocations to other equity areas such as developed market financials and euro area industrial stocks, and buffering portfolios with allocations to bonds, gold and other alternative asset classes where possible.”

Why spending on AI could force the next rotation
Billie Leung, investment strategist at Global
“On the serious side, the situation in the Strait of Hormuz remains unresolved… So the geopolitical premium for oil is not going to disappear anytime soon,” he told CNBC. “However, there are more permanent risks to AI capital spending. The scale of financing currently being pumped into building AI infrastructure is in the hundreds of billions of dollars, reigniting serious discussions about circular funding structures and weak free cash flow transformation across parts of the AI ecosystem. Unlike geopolitical shocks, this is a long-tail risk because it does not resolve with a single headline.”
Leung said the positioning data shows that equity investors are not taking a particularly defensive stance despite the resurgence in volatility, and “if anything they appear to be under-hedged.”
“Implied volatility across major indexes and ETFs has fallen toward one-year lows, and skew is near the bottom of the range, indicating broad bullishness rather than fear,” he said. “In terms of sector rotation, the most obvious beneficiaries are data center industries, energy, and travel, with healthcare, consumer staples, and real estate lagging behind.”
According to Leong, it is the durability of AI capital spending, rather than macroeconomic data signals, that is most likely to trigger real redeployment.
“There is a legitimate debate growing about whether the sheer scale of AI-related investment is starting to crowd out other forms of capital investment in the economy, and, separately, whether the financing structures supporting that ramp-up can support long-term free cash flow gaps,” he said. “If that argument goes beyond theory and starts showing up in guidance and funding costs, that’s what will force a rotation and move money away from pure infrastructure and towards names that can be monetized in the near term, rather than a broader sale of AI.”
