
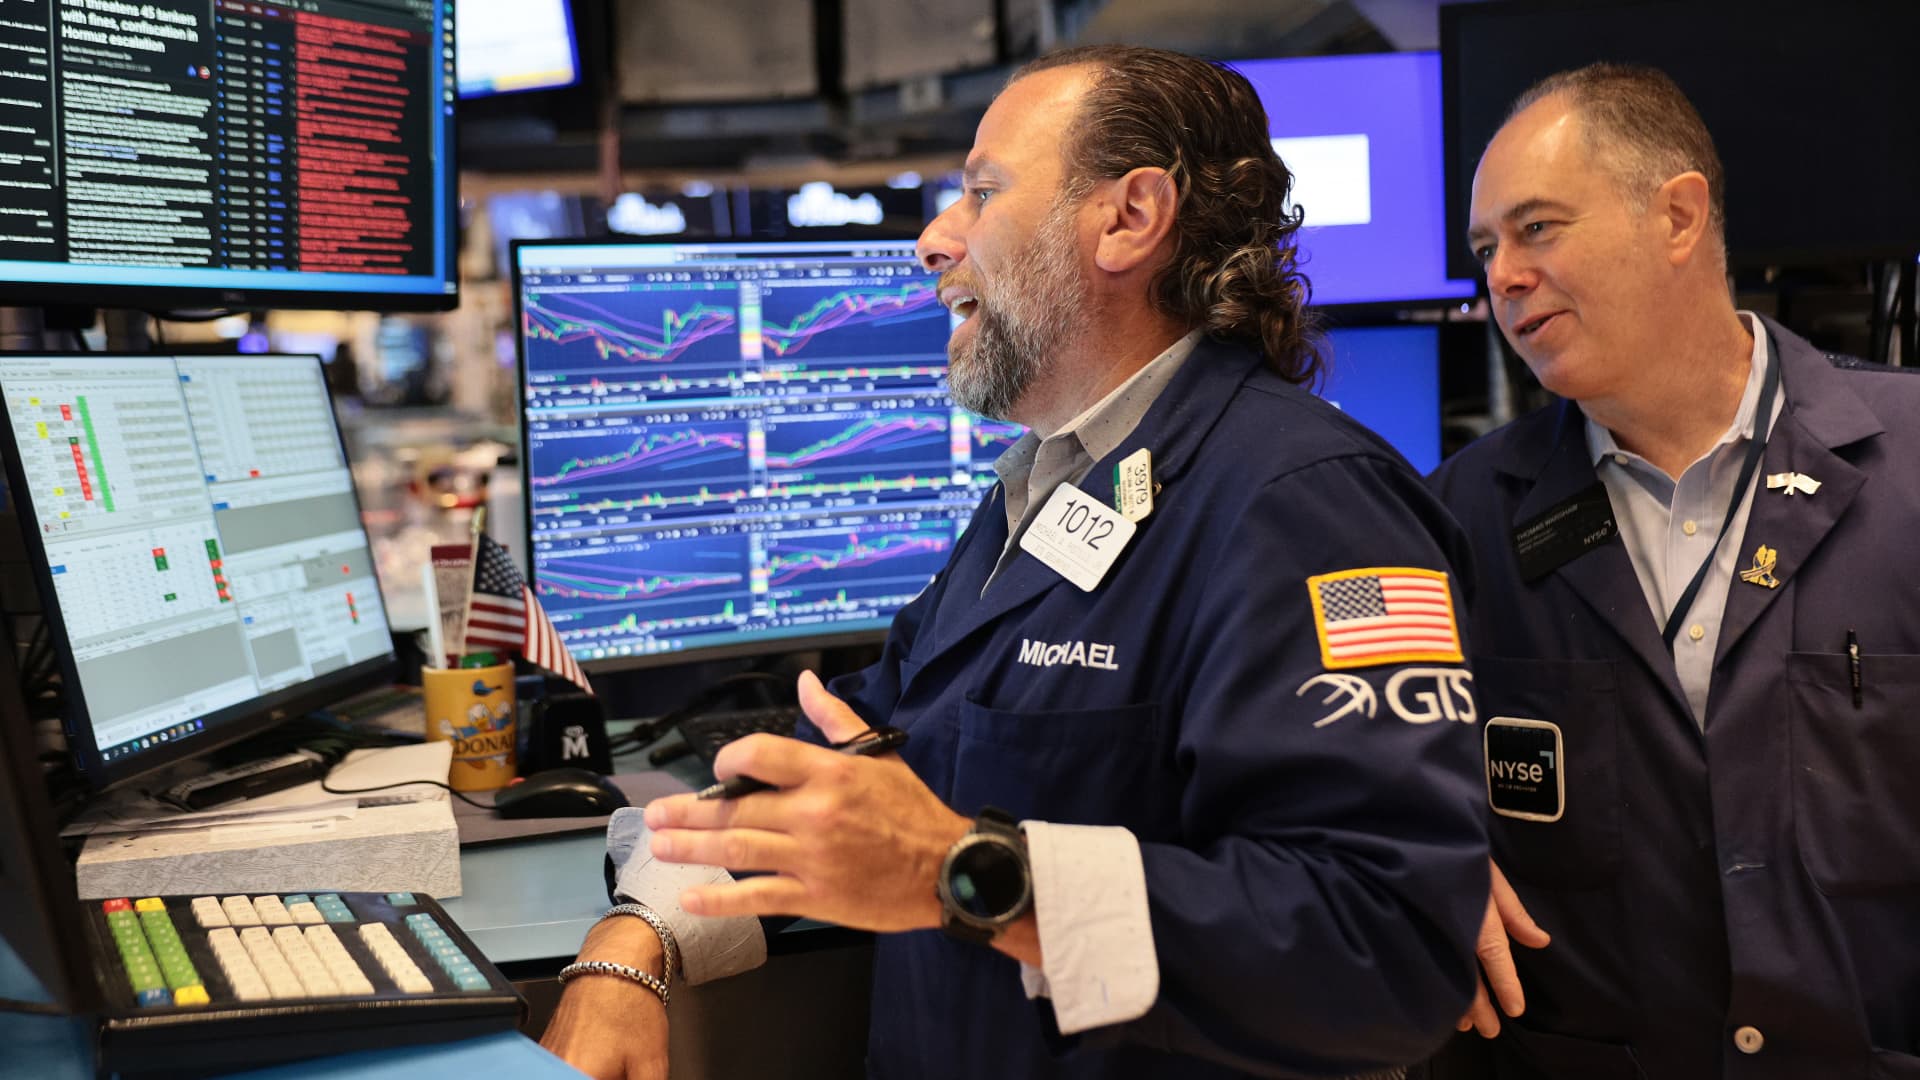

Regarding the two main threats to the current US stock market, traders at Option Pit reveal which boogeyman is scarier and potentially more destructive to AI trading.
Volatility is measured in the following way: CBOE VIX Index Options trading on the gauge soared to more than double its 30-day average volume as semiconductor and data center stocks dragged down the S&P 500 index. Their poor actions have renewed debate among technology leaders and politicians about whether artificial intelligence is ramping up too quickly.
By midday, three of the top five VIX contracts for purchase were calls, and the biggest trade of the day was someone buying at least $3.6 million of 31-strike calls expiring in mid-November.

CBOE Volatility Index Year-to-date
The opposite was true on Friday, with the VIX erasing two days of gains despite inflation statistics that put a 90% chance the Federal Reserve will raise interest rates when it meets this week. As of Friday’s close, S&P 500 options were pricing in a 0.8% swing for the weekly contract expiring Sept. 18, below the 50th percentile of volatility expected in the coming weeks at the FOMC meeting, according to an analysis published by New York-based options manager Carrick Lane.
The VIX hit a year-to-date low of below 14 this month as the probability of a rate hike steadily rises. Carrick Lane principal John Marshall said this, combined with Friday’s post-inflation drop in the VIX, was a sign the market was getting used to higher interest rates.
“Stock market players now think the FOMC has made a decision and they seem to be more focused on AI,” Marshall said on a conference call. “Technology risk and interest rate risk are usually relevant because they are long-term assets, but people are not pricing this in as far into the future, perhaps because the age of AI is now and the time to profit is now.”
It is important to note that fluctuations in interest rates are not absent across the market. The Merrill Lynch Option Volatility Estimate (MOVE) index, which measures the volatility of U.S. Treasuries, added 10 points last week to hit the 92nd percentile high, according to a memo from Mandy Hsu, head of derivatives market intelligence at Cboe.
Similarly, option pricing takes into account the volatility of interest rate sensitive groups. iShares 7-10 Year Treasury Bond ETF (IEF) and Vanguard Real Estate Index Fund ETF (VNQ) According to Marshall’s analysis, they are in the upper 90th percentile and in the 80th percentile.
But volatility pricing in bonds doesn’t seem to be a factor in stocks. The probability of a rate hike at Wednesday’s meeting was more than 91% by midday, thanks to strong stock prices.
