
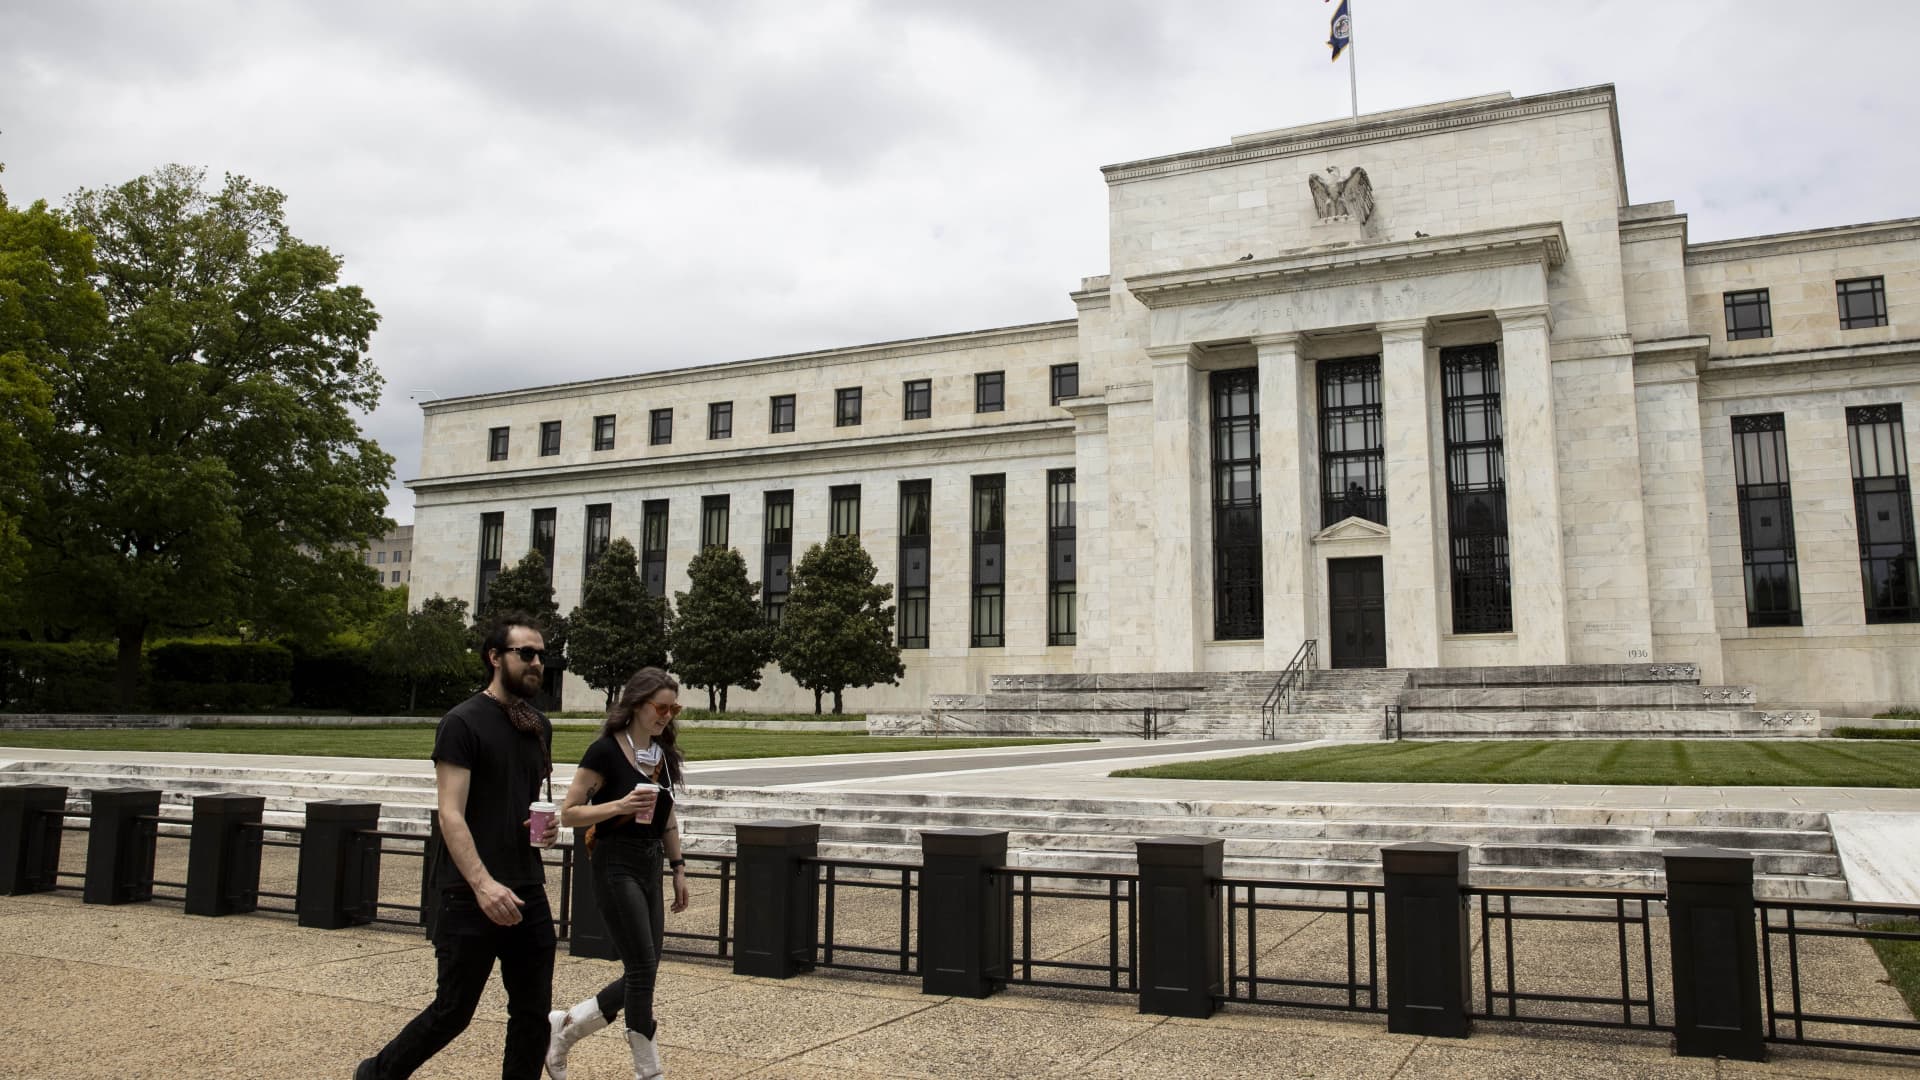

The Fed raised its benchmark interest rate at the end of its September meeting, despite continued pressure from President Donald Trump to lower interest rates after consumer prices rose again in August amid the war with Iran.
In an effort to curb inflation, the central bank’s Federal Open Market Committee, led by Chairman Kevin Warsh, raised the federal funds rate by a quarter of a percentage point to a target range of 3.75% to 4.0%. The move is expected to ripple throughout the economy, impacting everything from credit cards and car loans to savings accounts.
The federal funds rate, set by the U.S. central bank, is the interest rate at which banks lend and borrow from each other overnight. Although consumers do not directly borrow at that rate, Fed policy has a significant impact on consumer borrowing costs and savings yields.
In general, short-term consumer borrowing rates are closely related to the prime rate and are typically 3 percentage points higher than the federal funds rate. Long-term interest rates are driven by inflation expectations and broader economic conditions.
This quarter-point increase, the first since July 2023, corresponds to an increase in the prime rate and will immediately raise the cost of financing many forms of consumer borrowing, exposing some U.S. households to additional financial strain.
“Wealthier and typically older households will weather higher interest rates better because they are less likely to need to borrow, and if they do, it will be on the lower-rate mortgages they secured during the pandemic,” said Mark Zandi, chief economist at Moody’s. “They are also more likely to have savings accounts that earn higher interest rates.”
How the Fed’s interest rate hikes will affect you
President Trump has argued that keeping the federal funds rate too high puts the U.S. at an economic disadvantage, but tight monetary policy is aimed at curbing spending and borrowing, cooling the economy and easing inflationary pressures.
“Raising rates is good news for savers, but bad news for borrowers. It means higher yields on high-yield savings accounts and (certificates of deposit), but it also means higher interest rates on credit cards,” said Matt Schultz, chief consumer finance analyst at LendingTree.
credit card
Most credit cards have variable interest rates, so they are directly tied to the Fed benchmark. When the federal funds rate increases, the prime rate also increases and credit card rates follow within a few billing cycles.
“Cardholders should expect their credit card annual interest rates to increase by a quarter of a percentage point in the coming months as a result of the Fed’s actions,” Schultz said. “For most people, this one rate hike will only add a dollar or two to their monthly bill, but for those already struggling with credit card debt, any increase is certainly not welcome.”
According to a recent analysis by personal finance site WalletHub, the 25 basis point increase will cost credit card users a total of about $2 billion in interest charges over the next 12 months.
mortgage loan
15- and 30-year fixed mortgage rates tend to track the 10-year Treasury yield and broader bond market conditions rather than directly to the federal funds rate, so homeowners are not immediately affected by the Fed’s rate hike.
But given that bond yields are highly sensitive to inflation expectations and face many of the same pressures that prompted the latest rate hike, mortgage rates on new mortgages could also rise, said Michele Ranelli, vice president and head of U.S. research and consulting at TransUnion.
U.S. Treasury yields have been rising sharply on expectations for economic price increases, with the 10-year bond yield briefly exceeding 5% on Tuesday, the highest level in 19 years.
“Looking forward, a borrower with an average new mortgage of $389,367 at an average annual interest rate of 6.78% could see their monthly payments increase by about $65 if mortgage rates rose by a quarter of a percentage point,” he said.
Other mortgages are more directly tied to Fed action. Adjustable rate mortgages (ARMs) and home equity lines of credit (HELOCs) are fixed at the prime rate. Most ARMs adjust once a year, but HELOCs adjust quickly.
car loan
Interest rates on auto loans are fixed once you buy a car, but the Fed’s rate hike could push up interest rates on new loans, further increasing the financial pressures car buyers face.
“The direct financial hit to individual car buyers’ monthly budgets doesn’t seem like much on paper,” said Joseph Yun, consumer insights analyst at Edmunds.
“What’s really troubling is the overall borrowing situation, because this rate hike comes at the same time as auto loan interest rates, which are already near multi-year highs, and new car transaction prices, which are hovering around $50,000 on average,” Yun said.
student loan
Federal student loan interest rates are also fixed for the life of the loan, so most borrowers are not immediately affected by the Fed’s moves. But based on May’s previous 10-year bond auction, which took effect July 1, interest rates are already higher for loans made during the 2026-27 school year.
Private student loans tend to have variable interest rates tied to LIBOR, prime, or Treasury bill rates. In other words, if the Fed rate rises, borrowers will pay more interest. But how much more varies by benchmark.
savings rate
The advantage is that interest rates on savings accounts can increase.
Although the Fed does not directly affect deposit rates, it tends to track movements in the federal funds rate.
“This is a great time to buy online high-yield savings accounts, CDs, and money market accounts,” LendingTree’s Schultz said. “Although returns have not reached the record levels seen a few years ago, they are still strong by historical standards, and rate hikes mean things will get even better in the near future.”
Subscribe to CNBC on YouTube.
