
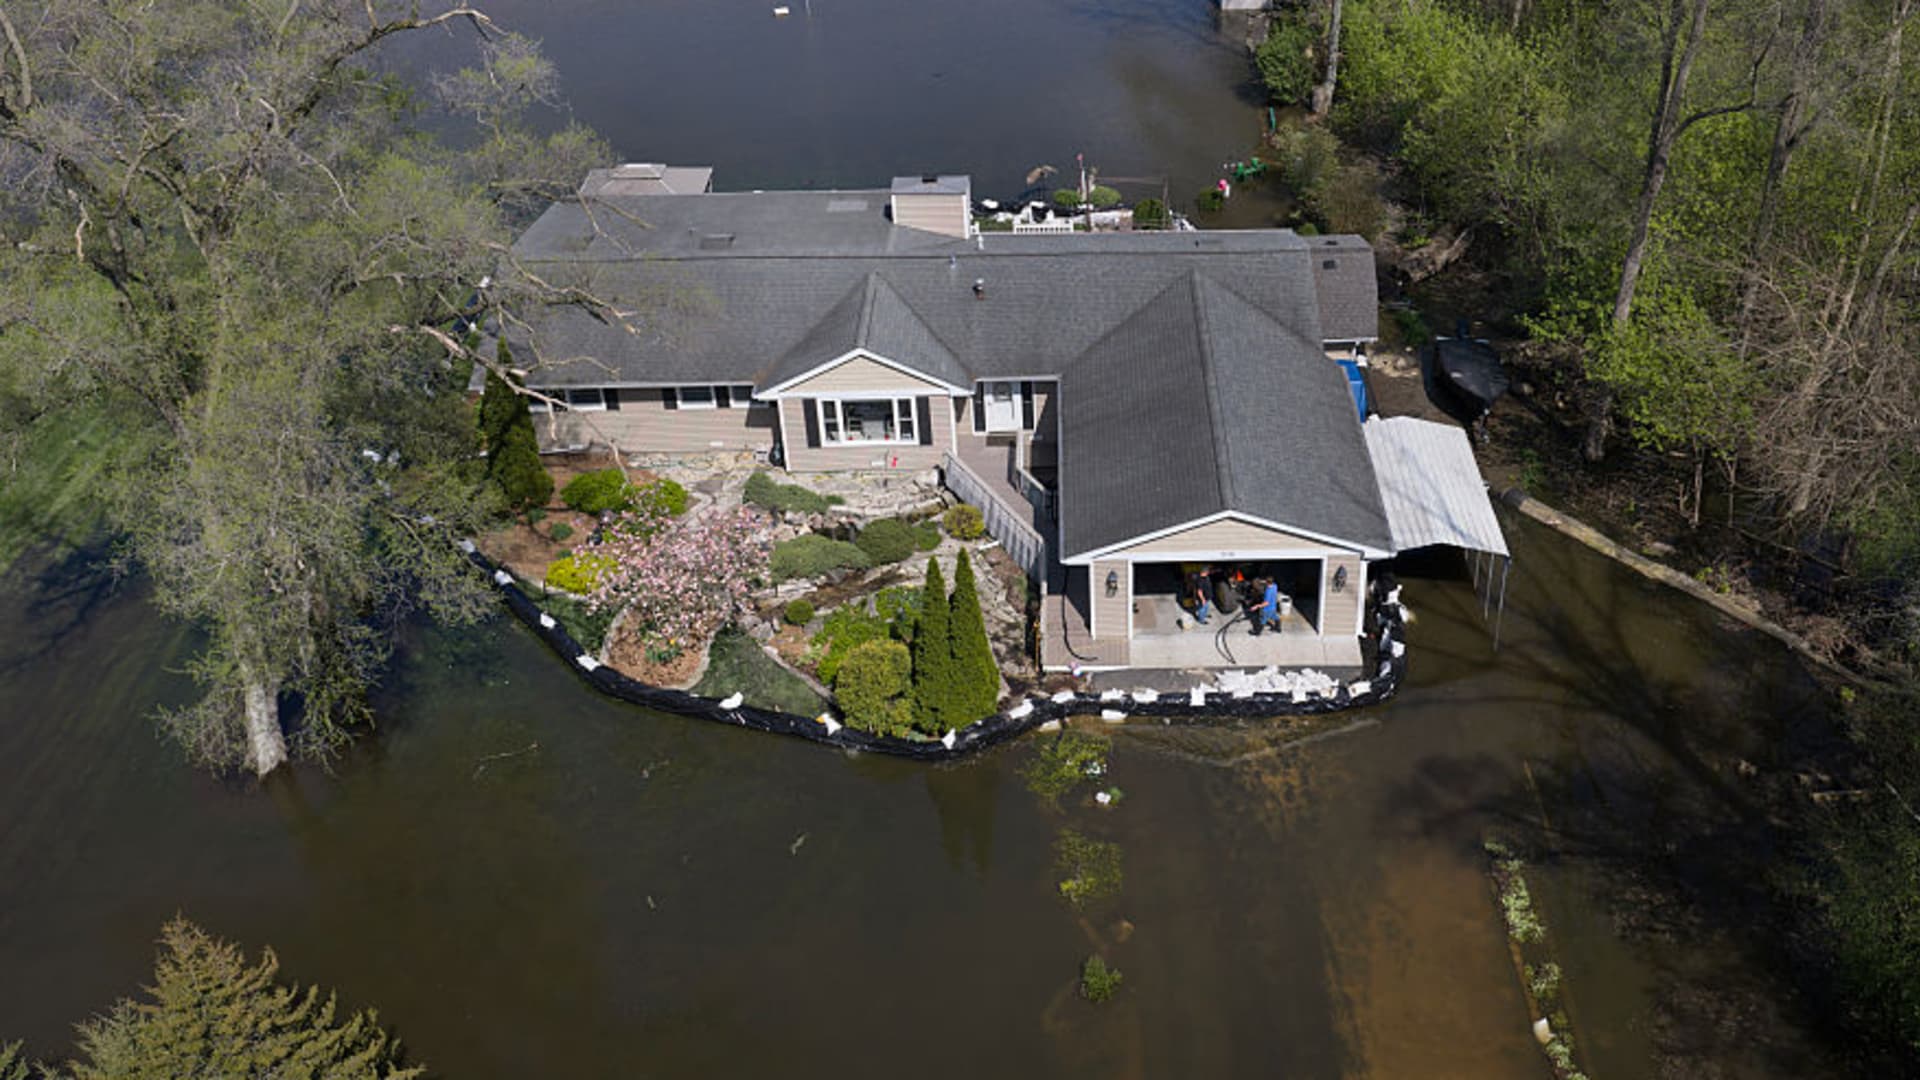
Flooding surrounds homes along the Fox River near Crystal Lake, Illinois, on April 21, 2026.
Scott Olson | Getty Images
Insurance experts say many homeowners probably don’t know that there are huge differences in insurance coverage.
That leaves policyholders exposed to financial losses from increasingly frequent and costly natural disasters such as wildfires, hurricanes and floods, which could put their biggest financial assets at risk, experts say.
In recent years, rising insurance premiums have significantly increased the cost for consumers to maintain insurance.
“The vast majority of homeowners want to fully and adequately insure their homes, are willing to pay the premiums, and believe they have insurance,” Kenneth Klein, a law professor at California Western Law School, wrote in an article in the Lewis & Clark Law Review earlier this year. “But most of them are wrong and severely lacking.”
“Crisis of insurance shortage”
Area burned in the aftermath of the Marshall Wildfire, Louisville, Colorado, January 24, 2022.
Kent Rainey | iStock | Getty Images
About 90% of owner-occupied homes in the United States are insured, Klein writes.
A typical homeowners insurance policy imposes financial limits on coverage in a variety of ways. For example, they exclude certain types of disasters or cap payments for certain items or types of damage.
Klein analyzed California Department of Insurance data from 2018 to 2023 on 74,000 fire-related insurance claims of all sizes, from wildfires to residential fires. Of those claims, more than 70% of insured homeowners were underinsured by an average of about 20%, Klein wrote.
He said the problem is not limited to California.
“This data shows that there is a barely hidden national underinsurance crisis,” Klein wrote. This dynamic, he writes, “permanently and inevitably deprives homeowners of the opportunity to fully recover what they have lost.”
Experts say there are many reasons why homeowners don’t have enough insurance.
“Some consumers may intentionally choose lower coverage amounts just to have some coverage,” Amy Buck, co-founder of the consumer advocacy group United Policyholders, wrote in an email.
But experts say many consumers are unaware of the gap.
On the one hand, confusing insurance policy language prevents a “widespread segment” of Americans from understanding what they’re buying, according to a study published in May in the Virginia Law Review.

Additionally, insurance companies continue to exclude more things from coverage and cap the amount of money covered, Bach wrote.
Experts say consumers generally underestimate the cost of rebuilding a home.
Unfortunately, “coverage gaps are often discovered at the point of loss, when you don’t want to be discovered,” said Larisa Klingler, director of national claims for insurance brokerage Lockton’s Private Risk Solutions Group.
According to experts, the biggest insurance gaps for consumers are:
1. Flood
On December 16, 2025, a temporary sea wall along the White River in Pacific, Washington, was breached and flooded an area.
david rider reuter
Insurance experts say a typical homeowner’s insurance policy excludes or limits coverage for damage from certain disasters, such as earthquakes, landslides and floods.
But insurance experts say consumers often stumble on the latter, which can be costly.
Homeowners require separate insurance to cover physical damage caused by flooding, defined as water that enters a home through the ground. This can occur due to storm surges, heavy rains, and flooding of bodies of water such as lakes and rivers.
According to the Insurance Information Institute, flooding is the most common and costly natural disaster in the United States.
According to the Federal Emergency Management Agency, just one inch of water can cause about $25,000 in damage to a homeowner’s property. According to FEMA, from 2020 to 2024, the average payout for all flood insurance claims was $82,614.
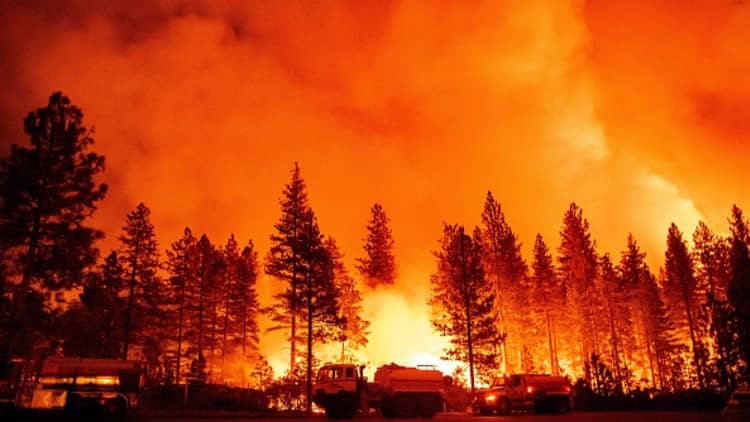
And flood insurance isn’t just for people who live near water. According to FEMA’s Floodsmart.gov, approximately 99% of U.S. counties have experienced flooding in the past 20 years.
But less than 4% of U.S. households purchased insurance from the National Flood Insurance Program, according to the agency’s 2025 blog post.
NFIP is the primary source of flood insurance coverage for residential properties.
Standard homeowners insurance covers certain types of water damage. For example, experts said, in the case of “wind-driven rain,” essentially water enters the house from the top down.
Experts say this can happen when a hurricane damages a roof and allows rain to seep in, flooding the entire house or multiple rooms.
However, insurance companies may exclude benefits or cap benefits for mold damage, Bach said. Additionally, the cap on water damage payments could likely be $5,000, $10,000 or $15,000 per loss, she said.
California Insurance Commissioner Ricardo Lara this week urged consumers to review their coverage and consider flood insurance ahead of what is likely to be a historic El Niño event. Lara said don’t wait until disaster approaches. Flood insurance typically takes effect 30 days after purchase.
Even if you have flood insurance, there are things to be aware of. For example, traditional policies typically limit basement coverage.
2. Reconstruction costs
A new home is being built on the site where a home was destroyed in the Eaton Fire on September 17, 2026 in Altadena, California.
Tama Mario | Getty Images
Underestimating restructuring costs is also a major cause of underinsurance, said Peter Kochenburger, visiting law professor at the Southern University Law Center and managing fellow at the Insurance Law and Policy Institute.
“Construction and repair costs have increased significantly,” Kochenburger said. “If you lose your home and your homeowner’s insurance limits aren’t enough to rebuild it, you’re stuck unless you have your own financial assets, which many people don’t have.”
A Treasury report released last year found that the replacement cost of liability-related losses increased by an average of 45% between 2020 and 2023. Homeowners insurance is a type of property insurance, just like renters insurance and auto insurance.
The majority of homeowners want to fully and adequately insure their homes, are willing to pay the premiums, and believe they are insured. But most of them are wrong and severely lacking.
Kenneth Klein
Professor of Law, California Western Law School
Personnel costs also increased. The cost of hiring workers to build single-family homes jumped 37% between 2018 and 2022 and 45% between 2014 and 2023, according to the report.
Lockton’s Klingler said consumers can consider purchasing “extended replacement cost” coverage to add to their traditional insurance policy.
This typically amounts to an additional 10 to 50 percent on top of a consumer’s home coverage limit, which is the maximum amount the insurance will pay to rebuild a home from the ground up, according to insurance comparison site Policy Genius.
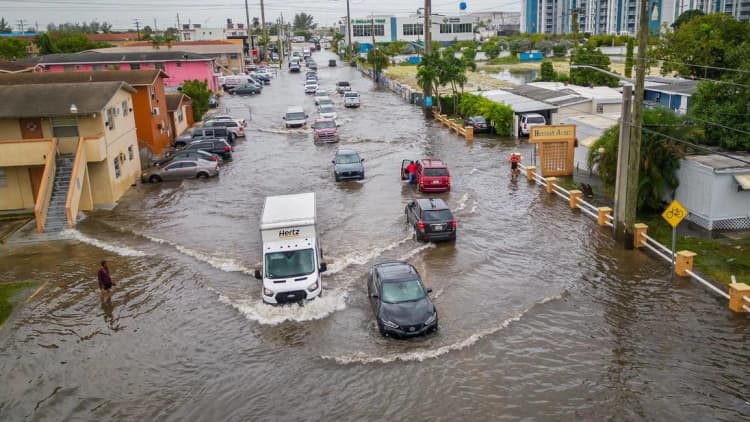
Klingler said consumers, especially those who live in older homes, may also consider purchasing what’s called “ordinance or statutory coverage.”
This protects you from the higher costs of rebuilding your home due to the need to make your home comply with current building codes, such as upgrading wiring, plumbing, and insulation.
3. Restrictions on certain items
Peter Daisley | Photodisc | Getty Images
Experts say insurers generally limit the amount they will pay for certain content in many categories, including art, collectibles, rugs, furs and other high-value items.
However, consumers can purchase add-ons to traditional policies to increase dollar limits on individual items.
“People who have special items like antiques, guns, electronics, jewelry, etc. should find out how they will be covered and whether they need additional coverage for those items,” said Brenda Coode, professor emeritus of financial planning, housing and consumer economics at the University of Georgia and consumer representative for the National Association of Insurance Commissioners.
