
China’s producer price index rose 5% in September, the fastest pace in more than four years, as soaring fuel prices pushed up costs for businesses.
The growth rate was higher than the 4.5% expected by economists polled by Reuters and was a sharp increase from 3.8% in the previous month.
China’s National Bureau of Statistics said the country’s coal sector also saw price increases due to increased demand for coal for winter heating, temporary supply tightness in major coal-producing regions, and an expected rise in international coal prices.
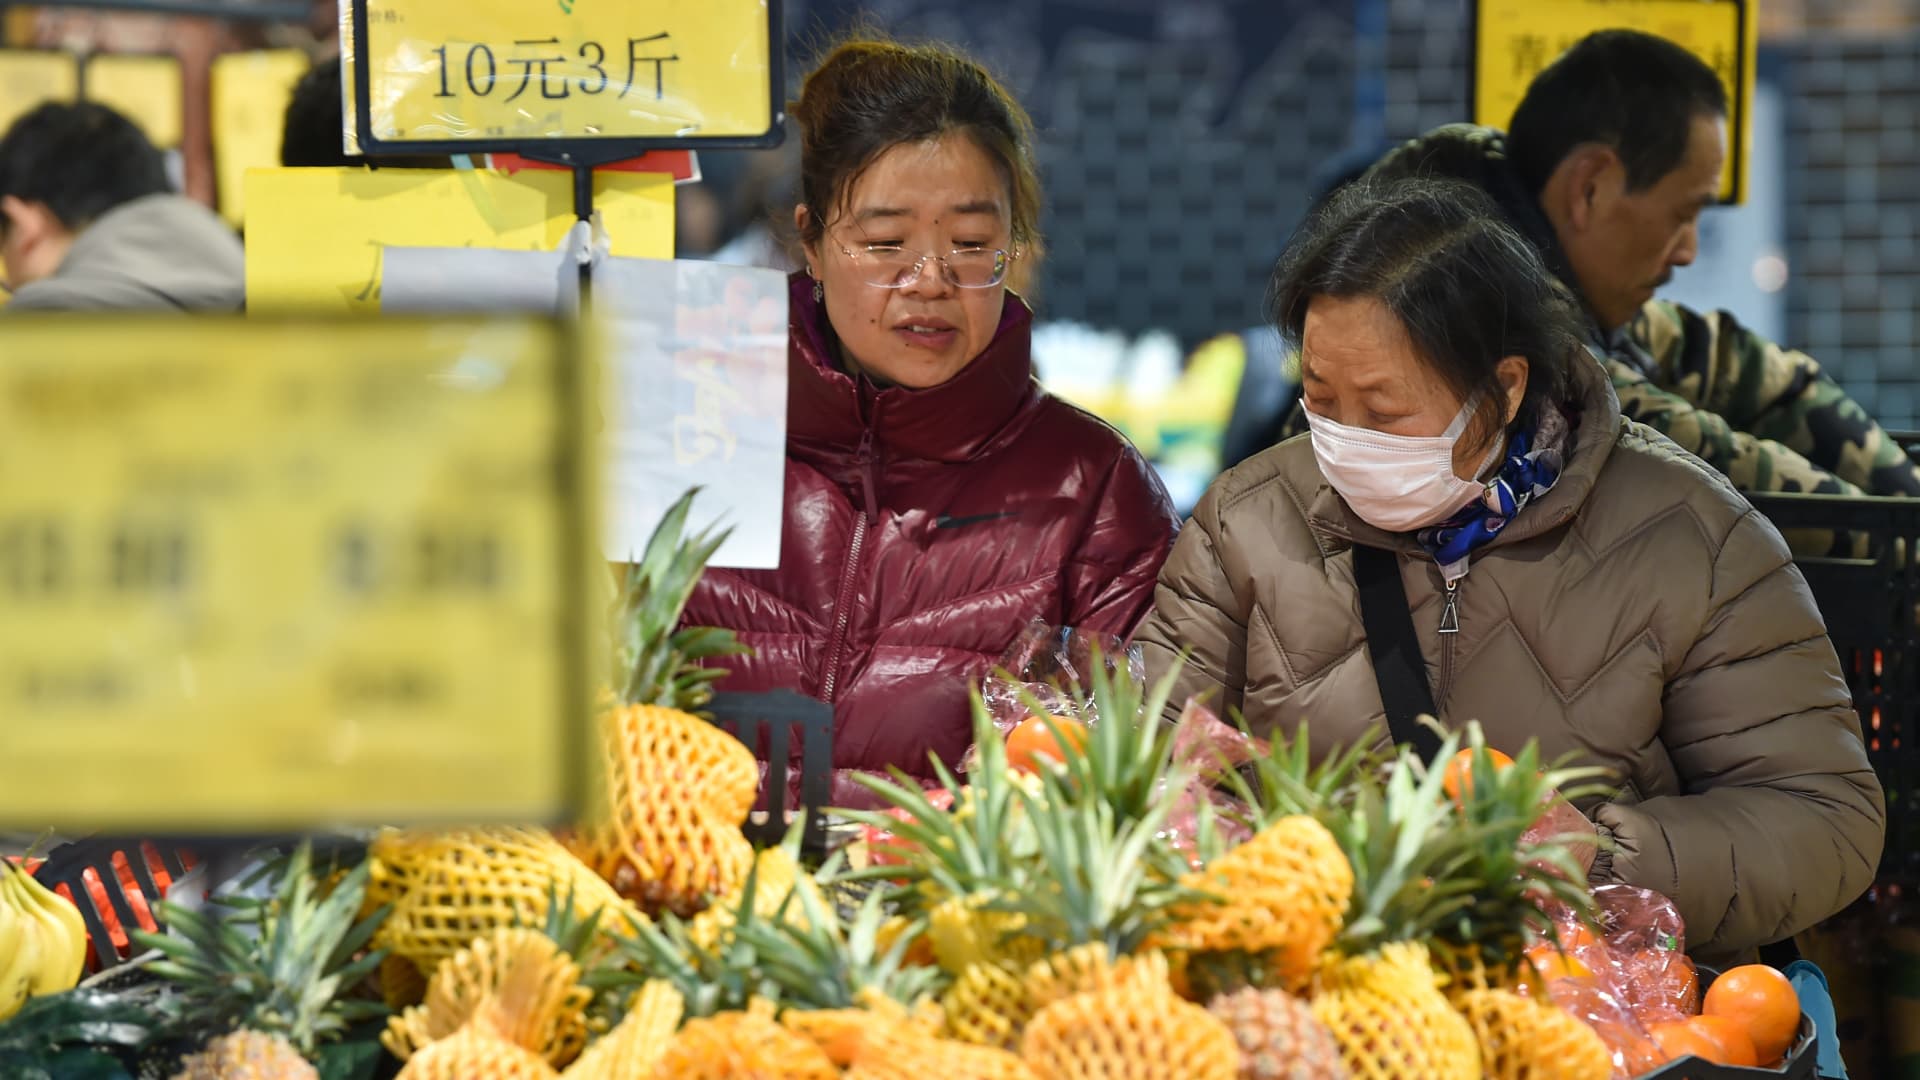
Consumer prices rose 0.9%, slightly short of the 1% expected, but up from 0.8% the previous month.
According to NBS Urban Bureau chief statistician Don Lijuan, the rise in consumer inflation was due to a 16.6% increase in gasoline prices, which contributed about 0.47 percentage points to the year-on-year CPI increase.
This was partially offset by a significant decline in food prices, which fell by 1.7% and pushed CPI down by 0.29 percentage points, Dong added.
Core CPI, which excludes volatile food and energy prices, rose 1%.
Zhiwei Zhang, president and chief economist at Pinpoint Asset Management, said in a note after the data release that the weaker-than-expected CPI readings indicate domestic demand remains “lackluster.”
However, Hao Zhou, chief economist at Guotai Junnan International Holdings, said the rise in PPI showed the economy was gradually emerging from deflationary pressures, even if the recovery remained uneven.
He said domestic demand is recovering more slowly than the industrial sector, although the fact that consumer inflation remains in positive territory as demonstrated in the deflationary environment in 2024 and 2025 “continues to disappear.”
The rise in inflation comes as China’s economy struggles with its slowest growth rate in more than three years. The GDP growth rate in the second quarter of this year fell short of the expected 4.3%.
Economic data for August showed slower-than-expected growth in retail sales, but higher-than-expected industrial production.
On September 28, a State Council readout stated that “efforts should be made to respond to new challenges in economic management and strengthen the countercyclical adjustment of macro policies,” suggesting that further policy support may be provided to the Chinese economy.
“This signals a slight shift in tone,” said Lin Song, chief economist for Greater China at ING, adding that further policy support would be deployed to meet short- and long-term growth targets.
“These include a 4.5% to 5.0% GDP growth target for 2026 and the long-standing goal of doubling GDP from 2020 to 2035.”
