

Social unrest, political unrest and rising debt weighed on French assets on Monday, weighing on government bonds and Paris-listed stocks.
of EUR The dollar was last down 0.28% against the US dollar and 0.24% against the British pound.
of France 10 years Despite recent easing, bond yields rose more than 10 basis points and remained near their highest levels in decades. Rising yields mean higher borrowing costs for governments in the bond market. country 2 years and 30 years Yields rose by 6 basis points and 8 basis points, respectively.
Stock prices are also feeling the heat, CAC40 In Monday morning trading, the index was down 1.34%. Banks have been under particular pressure due to rising political instability, and the market has lagged far behind its European peers in recent years, even though only about 15% of its revenue is generated domestically.
The French stock market has historically been sensitive to widenings in the additional bond yields France pays to Germany, the so-called OAT-Bund spread, which has reached its highest level since the European debt crisis of the early 2010s. French yields also exceeded those of Italy and Greece, suggesting risks are rising.
Widening bond spreads are raising concerns about companies’ cost of raising capital, raising concerns about higher taxes and tighter regulations. The French stock market is also struggling because it is dominated by luxury goods companies and is suffering from weak consumer spending of luxury goods in China.
“Bond market riot or popular uprising?”
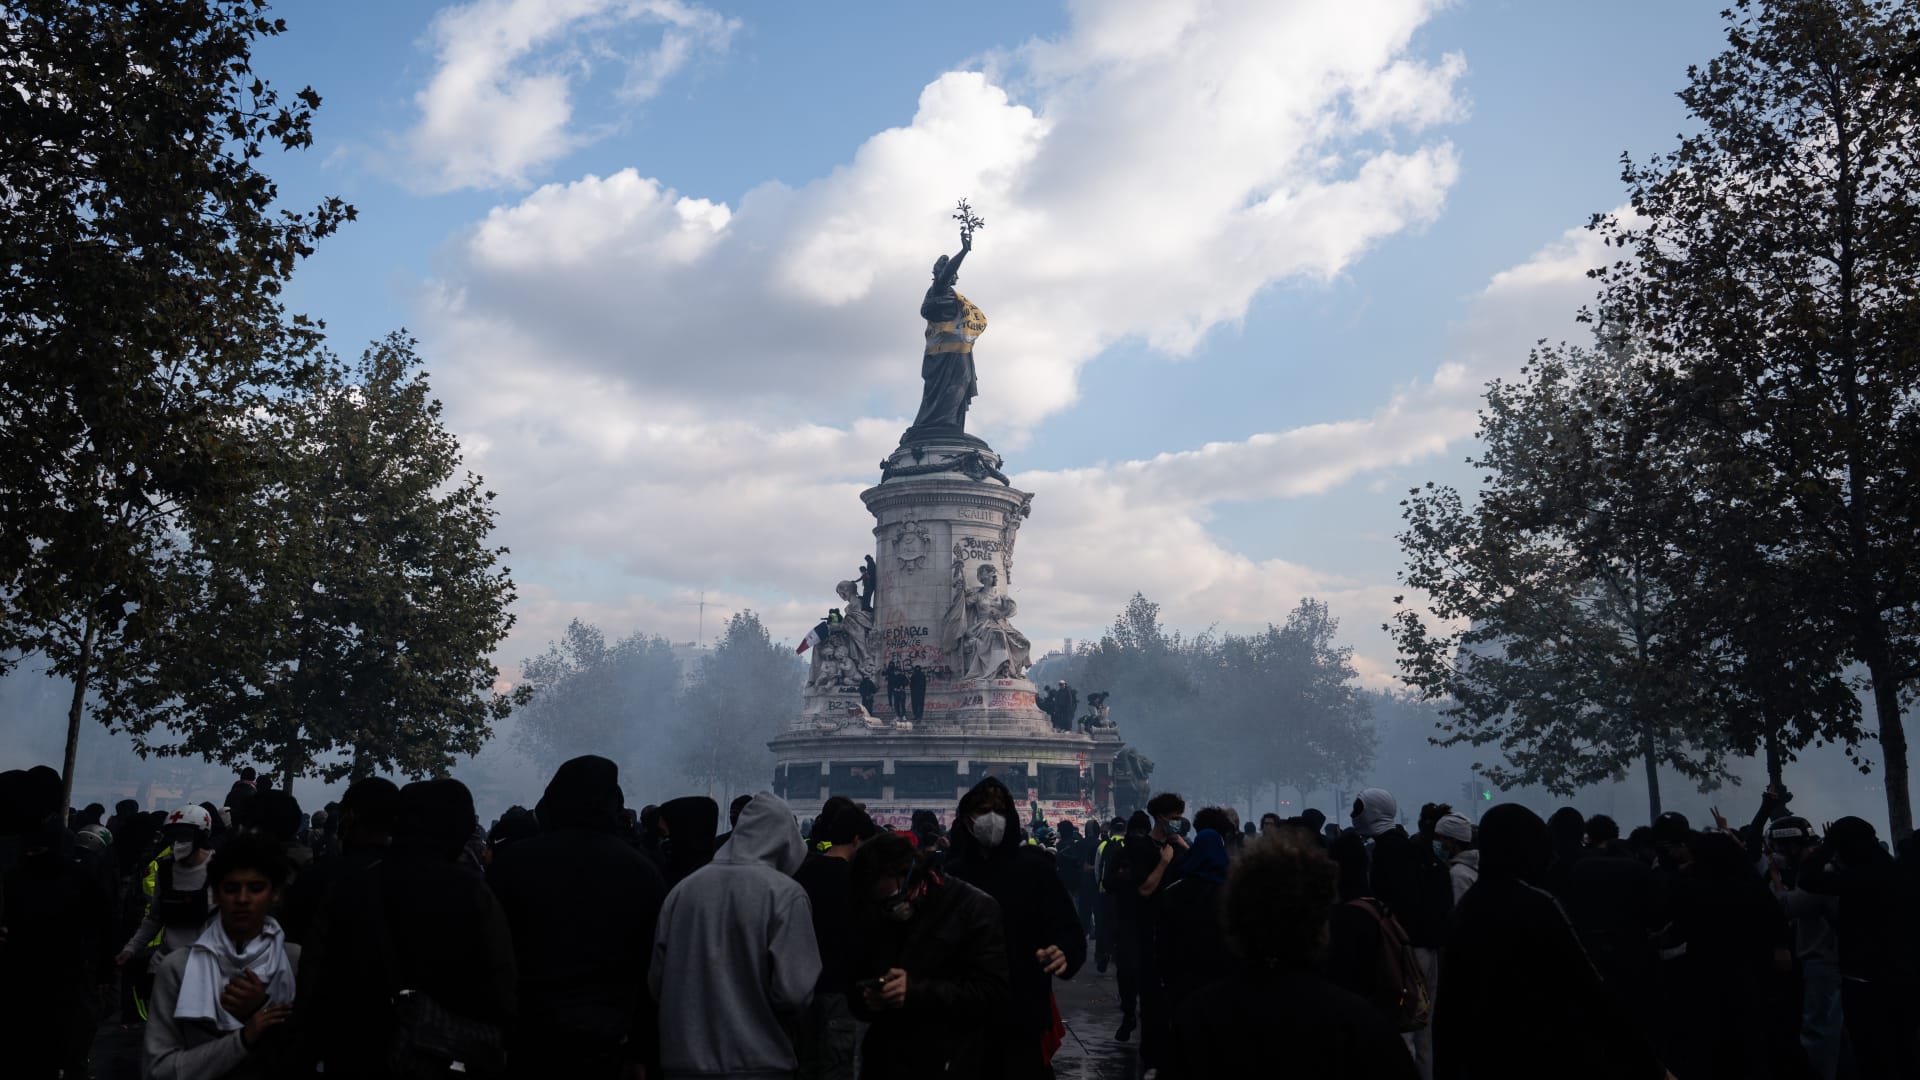
Hundreds of thousands of people marched over the weekend to protest political paralysis, the cost of living, and the state of public services such as schools and health care.
Mass rallies in cities from Paris to Lyon to Marseille turned into dramatic scenes, with buildings and cars set on fire, clashes with police and more than 2,000 people arrested.

“That’s not helpful for international investors who are thinking about whether they want to invest in French government bonds,” Mike Bell, head of market strategy at RBC BlueBay Asset Management, told CNBC’s “Squawk Box Europe” on Monday.
“It looks like a bond market riot or a popular uprising or both,” Bell said.
The share of foreign investors in French government bonds is increasing, rising from around 48% in early 2022 to nearly 60% in early 2026, which could mean more volatility in bond markets in a risk-off environment.

“What we need in France is to get our finances in order, and we need to raise the retirement age – the average person lives to 84 and you can’t retire at 62 – but before we get into that, if this is what’s going on, imagine what would happen on the streets of France if we tried to raise the retirement age to 68…I mean, here in the UK it’s 68,” Bell added.
“It doesn’t seem like this country has much ability to govern when it has to make difficult choices.”
budget challenges
France’s benchmark borrowing costs are nearing their highest levels since 2002, with investors demanding higher premiums to fund the country’s spending.
Key concerns include the uncertainty of next year’s presidential election, with far-right Marine Le Pen leading in many opinion polls, and whether Prime Minister Sébastien Lecorne’s minority government will be able to pass the 2027 budget currently under negotiation.
Budget negotiations are becoming increasingly difficult in France, which ousted two of Lecornu’s recent predecessors.
Analysts say financial institutions want a credible fiscal consolidation plan to prevent France from falling into a debt spiral. Slower economic growth and a persistently high budget deficit as a percentage of GDP are pushing up bond yields, increasing government debt servicing costs and potentially widening the deficit further, potentially pushing borrowing costs further higher.

“It’s going to be difficult to see the deficit come down without painful policies,” Sharon Bell, senior European equity strategist at Goldman Sachs, told CNBC’s “Squawk Box Europe” on Monday.
“There is a good chance that taxes will go up for companies in France. I think taxes in general could go up in France. Fiscal consolidation means you have to either reduce spending or increase taxes. These things are very difficult.”
“Ms. Le Pen, who is currently leading the polls, has talked about adhering to the golden budget (rule) during her term, but she has not given details on how this will be achieved,” Bell continued.

“One of the reasons the OAT-Bund spread is not coming in is because investors are skeptical about fiscal consolidation and reducing the budget deficit.”
But Ken Egan, senior director of sovereign debt at ratings agency KBRA, said last week’s auctions showed that “the underlying demand for French government bonds remains very strong.”
“The morning is generally more risk-off, but France is clearly under a little more pressure. The question the market will be asking is how easily France can actually move forward from here,” Egan said in an email.

A looming debt crisis?
Goldman Sachs’ Sharon Bell does not believe the current situation warrants emergency intervention by the European Central Bank, adding that the bank is “unwilling” to use tools such as communications safeguards.
However, he said the ECB would choose to use this mechanism if spreads began to disrupt market liquidity.
Such a move would be politically sensitive, he added, and France would likely need to undergo tougher fiscal reforms over a longer period of time, similar to what countries such as Greece, Portugal and Ireland did during the eurozone crisis.
“Sometimes you need market pressure, and that’s what we’ve seen this year.”
Meanwhile, Mike Bell of RBC BlueBay Asset Management said France faced a “very real risk” of a sovereign debt crisis.
“Ultimately we need to have a fiscal authority in place. If we proposed what we actually need to do for that, we’re not going to get elected, and if we try to introduce it without doing our electoral mandate, there’s going to be riots in the streets.”
Mr Bell added that there would be an “almighty clash with the ECB, whoever wins the next election” before any intervention takes place. Central banks are unlikely to intervene unless countries follow an excess deficit procedure that states that general government budget deficits cannot exceed 3% of GDP. France’s current budget deficit is approximately 5%.
Bank of France Governor Emmanuel Moulin told CNBC last week that while he attributed the rise in French bond yields to political uncertainty, “it is possible to return to the government’s 3% budget deficit in 2029.”
