
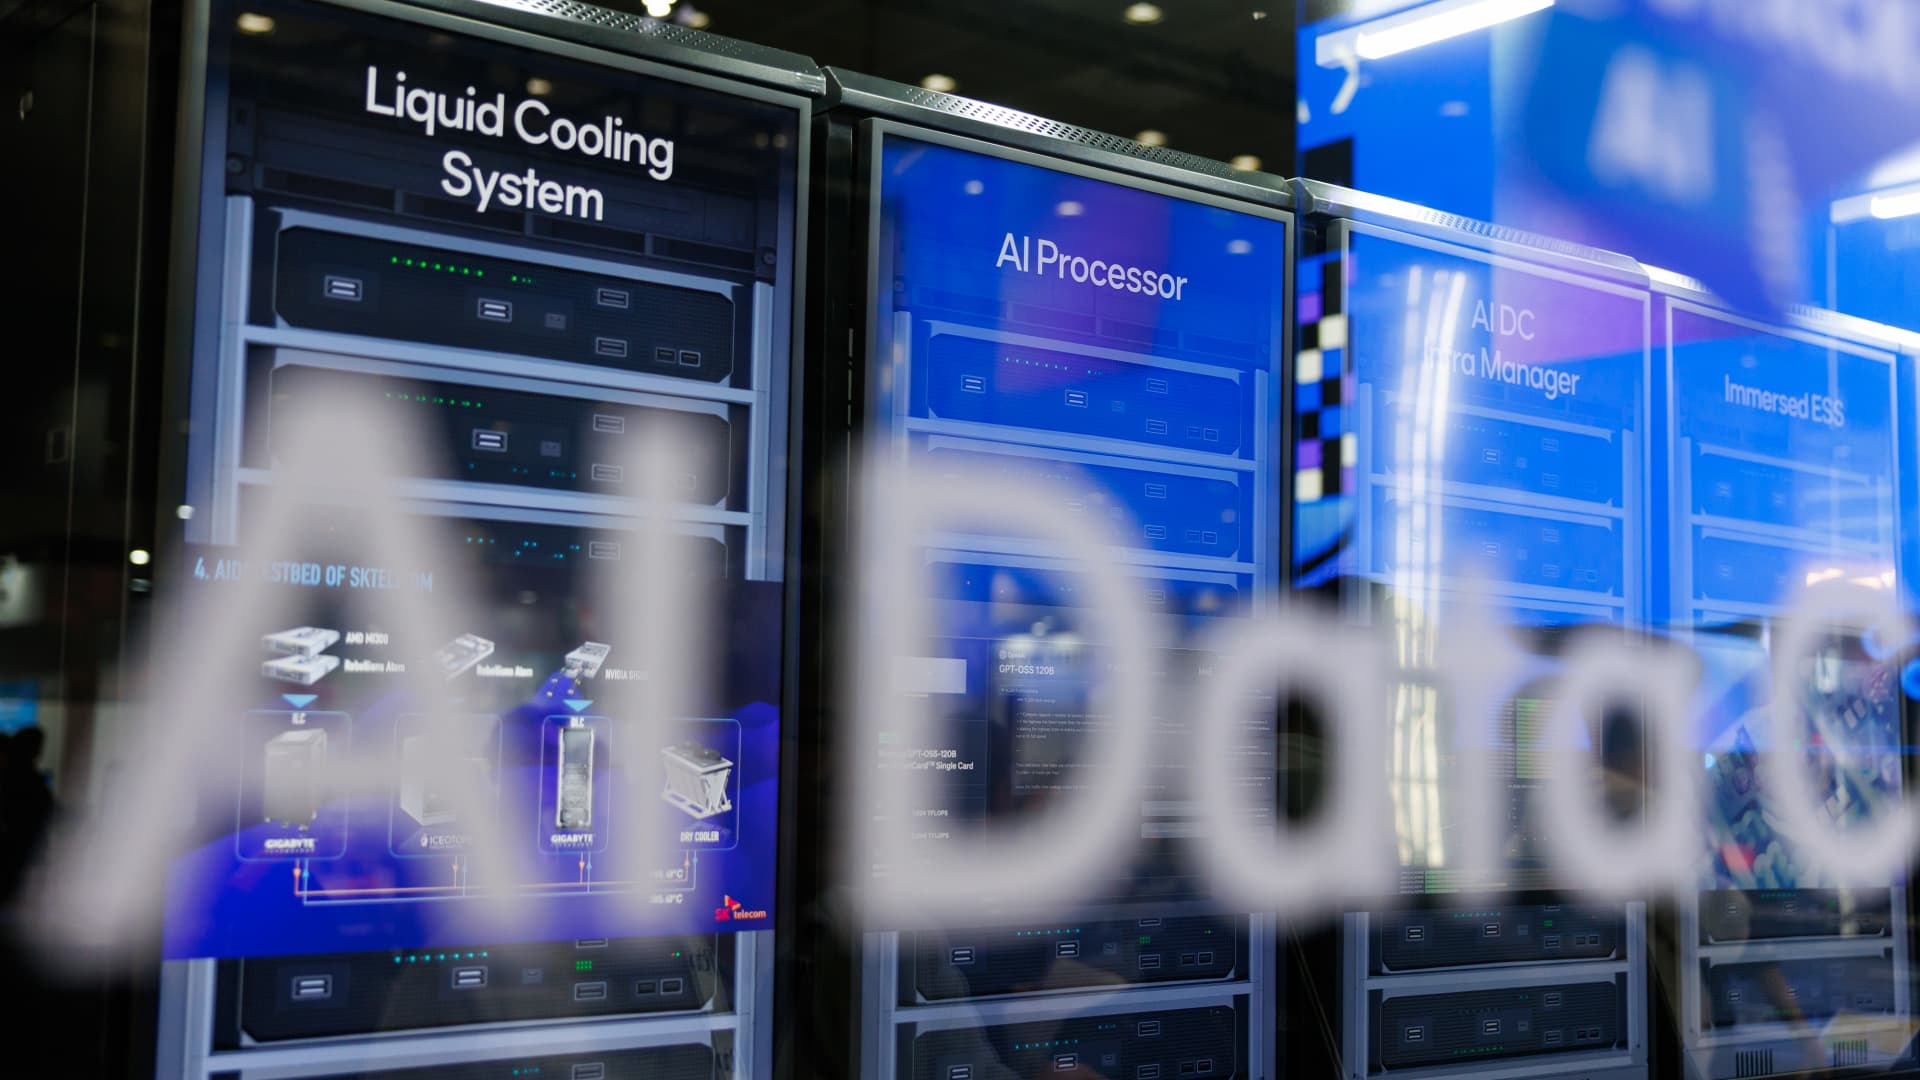
AI data center solutions at the SK Telecom Co. booth at the World IT Show on Wednesday, April 22, 2026 in Seoul, South Korea.
Cho Sung Joon | Bloomberg | Getty Images
The artificial intelligence boom may be entering an even more inexorable phase, as investors increasingly doubt whether the billions of dollars poured into data centers will lead to sustainable returns.
A disastrous stock market debut by South Korean AI infrastructure provider Eris is the latest warning sign that investors may be scrutinizing its ambitious expansion plans and path to profitability more closely.
Shares of the Seoul-based neocloud company plunged 32% in its trading debut on Tuesday, despite raising 201 billion won ($151 million) in an initial public offering at the highest market price. The stock then rebounded about 30% on Wednesday. Neoclouds provides specialized cloud infrastructure specifically for AI workloads.
“This is a testing moment for the tech industry,” said Dan Ives, a tech analyst at Yorkville Ives. “Investors are looking to better identify winners and losers and identify weak links in the tech AI food chain.”
He added: “Patience is wearing thin and there will be increased scrutiny, especially of companies with large debt burdens, such as some of Neocloud.”

The weak debut highlights a broader shift in sentiment toward the AI industry, with rising borrowing costs and concerns about debt-fueled expansion potentially forcing investors to differentiate between companies that generate cash in a boom and those that spend heavily in anticipation of future demand.
“AI trading has moved from a stage where the amount of capital investment announced was positive in and of itself to a stage where investors are asking who will actually get a decent return on that capital,” said Billy Leung of GlobalX ETF. “The market differentiates between companies that need capital to survive expansion and companies that are rewarded as they continue to expand.”
Leon said the most vulnerable companies are neo-cloud providers that are expanding faster than they can generate cash, especially those that rely heavily on external funding.
CoreWeave, one of the largest neo-cloud providers, is “the poster child for this whole thing,” said John Blank, chief equity strategist at Zacks Investment Research. “This is a stress on the entire market, not just speculation,” he said, pointing to widening credit spreads.
Companies that borrow heavily to build computing capacity could find themselves in trouble if financing costs rise faster than revenues, especially if construction costs and depreciation costs rise before the equipment is fully operational.
This shift is particularly important for Asia, where technology markets are heavily exposed to the semiconductor and memory chip industries that have been driving the global AI investment frenzy.
“The U.S. semiconductor and AI race is overbuilt, and it’s even more overbuilt in South Korea,” Blank said.
Beneficiaries of demand
South Korea’s SK Hynix and Samsung Electronics have been the biggest beneficiaries of a surge in demand for advanced memory chips, but their shares have come under pressure as investors reassess the sustainability of AI spending.
“Asia simply has a much more direct interest in the hardware and memory side of the AI trade, so when investors question AI capex and financing, South Korea and other North Asian technology markets feel it disproportionately,” Leong said.
He added that the rise in earnings estimates across South Korea and Taiwan suggests that recent stock declines reflect deteriorating sentiment and compressed valuations rather than a sudden collapse in demand.
This shift reflects a widening gulf between companies with the financial strength to sustain aggressive AI investments and those that rely heavily on financing to expand their operations.
HSBC Chief Executive Georges Erhedery warned that investors and lenders need to be more discerning about which data center projects are worth financing.
“You need to look at the quality of the tenancy agreement,” he says. “We need to look at the pricing of these contracts. Not all contracts are at a virtuosity level that we can strongly support. Some may be more difficult.”
