
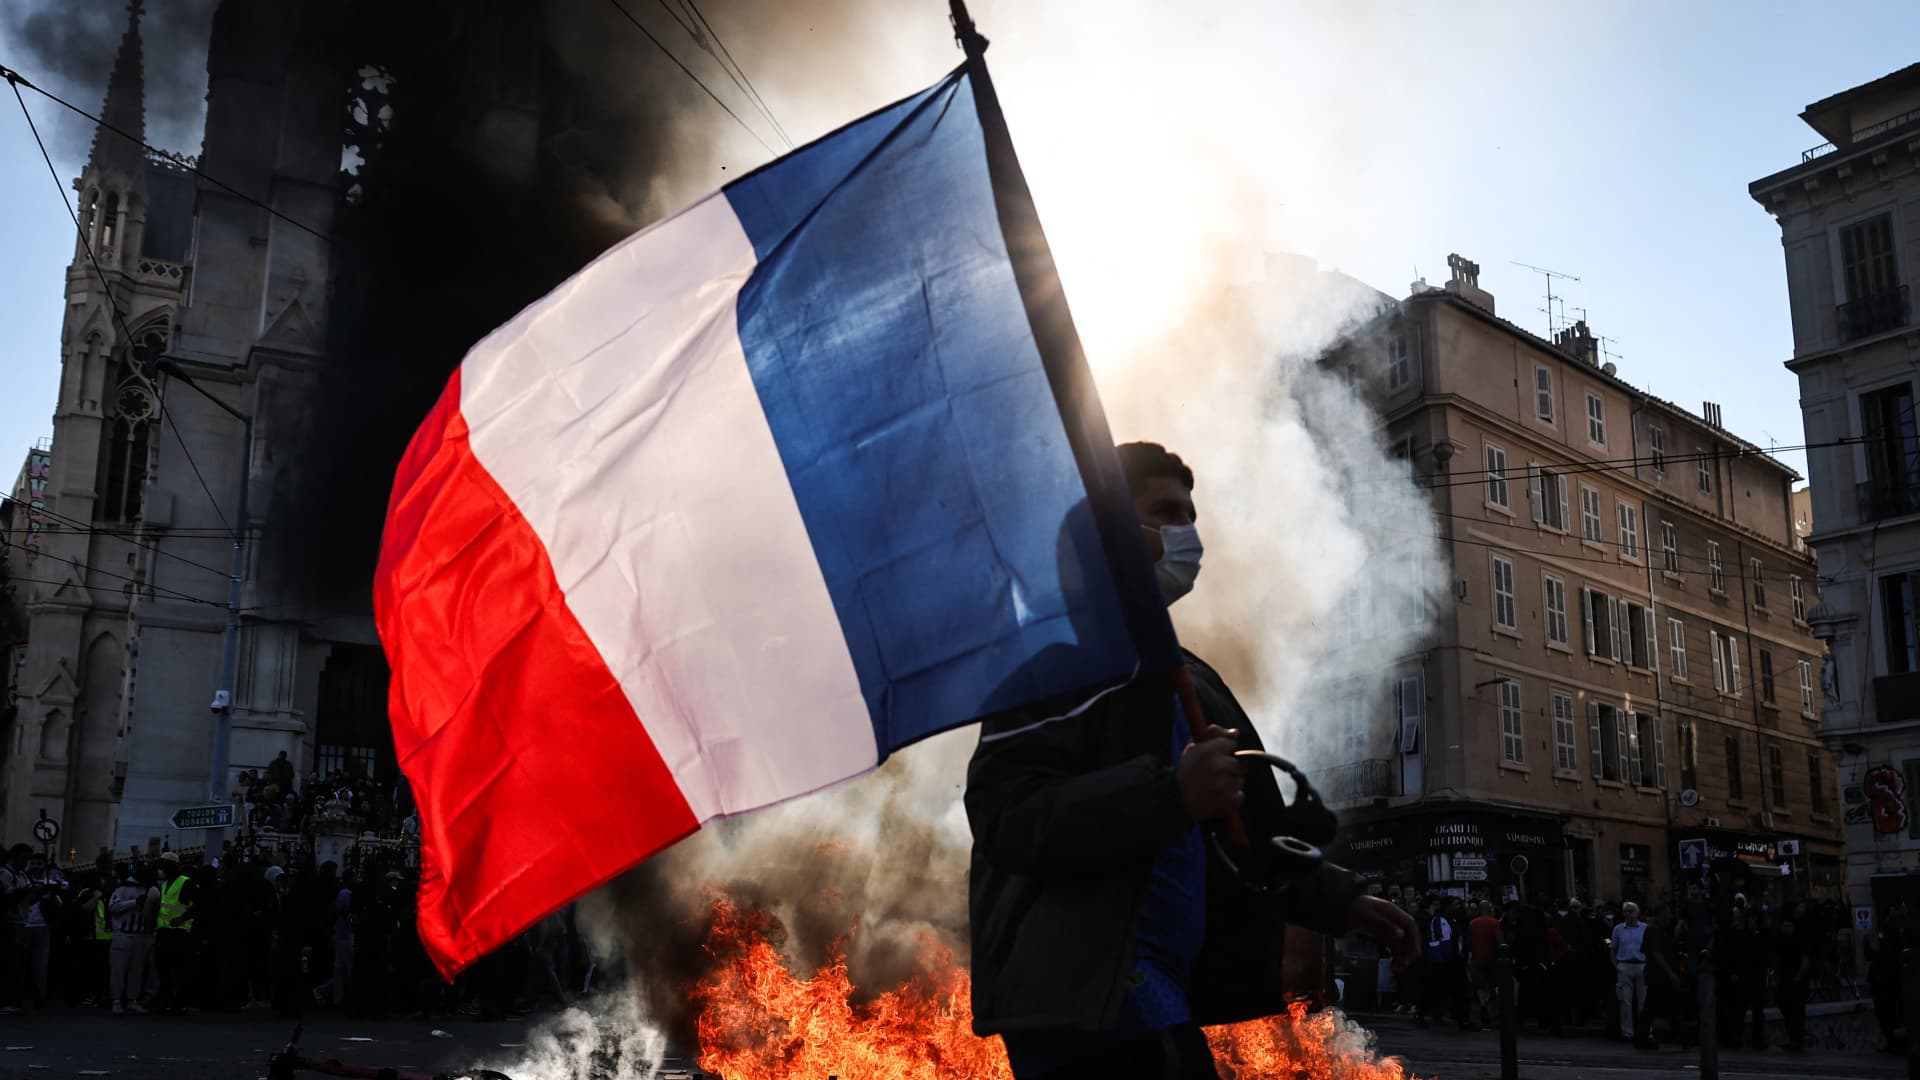
Protesters wave French flags as they pass by a fire during clashes before the start of a demonstration against the “high cost of living” in Marseille, southern France, on October 17, 2026.
Thibault Moritz | AFP | Getty Images
Credit markets are sounding the alarm as investors grow wary of borrowing risks, from AI companies funding data center projects to the heavily indebted French government.
Spreads on five-year credit default swaps widened. coreweave, oracle and Softbank GroupAs well as France and Italy, according to a CNBC analysis of FactSet data.
AI-related bonds are selling off as markets raise the cost of capital on concerns about a cash crunch. Nvidia CEO Jensen Huang told CNBC on Thursday that demand for NeoCloud was “unexpected,” but warned of a “lack of capital.” “The demand for capital far exceeds the availability of capital,” he said, adding, “That will be resolved.”
Countries like France are facing similar crises. Bond markets are under pressure as investors demand more compensation to finance public debt. The recent outbreak of large-scale protests and riots in France has heightened market concerns.
“The market may no longer want to take on large capital expenditures, high leverage, and uncertain future cash flows,” said Ben Emmons, CIO and founder of FedWatch Advisors. “The same changes are widening French sovereign spreads as they demand more coverage to finance their debt,” Ben Emmons, CIO and founder of FedWatch Advisors, wrote in a post on Substack’s “French Neocloud.”
AI-related debt increases insurance costs
CoreWeave, Oracle, and SoftBank are at the heart of building AI infrastructure across data centers, cloud services, and finance.
Their 5-year CDS spread provides a clue as to investors’ concerns about all expenses and bottom line returns. A higher spread means that default protection is more expensive and may indicate increased concerns about the borrower’s creditworthiness.
CoreWeave had the fastest increase in default protection costs. The company’s five-year CDS spread hit 1,065.84 basis points on Oct. 21, reflecting growing concerns about the debt-laden company’s ability to fund its expansion, according to FactSet.
At the same time, Oracle’s spread rose to 308.25 basis points on October 21st, up from 141 basis points on January 2nd. S&P Credit Ratings downgraded Oracle’s debt to the lowest level of investment grade in July, citing the expansion of its infrastructure business as increasing its overall credit risk.
SoftBank is a major AI investor, with a large stake in OpenAI and investments in data centers and power infrastructure, including an $87 billion investment in a data center in France. The five-year CDS spread was at a four-year high of around 432 basis points as of October 20, up from 284 basis points on January 5.
France’s debt default protection costs exceed Italy’s
Although France is not in a full-blown debt crisis, markets are concerned because the cost of protection from sovereign default exceeds Italy’s and is also increasing.
France’s five-year credit default swap spread reached 89.8 basis points on October 21, up from 29.74 basis points on January 2, according to CNBC analysis. The Italian spread widened from 28.33 basis points on January 2nd to 67.1 basis points on October 22nd. The focus is on France’s fiscal uncertainty and debt burden, raising concerns that risks could spill over to other European countries.
German spreads also rose, but were still significantly lower at 12.15 basis points as of October 22, compared to 7.47 basis points at the beginning of the period.
Macquarie Group global currency and interest rate strategist Thierry Wismann said France’s rising debt burden and persistent budget deficit were the main drivers of rising default protection costs.
“The main factors are the huge French national debt (120% of GDP) and the impossibility of reducing the deficit,” Wismann told CNBC. Compared to France, Germany’s government debt accounts for 65% of the country’s GDP.
Investors are also focusing on the spread between French and German bonds, a measure of European creditworthiness, which also rose to 1.6 percentage points. France’s 10-year bond yield also exceeded 5% for the first time since 2002. The spread between the French OAT and the German bond’s 10-year yield is the additional payment an investor would be required to make to hold a French bond rather than a German bond.
Although the Franco-German spread is relatively wide, the difference in borrowing costs was much larger in the euro area during the euro area debt crisis of the early 2010s.
France faces a new challenge as Moody’s plans to review its Aa3 sovereign rating with a negative outlook on October 23. The review comes as political divisions complicate efforts to rebuild the country’s finances.
Spillover effect on bond indexes
While some AI lending is experiencing stress, bond markets are also pricing in higher costs. S&P Global warned on October 19 that major cloud providers may have more AI-related debt exposure than publicly acknowledged.
The CDS Index provides a broader picture of credit market pressures by tracking default protection costs across a basket of companies.
The North American CDX High Yield Index captures credit risk across speculative-grade companies. The five-year interim spread reached 355.35 basis points on Oct. 20, up about 39 basis points from the end of 2025, according to LSEG data.
This widening suggests investors are seeking more coverage for credit risk beyond AI-related borrowers.
