
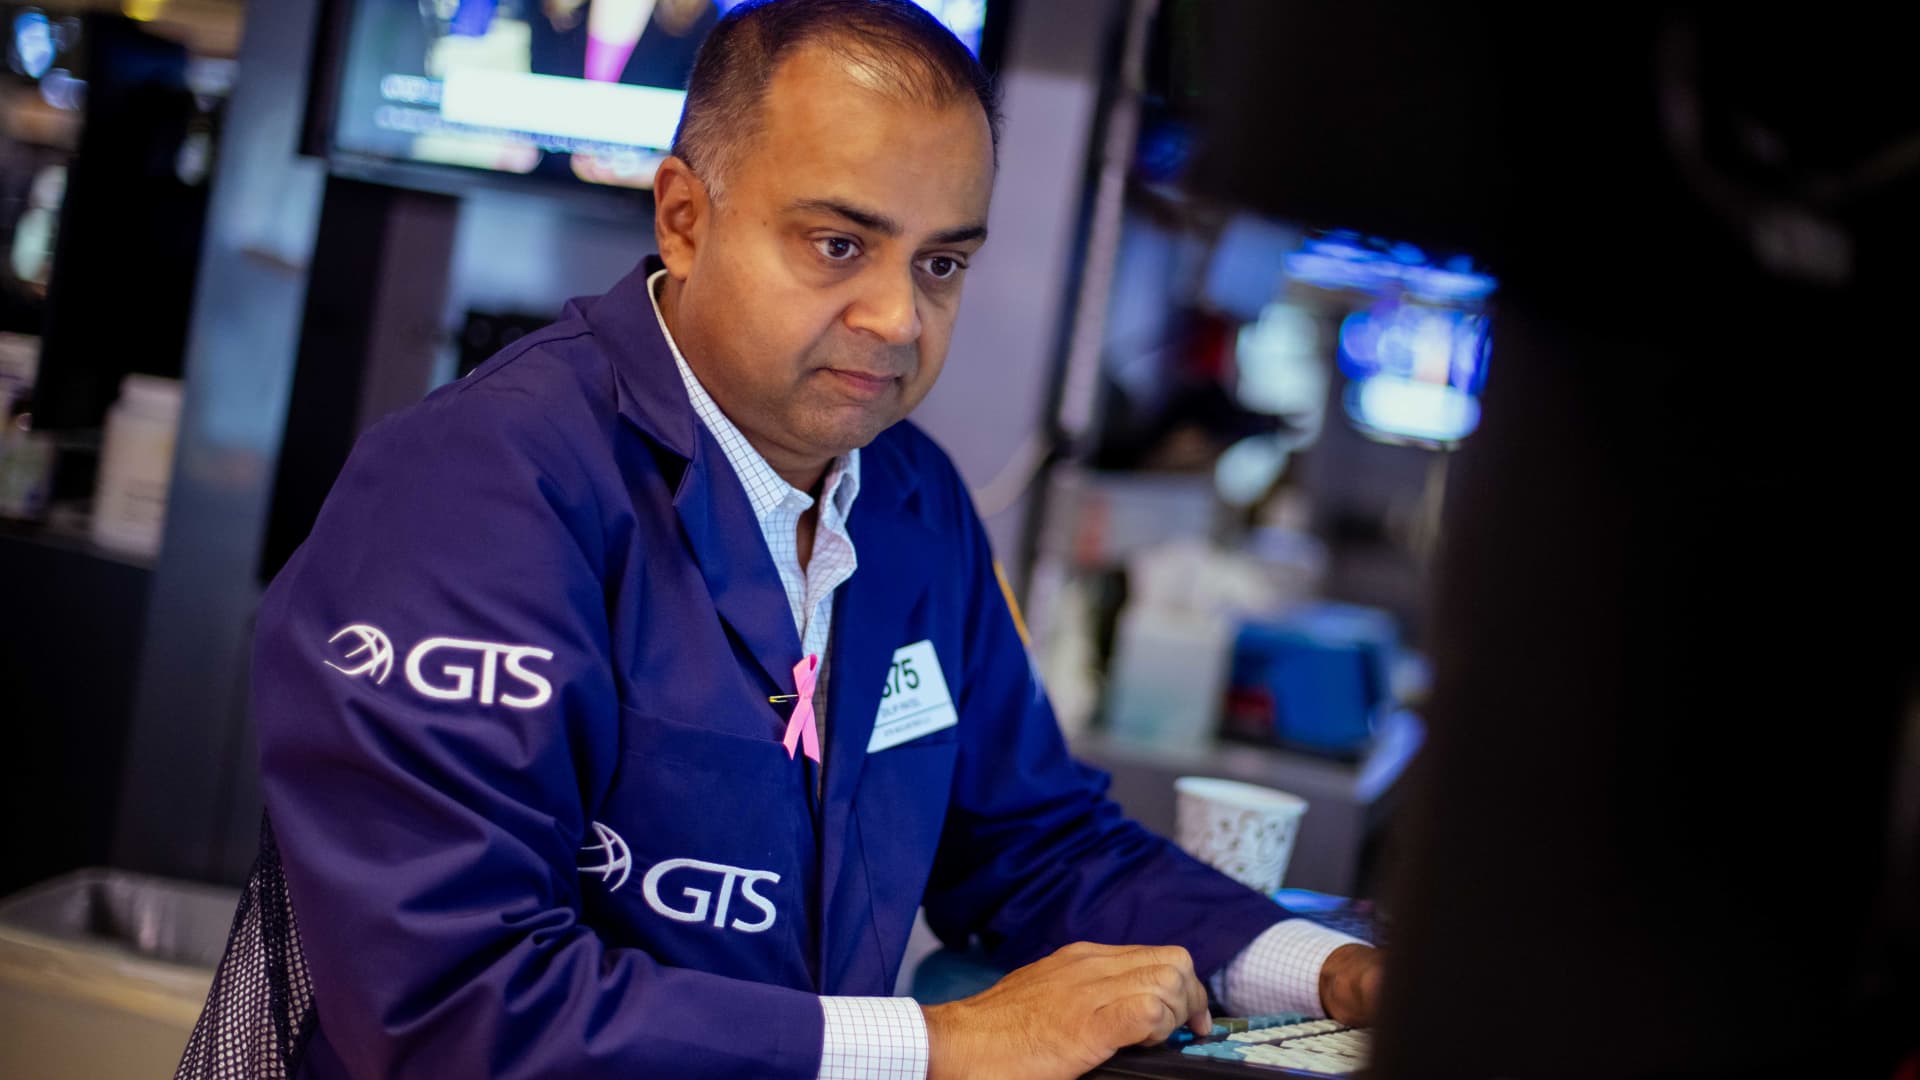
October 19, 2026 Trader working at the New York Stock Exchange.
new york stock exchange
Even after bond markets fell again on Friday, investors are turning their attention to U.S. Treasuries in hopes of yields peaking.
benchmark 10 year bond We spent the day worrying about the psychologically important 5% level as oil prices soared and new consumer surveys showed inflation expectations remained well above the Federal Reserve’s 2% target.
Still, some market participants see some silver lining in the market’s weakness this year due to concerns about rising prices, tensions in the Middle East and intense competition from artificial intelligence hyperscalers that have flooded the market with debt.
Bank of America’s Michael Hartnett declared in a note to clients that “the price is right” in the battered Treasury market, noting that the market’s long-term returns are the worst in 100 years.
“A secular contrarian (trade) will add to bonds,” the investment strategist noted in a summary of weekly money flows, drawing parallels with similar long-term negative returns in stocks and commodities that later turned out to be good entry points.
Investors have been putting money into bonds and Treasuries in particular this year, despite negative returns and soaring yields.
Over the past week, U.S. Treasuries have seen $5.4 billion in flows, part of a total of $12.1 billion into the bond market, according to data compiled by BofA. of iShares 20+ year government bonds The ETF, a $47.3 billion fund that provides exposure to long-term government debt, has seen $1.14 billion in new cash inflows from investors over the past month.
One of the reasons investors are so excited is the simple belief that the market has priced in the various risks to the market, is now at least poised to stabilize, and that the sell-off in Treasuries is over.
In Thursday trading, the 10-year Treasury yield rose by a hefty 19 basis points (0.19 percentage point).

This week’s 10-year bond yield
Nicholas Colas, co-founder of DataTrek Research, calculated the rise as a “three standard deviation move,” meaning it was well above the expected trading range for major government bonds that day. The trade “was not a sudden change in the market’s view of the U.S. economy,” Collas wrote in his daily market note, given Thursday’s renewed optimism in jobless claims.
“We believe that the U.S. Treasury market may be interpreting concerns in the stock and corporate bond markets about AI-related capital investment funding as a sign that the pace of issuance is slowing,” he added. “The less this paper is on the market, the less competition the Treasury will have for capital.”
Historically, stocks and bonds generally move in opposition to each other. As risk appetite increases, investors generally avoid the safety of bonds, and vice versa.
Friday’s stock market decline coincided with an aggressive sell-off in bonds, a trend not seen recently, with trades driven primarily by concerns that high oil prices would hit both asset classes.
But Colas said history suggests correlations will return, making a combination of stocks and bonds “still a reasonable approach despite recent painful history.”
He also said Thursday’s plunge in yields was an “important signal.”
“While the interest rate fever may not be completely over, (Thursday) was a solid step in the right direction,” he said.
