

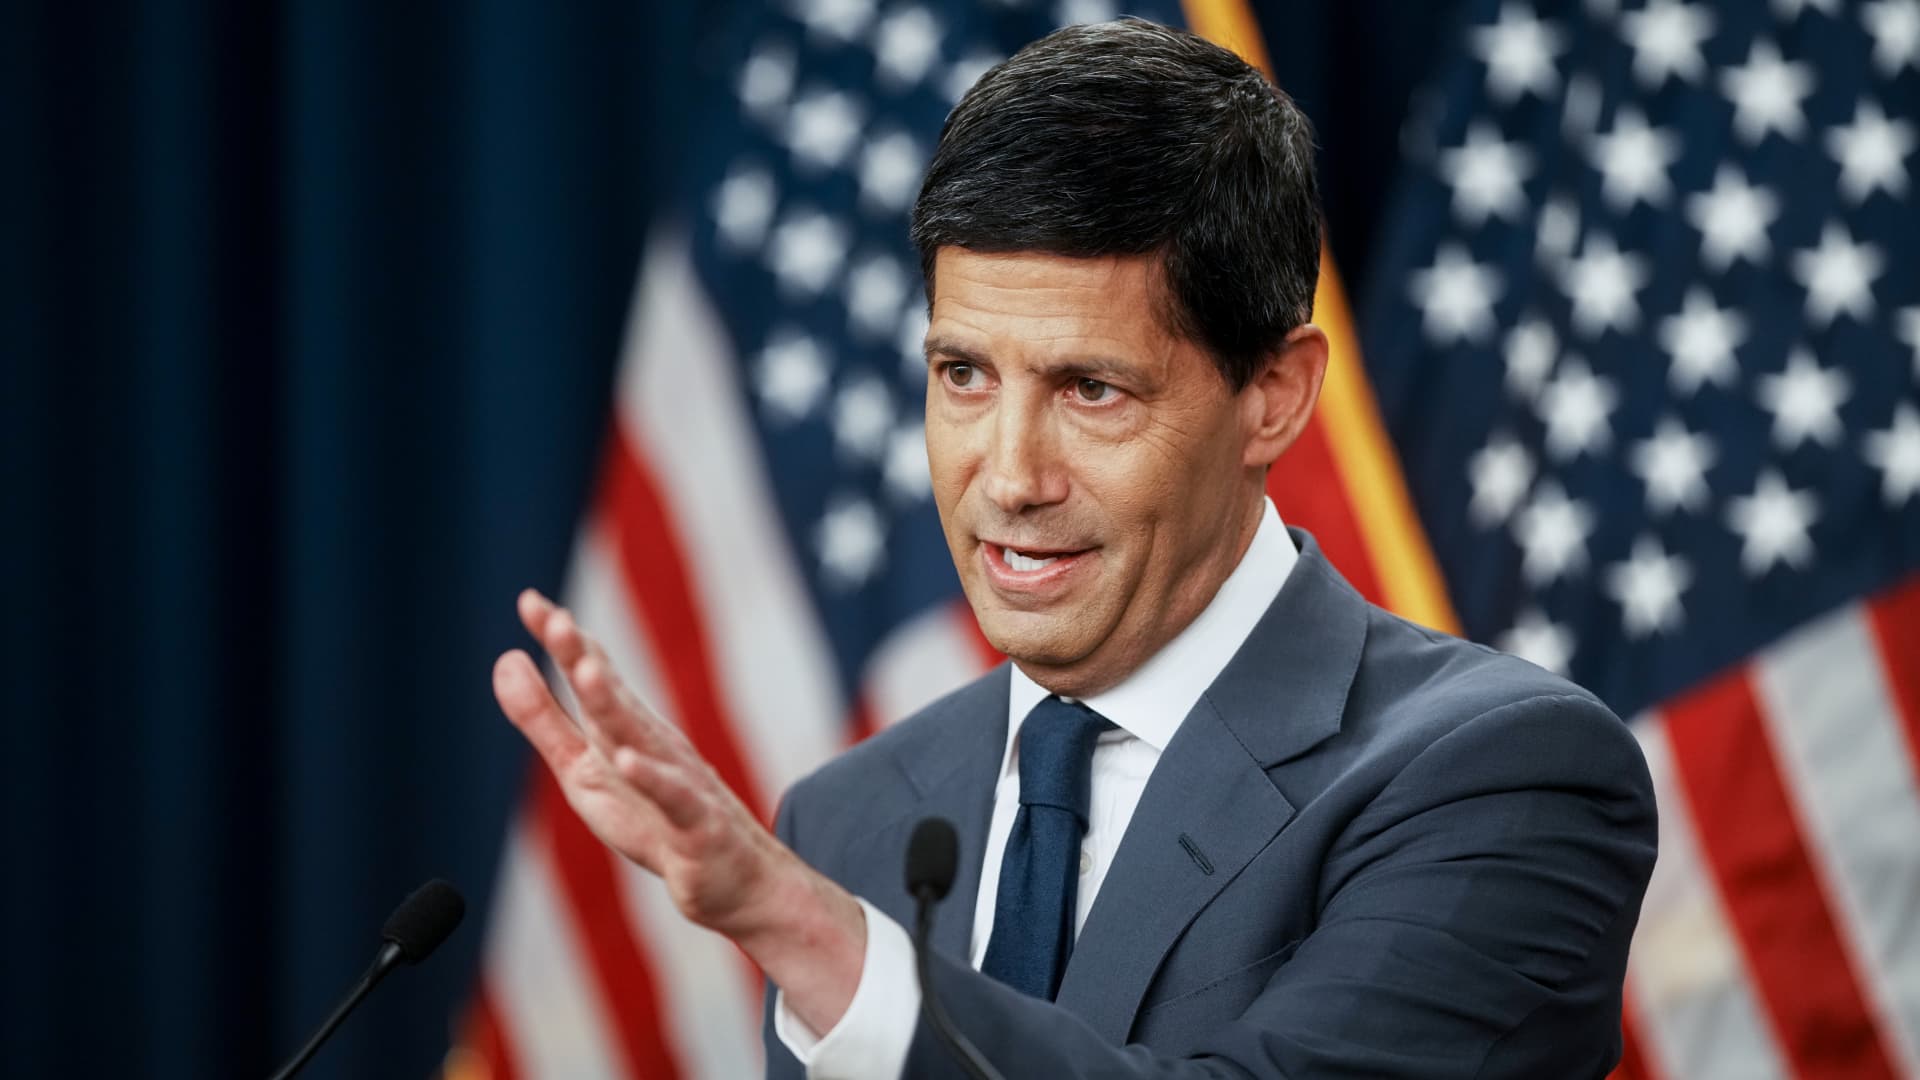
Federal Reserve Chairman Kevin Warsh during a press conference after the Federal Open Market Committee on October 28, 2026 in Washington.
Al Drago | Bloomberg | Getty Images
After the Fed left its benchmark interest rate unchanged last week, Fed Chairman Kevin Warsh announced plans to reduce the number of votes that set interest rates over the next two years. The move could extend the timeline for ordinary Americans to see borrowing costs adjust, some experts say.
“Fewer Fed meetings in 2027 could mean consumers wait longer for relief when borrowing costs rise,” said James Vlachas, executive director of advisory firm Post Oak Group.
While Americans may feel a little alienated from the Fed, its moves have ripple effects on a range of consumer products, including interest rates on credit cards, mortgages and car loans.
For example, most credit cards’ variable interest rates are tied to the prime rate, which moves in line with the Federal Reserve’s benchmark. However, LendingTree says credit card interest rates are creeping up even as central bank interest rates remain unchanged as issuers protect themselves from risk.
Matt Schultz, chief credit analyst at LendingTree, said card issuers are reducing risk from borrowers who may miss payments or default in the face of stubborn inflation in everyday spending.
Schultz said card issuers are generally slow to lower interest rates unless prompted by Fed action. “Card issuers may tinker with rates a little at the last minute at other times, but big moves tend to only happen when issuers are pushed into a corner.”

The central bank voted on Oct. 28 to keep its benchmark borrowing rate at its current target range of 3.75% to 4% as policymakers consider next steps as inflation remains well above the Fed’s 2% target.
Warsh said in a press conference after the October meeting that the Fed would continue to meet eight times a year, but that next year, one of the eight meetings would not include a vote on interest rates and would not include a post-meeting statement. Next year, the number of “strategy” meetings will increase to two, leaving only six opportunities to adjust interest rates, excluding emergency meetings when necessary.
“For consumers, this could mean an extended period of uncertainty around borrowing costs,” said Jordan Ricciardi, senior wealth strategy associate at UBS. “Customers looking to buy a home, refinance a mortgage, or finance a business may be affected because fewer scheduled opportunities mean the Fed is not responding quickly to changing economic conditions.”
Borrowing interest rates may remain high for a long period of time
Post Oak Group’s Vrachas said fewer opportunities for scheduled interest rate adjustments mean borrowing rates could remain high even if economic conditions start to improve.
He said that currently, financial institutions can adjust interest rates at any time based on market conditions, regardless of the Fed’s meeting schedule. But in the meantime, many consumers may continue to face higher borrowing costs for financial products such as mortgages, auto loans and credit card debt.
“The bigger concern for consumers is not necessarily that there will be fewer meetings, but whether lenders will pass on lower borrowing costs as quickly as they do,” Vlachas said.
“Warsh keeps his proverbial cards close to his chest.”
Economists say consumers could be hit even harder by the lack of transparency, as Warsh has taken steps to curb so-called forward guidance, the way the Fed signals future interest rate movements.
Although the economic picture has become more complex and information more widely available, “Mr. Warsh is carrying his proverbial cards closer to his chest than his recent predecessors,” said Mark Hamrick, an economic analyst and founder of the weekly newsletter Hamrick Brief.
“I don’t think consumers will see the world of market interest rates change just because the Fed votes less,” he said. “But the public may hear less from stakeholders about how and why the Fed makes decisions that determine how much money to borrow and how much to save.”
In the meantime, “consumers’ best protection is to shop around for the highest yields, especially in savings accounts and (certificates of deposit),” Hamrick said.
As long as the Fed keeps interest rates on hold, some high-yield online savings accounts are offering interest rates as high as 4% or more, according to Bankrate data. “This is one of the benefits of a high interest rate environment; savers can earn meaningfully higher yields,” Hamrick said.
Subscribe to CNBC on YouTube.
