
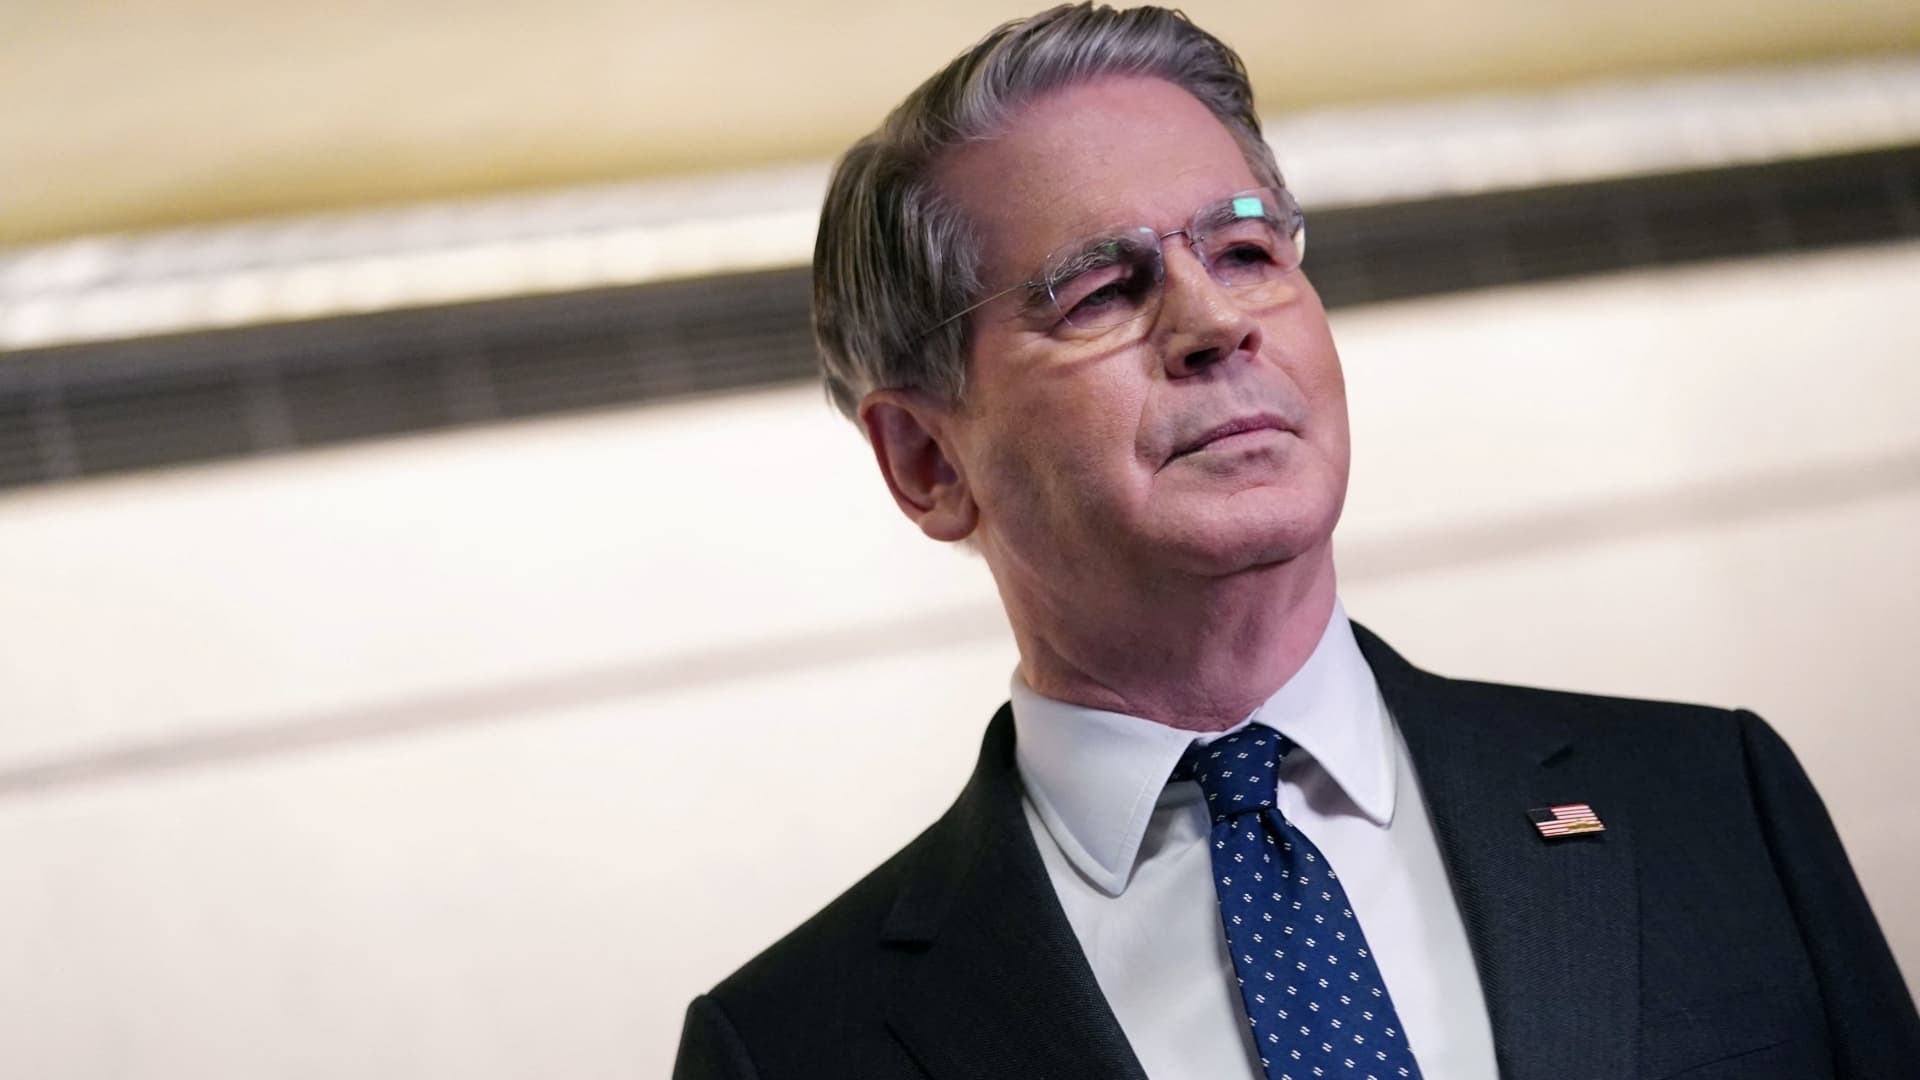
U.S. Treasury Secretary Scott Bessent speaks to the media at the World Bank on the day of his meeting with Chinese Vice Premier He Lifeng on September 23, 2026 in Washington, DC.
Nathan Howard | Reuters
The spike in Treasury yields isn’t just bad for the government and its $40 trillion in debt. It also threatens to hurt everyone from homeowners to credit card users and raise borrowing costs, while offering limited relief to consumers and potential benefits to banks.
The cost of government debt rose sharply on Wednesday, the result of a combination of factors, including new reports showing rising inflationary pressures, rising expectations for an October rate hike from the Federal Reserve, and a five-year bond auction showing weak demand from the Treasury. Competition from hyperscalers’ bond issuances is also seen as an aggravating factor.
Yields reacted by rising for the first time in about a year and a half since April 2025, when President Donald Trump first announced so-called reciprocal tariffs on U.S. trading partners. Recent market liquidity measures promoted by Treasury Secretary Scott Bessent have so far been ineffective, and interest rates have soared despite stepped-up efforts to buy back long-term debt.
The yield on the 10-year Treasury note, the benchmark for mortgages and other long-term debt, hit 5.125%, the highest level since before the global financial crisis. Similarly, two-year Treasuries, which typically react to Fed rate expectations and measure interest rates on mortgages, auto loans and other debt, rose more than 13 basis points to more than 4.9% as traders priced in the Fed likely to raise rates again in October, following last week’s hike.

Government bond yield
One basis point equals 0.01%, and the yield moves inversely to the price.
Such moves generally portend higher borrowing rates, hitting the U.S. economy hardest hit: consumers, who drive nearly 70% of all economic activity and carry nearly $19 trillion in debt.
Dan North, senior economist at Allianz Trade North America, said savers will benefit from a gradual increase in interest rates on bank savings accounts, but it’s unlikely to offset the pain felt elsewhere.
“Consumers are the most important part of the economy,” North said. “You’ve gone from a very small savings rate to a slightly larger savings rate. So I don’t think it’s helping consumers all that much yet. But housing has definitely been destroyed, and it’s affecting personal consumer loans, credit cards and things like that.”

In fact, interest rates on savings accounts are about 0.37%, according to FDIC data, and have been declining slowly since the Fed cut rates three quarter-points in late 2025.
However, mortgage rates are on a very different trajectory and are likely to continue rising. The standard 30-year mortgage rate is currently 7.26%, up more than a quarter of a point in just the past few weeks and nearly a full point over the past year, according to Mortgage News Daily.
Credit card interest rates have been fairly stable over the past few years, but they’re unlikely to stay that way as long as current trends continue.
structure
When the Fed raises interest rates, it is reflected directly in the prime rate. The prime rate, used as the baseline for floating rate credit, was most recently at 7%, after increasing by a quarter of a point from the Fed’s policy last week.
Taken together, these factors make it more expensive for consumers to borrow and less likely to seek the loans and credits that fuel much of the activity in the $32 trillion U.S. economy.
“When you raise the federal funds rate, you essentially raise interest rates along the entire curve in the short term,” North said. “If it’s harder for someone to buy a car, there’s less demand for cars, less demand for auto workers, and the economy slows down. It’s kind of basic economics, but that’s how it works.”
There are some positive aspects to higher interest rates.
Apart from the profits earned by savers, banks also earn profits. The industry’s model is based on a variety of factors that could benefit when interest rates rise, from what they can charge borrowers to the margins they can earn on the charges they pay depositors to the opportunity to increase their return on cash.
But even bank stocks, otherwise solid, mostly fell on Wednesday as sharply higher yields could slow demand for loans and overall economic activity. The Atlanta Fed forecast third-quarter GDP growth of 5.1%, another factor that could be factored into the rise in yields.
KBW Bank Index, year-to-date
However, the continuous increase in yield poses a risk to its growing situation.
“Small businesses are going to be in the worst trouble because they have less ability to borrow,” North said. “It gets even harder when you have less credit available.”

