
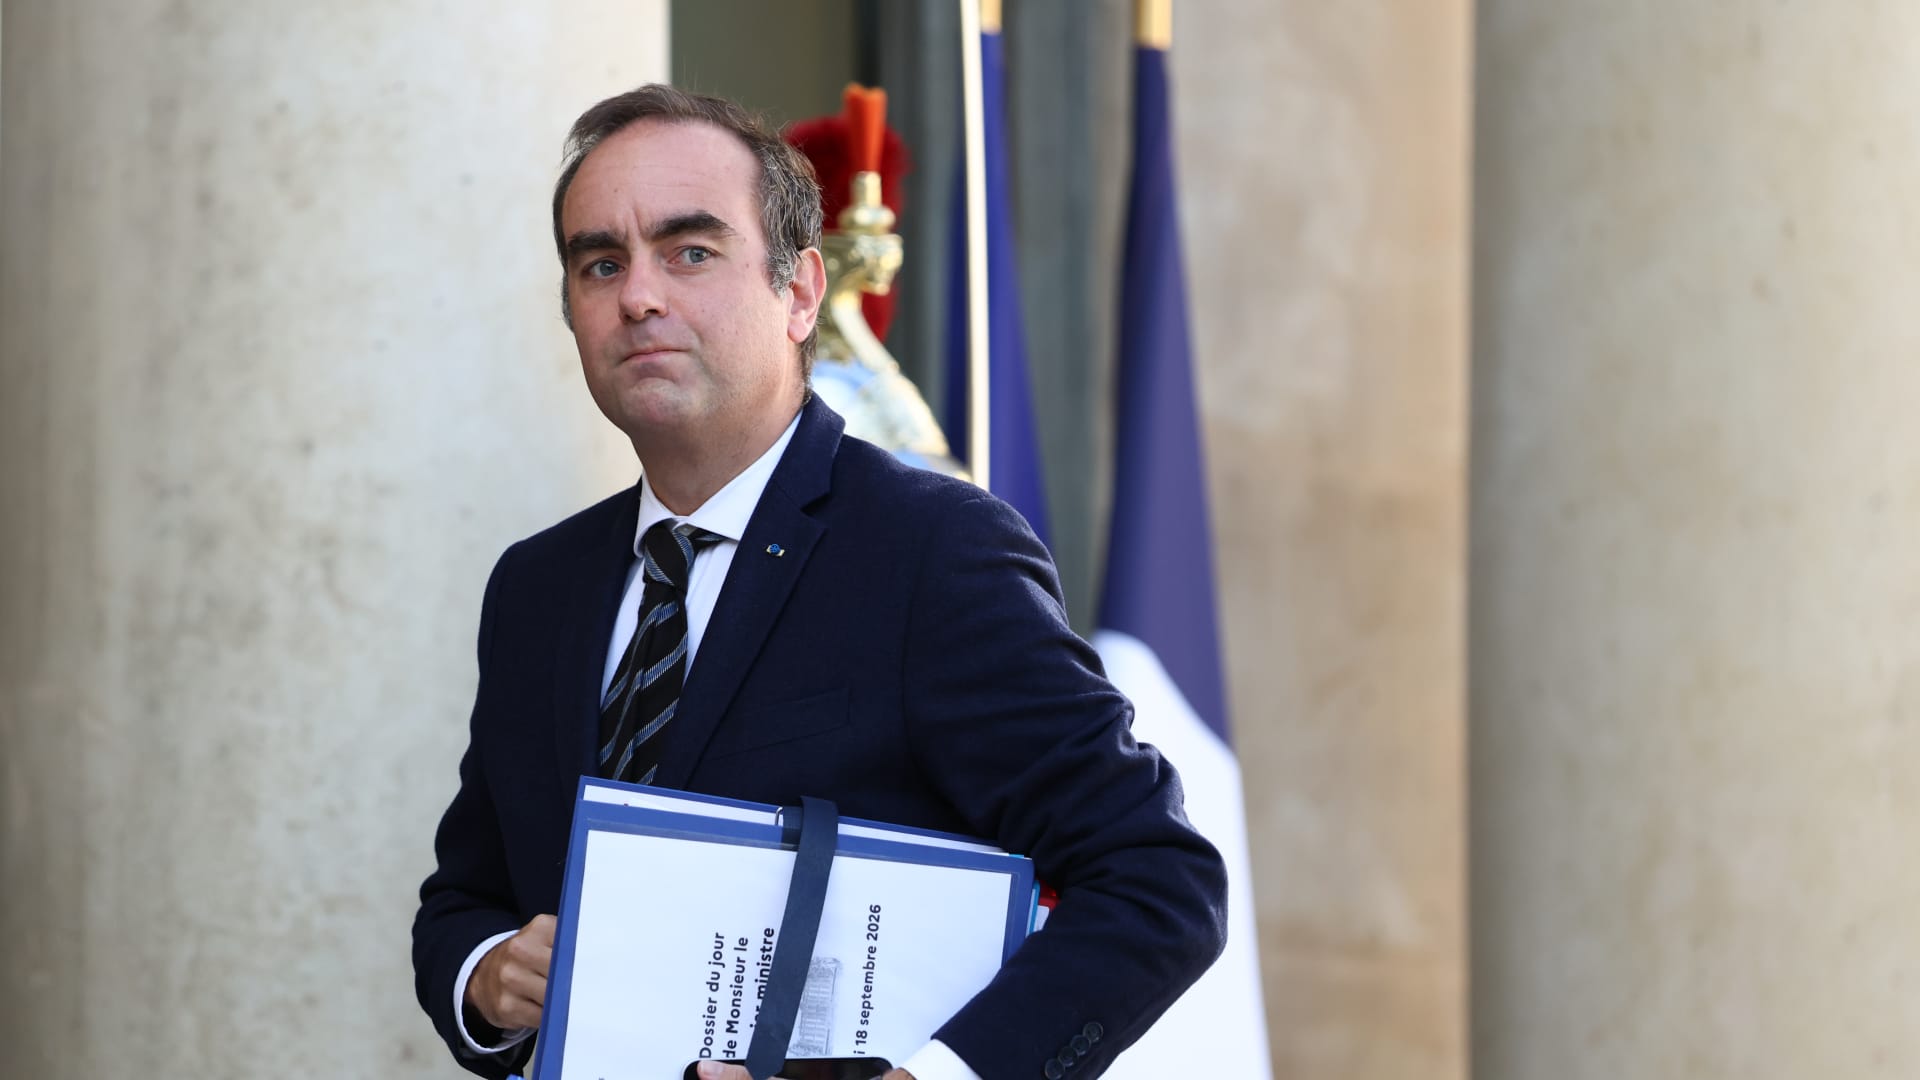
French Prime Minister Sébastien Lecornu arrives at the Elysée Palace in Paris, France, on September 18, 2026.
Tom Nicholson | Getty Images
France is paying a higher risk premium than ever on its debt, threatening to topple yet another leader as investors brace for a third consecutive year of budget drama.
country yield 10 year government bond The index, known as OAT, rose above 4.5% on Friday for the first time since 2008 and has remained above that threshold ever since. It was last traded on Thursday with a yield of 4.6696%.
France’s 10-year bond yield is currently more than 1 percentage point higher than the 10-year bond yield. german 10 year bond Markets continue to demand greater compensation for loans to France than to Italy and Greece, the troublemakers of the crisis.
Furthermore, across the entire yield curve, France has some of the highest government borrowing costs in the G7 group of developed economies.
On Saturday, France’s finance ministry announced that it expects the country’s debt to reach a record high of 119.3% of gross domestic product in 2026, and the debt-to-GDP ratio to reach 121.7% in 2027.
But ever since France’s snap elections in July 2024 failed to secure an absolute parliamentary majority, political divisions in the National Assembly, including the far-right National Rally, the left-wing New Popular Front and the center-right group led by L’Ecornu, have been at odds over the budget dispute.
The government was overthrown by votes of no confidence in December 2024 and September 2025, but it took until February this year for Lecorne to pass the 2026 budget thanks to a constitutional provision that allowed him to bypass parliament.

“Despite widespread public desire to avoid a political crisis before next spring’s presidential elections, the tough 2027 budget risks toppling the government,” Mujtaba Rahman, managing director for Europe at Eurasia Group, said in a note on Monday.
Mr. Rahman said that measures such as a partial pension freeze would be opposed by all parliamentary factions, but that Mr. L’Ecornu was determined to end his final months as prime minister, perhaps by forcing a vote on a budget that “at least in theory begins the long-term task of putting France’s public finances in order.”
That could include negotiating with rival parties in the coming weeks to compromise on certain issues, or appealing again to special constitutional powers to pass a budget by the mid-December deadline, Rahman added.
‘Time is not in our favor’ for French government bonds
Benjamin Schroeder and Michelle Tucker, interest rate strategists at ING, said in a note on Monday that the government’s efforts to move this year’s budget deficit back towards 5% from the expected 5.4% face “strong political headwinds.”
“But beyond that, we argue that this is not a favorable time for French bond spreads. After this year’s budget, the focus will shift to the presidential elections, likely followed by parliamentary elections and another potentially difficult government-formation process,” they said.
Throughout his nine-year term, President Emmanuel Macron has installed a succession of unpopular centrist supporters as prime minister. Next year’s presidential election could bring shockwaves between political extremes and bring the issue of parliamentary leadership back into the spotlight.
ING strategists expect the so-called OAT-Bund spread between French and German borrowing costs to remain between 100 and 125 basis points in the coming months, due to the unfavorable combination of high European energy costs and fractures in European Union cohesion. He added that while the European Central Bank is focused on new inflationary pressures, it may be reluctant to intervene to tighten spreads through bond purchases.
Chris Attfield, European interest rate strategist at HSBC, said the change in the spread between OAT and German government bonds was “much larger than we expected” given France’s debt-to-GDP ratio, but added that the ECB was likely to intervene only if market movements became “disorderly”.
“One complicating factor is that non-domestic OAT ownership has been rising, with ownership now above 50%. If these investors prove less ‘sticky,’ that raises the question of where are the swing investors who will increase their holdings to compensate, and more importantly, at what price?” Attfield said in a note on Monday.
BNP Paribas Chief Financial Officer Lars Mashnir said in an interview with CNBC’s Karen Tso on Wednesday that it was important for lawmakers to work on reducing France’s debt, but “they should take the time to come up with a meaningful budget and move in the right direction.”
Asked if he thought a budget would be agreed and approved before the deadline, he added: “I don’t have a crystal ball, but what I see is that there is a willingness to get over this (red line).”
“We’ll see. But looking at the progress and the timing, I think things are going well,” Machenil said.
