

State and federal regulators are scrambling to fill holes in U.S. cryptocurrency regulation after the Clarity Act, a comprehensive set of rules for digital assets, stalled in the Senate.
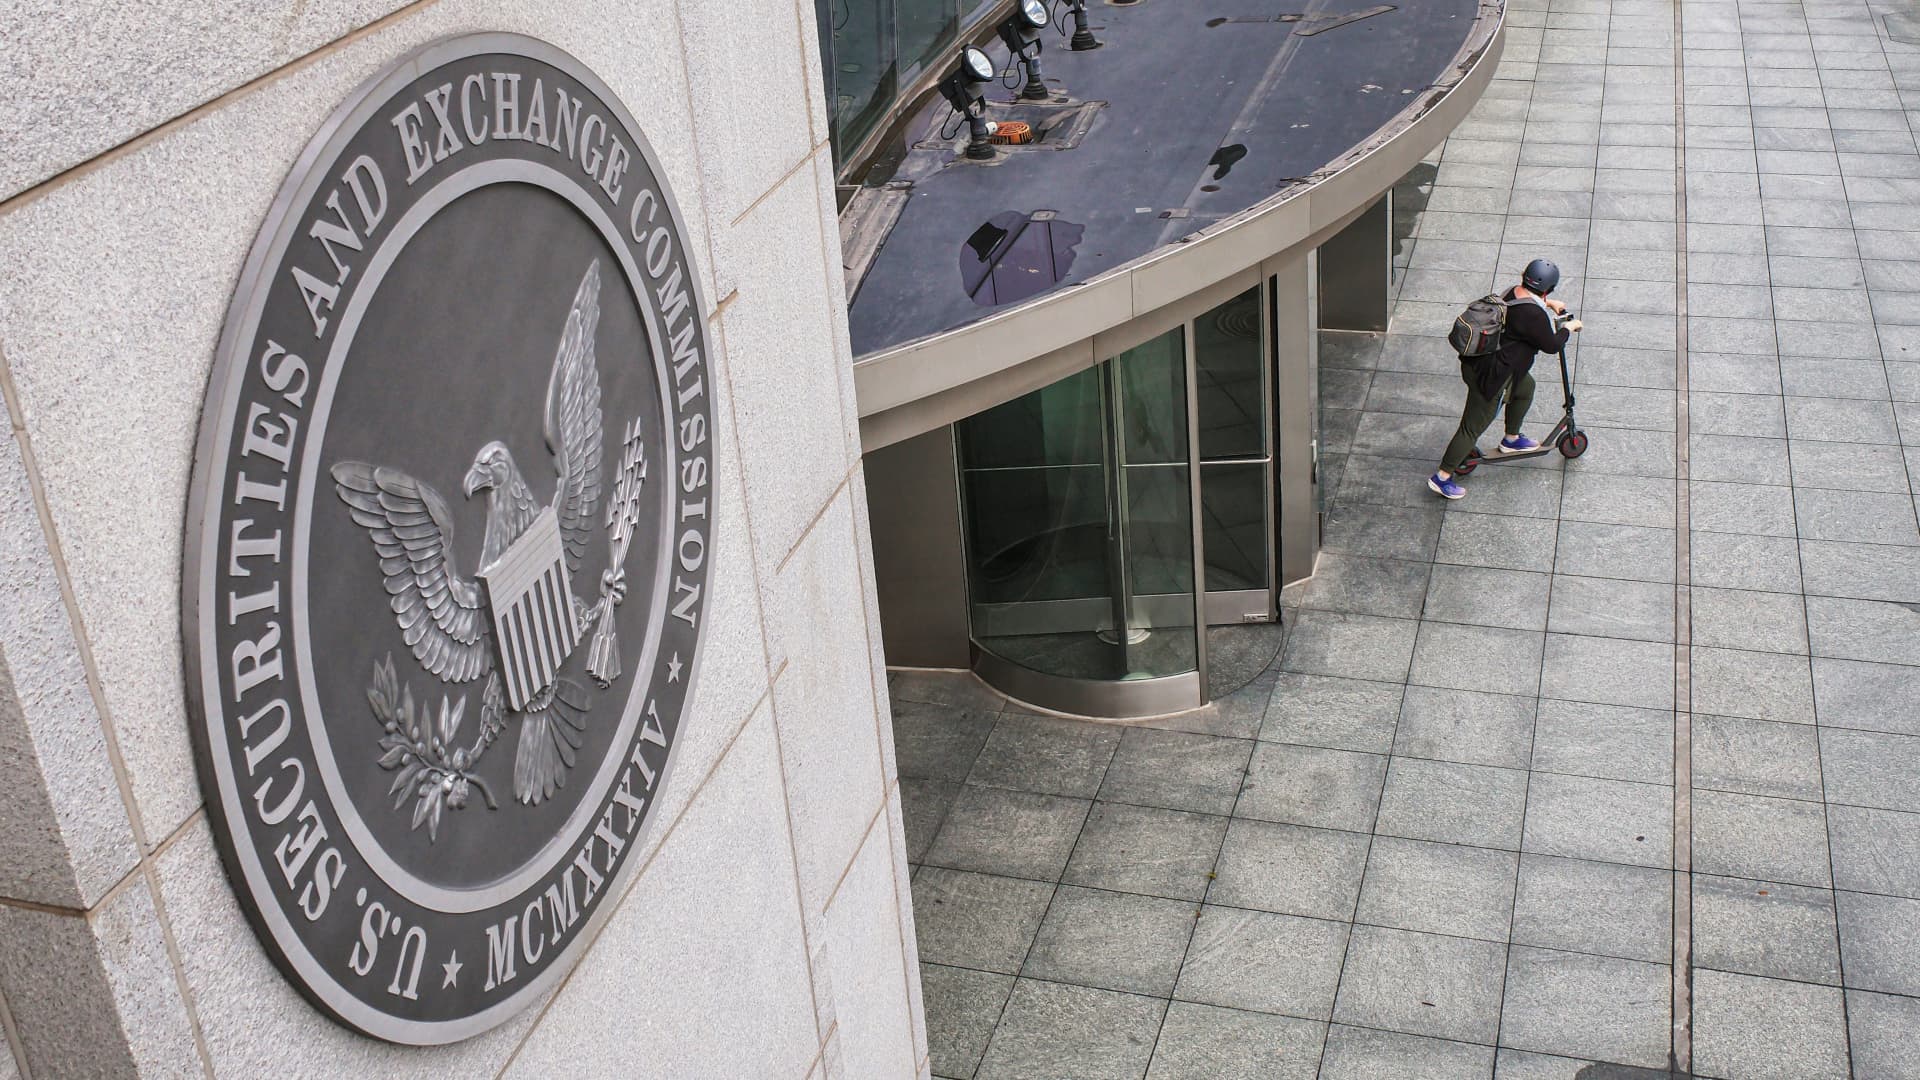
Just two days after the Transparency Act failed to pass the Senate, the Securities and Exchange Commission expanded its cryptocurrency rulebook based on existing authority. The agency issued an order creating temporary channels for trading certain tokenized stocks, bringing financial markets closer to 24/7 trading.
On the same day, the Commodity Futures Trading Commission submitted proposed virtual currency rulemaking to the White House for review. Details of the proposal have not been made public, but a post from the Office of Management and Budget confirmed that the rule is under consideration.
The crypto industry, which has supported the Clarity Act, said it is eager for regulatory guidelines for the developing industry, as it has sought to shape the regulatory environment to its liking.
“When you think about traditional finance getting into and using some of this technology, it’s currently held back because of the regulatory uncertainty,” said Summer Marsinger, CEO of the Blockchain Association and former CFTC commissioner. “Having regulators provide some certainty will really open up the industry to more investment and integration into traditional finance, which will really allow the sector to grow.”
and coinbase “I don’t think we can wait for Congress and the Senate to ask us at this point,” CEO Brian Armstrong, a leading industry player urging Congress to act under the Transparency Act, told CNBC after the Sept. 15 Senate procedural vote failed. Senate Banking Committee Chairman Tim Scott, R-S.C., also called on federal agencies to set “clear rules” regarding digital assets until Congress enacts them.
But new rules from the federal agency won’t come soon.
When asked how it intends to regulate cryptocurrencies, the CFTC pointed CNBC to Chairman Michael Selig’s September 16 statement, saying, “President Trump has committed to some form of future-proof crypto regulatory market structure, and we will use existing legal authority to help him accomplish that task.”
CNBC also contacted the SEC about next steps to regulate the digital asset industry, with a spokesperson saying the agency would consider proposals to “modernize rules for investment advisors’ custody of client and fund assets, including to address crypto assets.”
“Plan B moving forward at the agency level was always in mind,” Caroline Pham, who served as acting CFTC chairman from the beginning of President Donald Trump’s second term until December, told CNBC. Mr. Pham is currently the CEO of MoonPay Institutional and serves as the Chief Legal Officer and Chief Administrative Officer of MoonPay, a cryptocurrency service provider.
“We need to have contingency plans in place,” she said, explaining that the CFTC and SEC took into account the work both agencies have done since the beginning of President Trump’s second term. This includes the “Project Crypto” initiative introduced in July 2025 to modernize securities regulations and align SEC and CFTC crypto rules.
In August 2025, Mr. Pham announced that the CFTC would begin implementing recommendations from the President’s Task Force on Digital Asset Markets.

Countries target virtual currency fraud
As Washington grapples with crypto regulation, states are also fighting for opportunities to regulate the asset class.
In a Sept. 14 letter, a bipartisan coalition of state attorneys general urged the Senate Banking Committee to vote against the transparency law, arguing that the bill would take away states’ ability to regulate their securities markets.
“We call on the Senate to maintain clarity on each state’s police powers and ensure that each state continues to have the tools necessary to protect Americans from predatory fraudsters,” he wrote in a letter to Scott and the committee’s top Democrat, Sen. Elizabeth Warren of Massachusetts.
Aaron Klein, a senior fellow in economic research at the Brookings Institution, told CNBC that he doesn’t think states are in the best position to regulate domestic and international capital markets.
“I think capital markets regulation needs to be done at the federal level,” said Klein, who was previously a top staffer on the Senate Banking Committee. “The states have a lot of power when it comes to stopping fraud and fraud.”
He said that in the absence of a federal framework for cryptocurrencies, states should more actively monitor payment processing and prosecute perpetrators.
Marsinger pointed out that state enforcement occurs after the crime has already been committed.
“What we really need is oversight on the federal side to make sure we don’t have a situation where the state legislature has to step in and litigate because bad actors are involved or some of the state’s voters have been harmed in some way,” she said.
Although the midterm elections are now center stage, lawmakers have not completely abandoned transparency laws. Sen. Thom Tillis, RN.C., amended his vote against the bill to allow for a motion to reconsider the bill in the Senate.

