
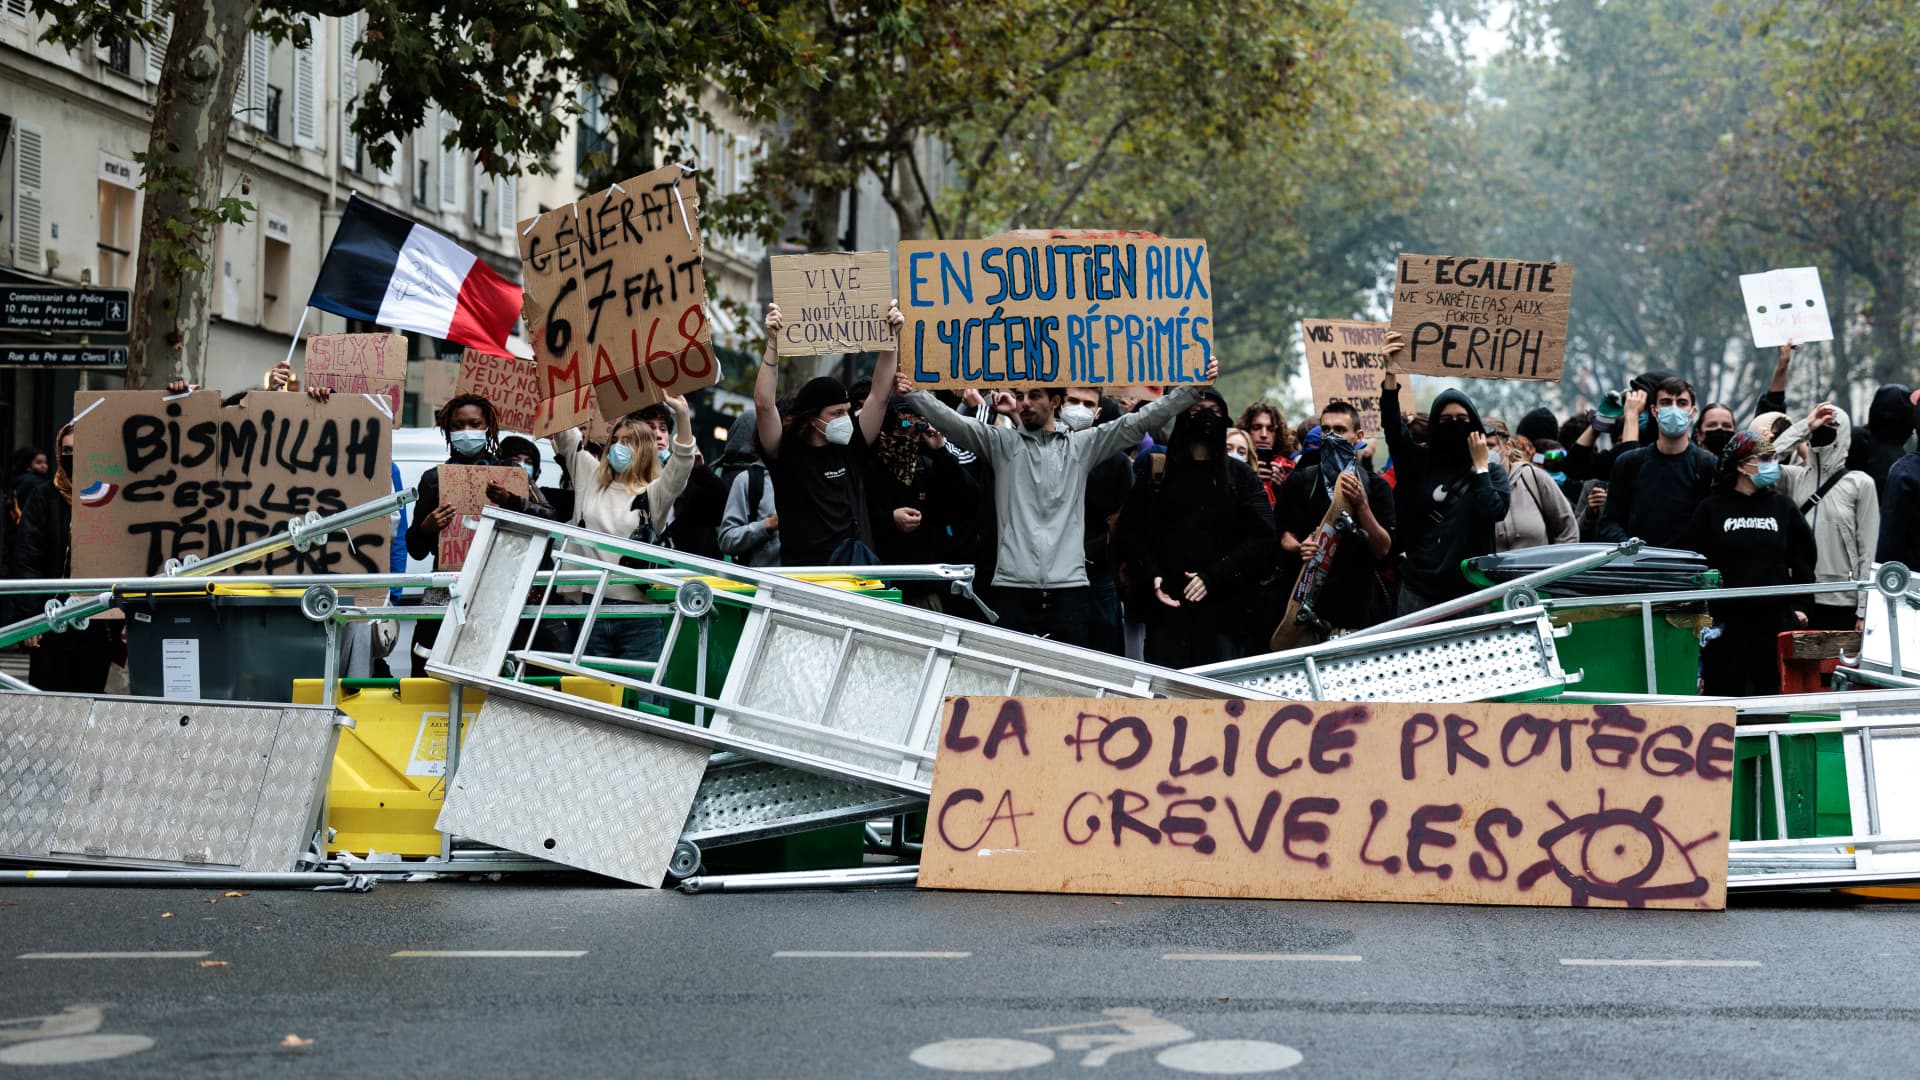
On October 7, 2026, in Paris, Ile-de-France, students gather near the political science department to prevent entry, while other students join in the high school protests and high school blockade.
Gautier Bedrinyan | AFP | Getty Images
France will release 10 million barrels from its strategic diesel stockpile to ease cost-of-living pressures, Prime Minister Sébastien Lecorne announced on Wednesday, in a bid to quell public unrest amid mass protests over lack of education funding.
Lecorne said in a televised speech that the protesters’ anger “didn’t come out of nowhere” and acknowledged that people were feeling “fatigue” over the crisis.
Lecorne said pump prices would fall by 12 to 18 euro cents per liter of diesel as French diesel stockpiles purchased before the U.S.-Iran war caused global energy prices to soar were released at cost.
The G7 countries, of which France is a member, agreed last week to release 100 million barrels of stockpiles after the Trump administration urged Europe to deploy them. Turmoil in the Middle East and Ukraine’s attacks on Russian refineries have further exacerbated the global squeeze on refined products, with prices expected to continue rising next year.
On October 7, 2026, as students took to the streets to protest educational conditions in Nancy, France, police intervened using tear gas.
Anadolu | Anadolu | Getty Images
Hundreds of schools in France will be closed on Thursday as many cities go into lockdown following nationwide protests by high school and university students dubbed “Semène Noir” or “Dark Week.” The government suspended the use of stun grenades after a 15-year-old boy’s hand was blown off earlier this week, prompting accusations of police brutality.
Protesters say that years of underinvestment have left France’s schools overcrowded, dilapidated, and under-resourced and understaffed.
France is experiencing widespread discontent over living standards and wages, strained public services, political dysfunction, immigration and security, with the far-right National Rally and the left-wing New Popular Front coalition gaining popularity at the expense of the current centre-right government.
But their complaints come as the Les Corgnes government seeks to rein in public spending to placate a nervous bond market, which has punished France more harshly than many of its peers this year amid a global bond market crash.
France’s benchmark borrowing costs have risen by about 1.26 percentage points this year, the highest level since 2002, while the risk premium over Germany has almost doubled.
The yield on France’s 10-year government bond, known as OAT, rose 3 basis points on Thursday to about 4.9%.

Mr Lecorne is aiming to pass a budget through a divided parliament, which does not have a majority, and includes cuts to public spending of around 43 billion euros ($48.1 billion). Analysts say he could resort to emergency powers to do so, a move that ended up toppling some of his predecessors.
France has had six prime ministers in the past five years, but instability has been exacerbated by the lack of a majority in the 2024 parliamentary elections.
Lecorne said in a speech on Wednesday that the government is taking action to improve fiscal health because “decisions taken today, with a fair share of the burden, will help us avoid more drastic measures in the future.”

“It is the responsibility of Parliament to budget the country, and indeed its greatest responsibility. Therefore, I appeal to your patriotism so that the ongoing debate will lead to the necessary compromises,” Lecorne said, adding that it was important to bring the public deficit to 5% by 2027. This year’s budget deficit is expected to be 5.4%.
National Rally presidential candidate Marine Le Pen, widely considered the front-runner in the 2027 election, boasted of her commitment to fiscal responsibility in a speech earlier this week, claiming her party would bring the overall budget deficit below the 3% threshold within 18 months.
Davide Oneglia, director of European and global macro at TS Lombard, said in a note on Wednesday that markets were “not (correctly) convinced by her promises,” noting that while France’s borrowing costs fell immediately after her remarks, the gap between French and German yields quickly widened to pre-remark levels.
