
For decades, one of Canada’s biggest selling points to foreign investors has been access to the world’s largest economy next door.
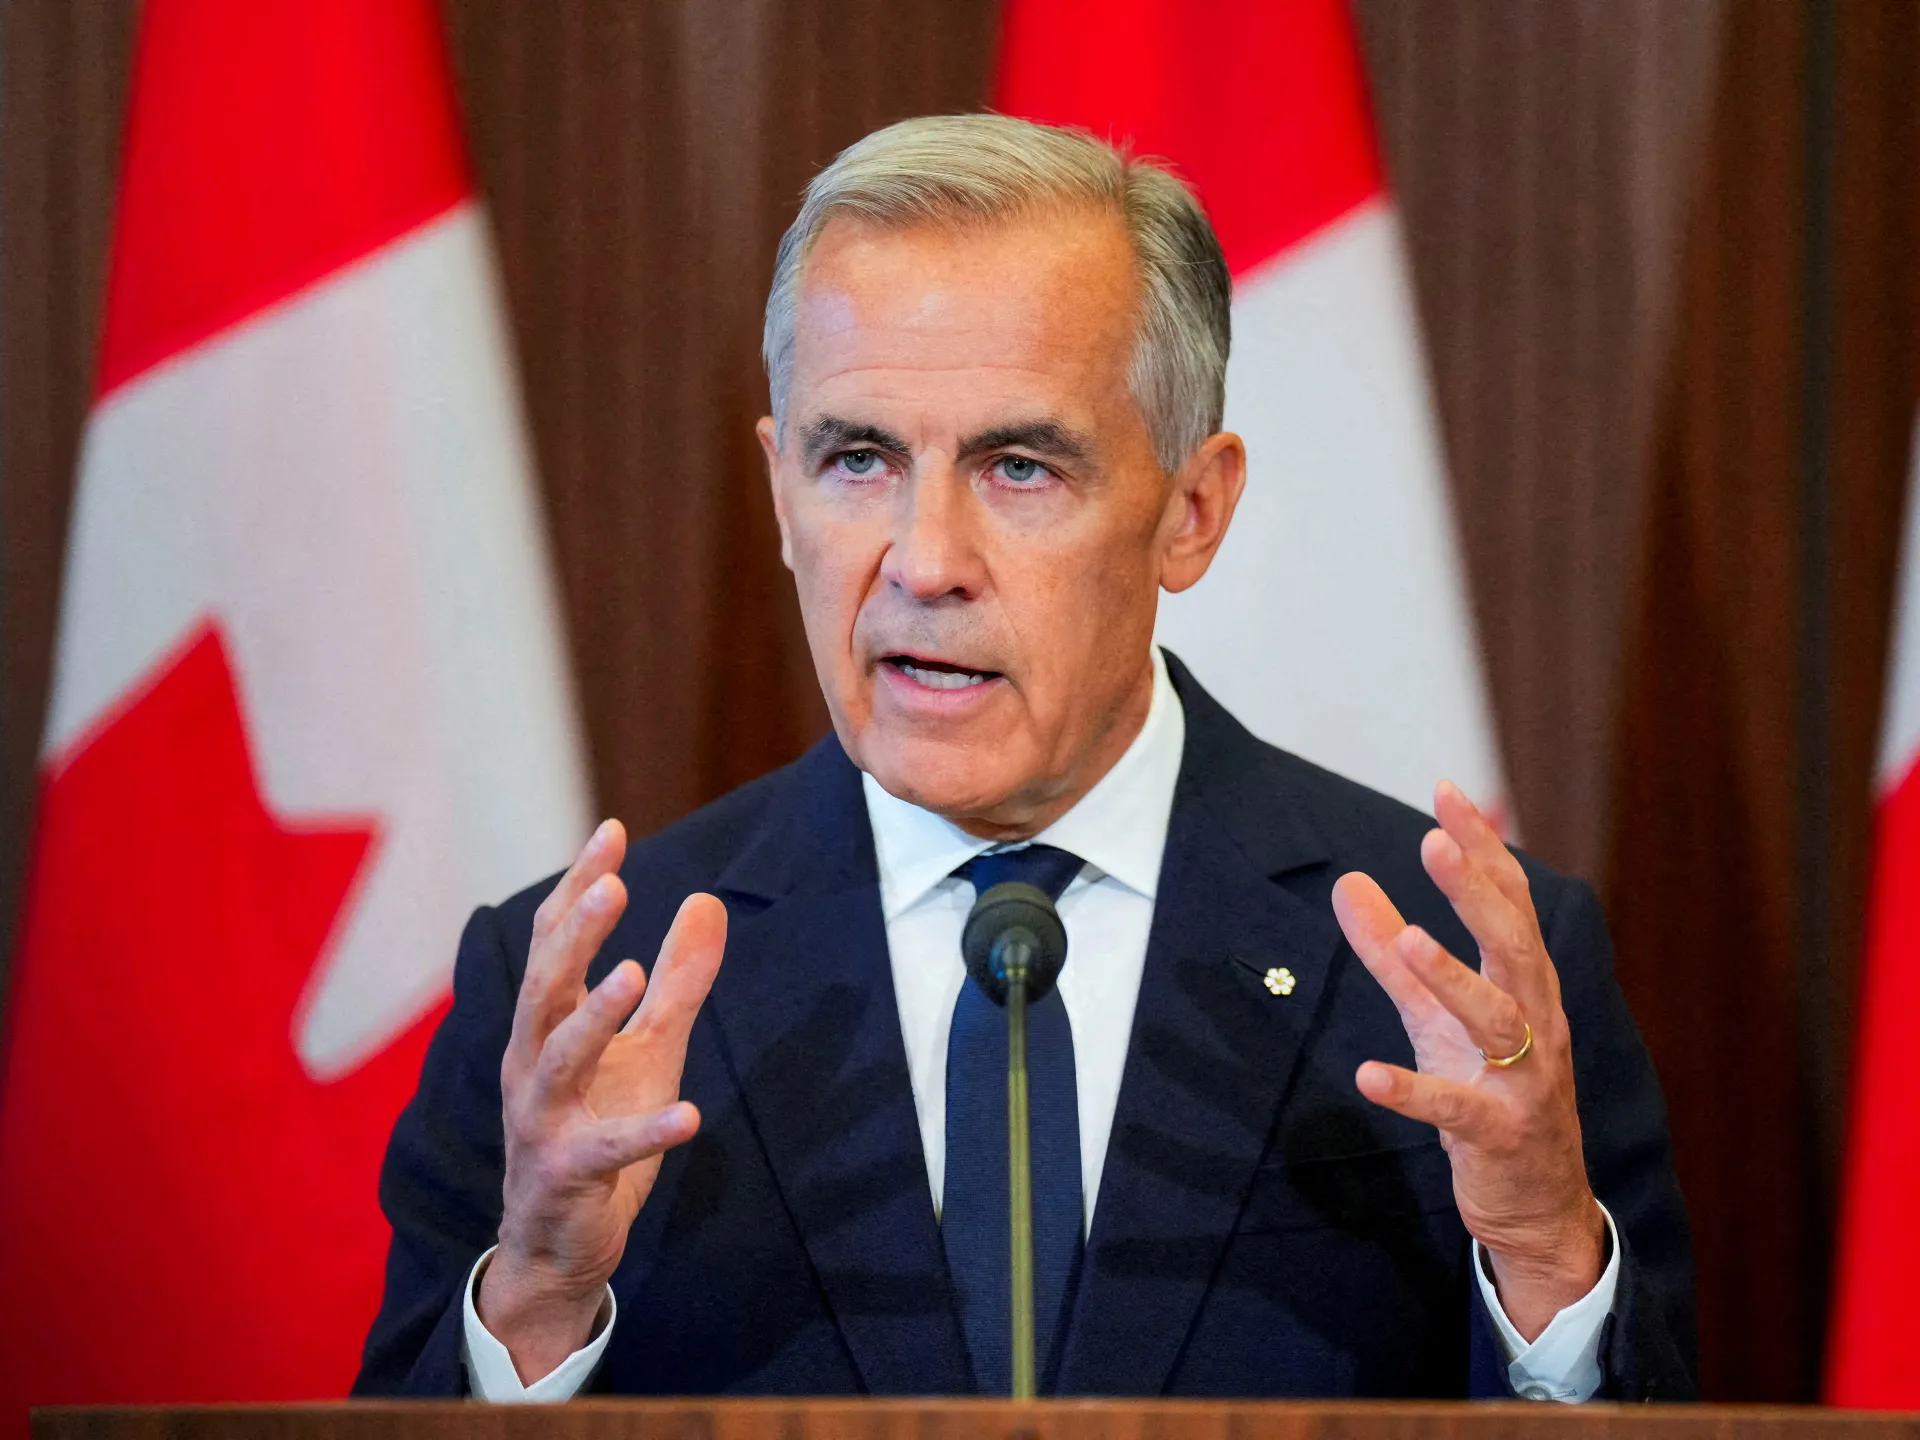
Prime Minister Mark Carney is now betting on something bigger: Canada itself.
Recommended stories
list of 4 itemsend of list
On Monday and Tuesday, hundreds of investors from around the world will gather in Toronto for the Canada Investment Summit. The invitation-only conference will also include the world’s largest pension funds, sovereign wealth managers, business executives, Canada’s prime minister and federal officials.
Carney, a former central banker with deep ties to the global investment community, wants to put money into everything from mines and pipelines to ports, artificial intelligence and advanced manufacturing. This is part of a larger effort to drive $1 trillion in investment into Canada over the next five years, including approximately $280 billion in public investment and government incentives to help attract private and institutional capital.
The summit came just days after the Canada-U.S. trade war, which has been ongoing since President Donald Trump took office for a second term and imposed a wave of tariffs around the world, including on Canada, one of its closest allies historically, escalated again.
Relations have been strained after President Trump repeatedly referred to Canada as the 51st U.S. state and Carney as its “governor.” The threat is particularly damaging to Canada, which before the tariffs sent nearly 80% of its exports to its southern neighbor.
After negotiations broke down last month, Washington imposed 50% tariffs on about $20 billion worth of Canadian goods, and Ottawa is set to impose retaliatory duties of 15% to 50% on the same amount of U.S. imports.
As the two countries continue to negotiate, Mr. Carney has been traveling the world trying to strengthen ties and restart or strengthen trade ties, an effort that bore some fruit with the Toronto summit.
“Mr. Carney is trying to turn a period of external pressure and uncertainty caused by President Trump’s trade war into positive policy,” said Bina Najibullah, co-founder and CEO of the Center for Strategic and National Strategy, a nonpartisan policy think tank in Canada. “Further development at home, diversifying Canada’s economic relationships with the rest of the world, and attracting the capital needed for both.”
In some ways, the uncertainty of the trade war has made Canada a harder sell, but it has also made it more compelling.
“It helps both ways,” Najibulla said. Investors may be wary of projects that rely heavily on the U.S. market. But the turmoil is also an opportunity for Carney to promote Canada as a “relatively stable, rules-based jurisdiction” in an increasingly volatile world.
Mr. Carney drew a large audience to his pitch. Having nearly 300 of the world’s leading investors focus on Canada for two days is unprecedented and a political victory in itself, Najibulla said.
But getting into the room is easy.
“Summits can open doors and build relationships,” she said. “Success ultimately depends on how many of those conversations develop into full-scale investment, funding, and projects that are actually built.”
What does Kearney sell?
He argues there’s more to Canada than access to the U.S. for investors to bet on, from energy to critical minerals, skilled labor and connections to markets around the world. The Canadian government said in a news statement ahead of the summit that through trade agreements with 51 countries, Canadian businesses will have preferential access to 1.5 billion consumers around the world.
“We’re trusted because we’re reliable and we have something the world wants,” Carney said Sunday. “That’s why the world comes to our door.”
A leaked prospectus prepared for the summit lists 167 potential investments across energy, mining, ports, transport, technology and advanced manufacturing.
These range from satellite technology to huge infrastructure projects, such as a proposed oil pipeline from Alberta to the coast of British Columbia.
However, this list focuses on resources and energy. Minerals and metals alone account for almost 38 percent of the project, according to Najibullah’s calculations. If we add energy and power infrastructure, the share rises to almost 70%.
“The summit is fundamentally about financing the physical capacity of the Canadian economy,” he said, citing mining, processing, energy generation, export infrastructure, ports and manufacturing.
However, not all projects are ready for investment. Some of the offerings are fully permitted, while others are still in the concept or feasibility stage.
“Some are so large and expensive that they are unlikely to make it to prime time,” said Rachel Ziemba, an adjunct senior fellow at the policy nonprofit Center for a New American Security.
Canada also needs to prove it can build
Getting big projects that far has long been a challenge for investors.
Ziemba noted that regulatory reviews take time, especially for projects that require both federal and state approvals.
Najibulla similarly cited a “long and uncertain approval process” and questions about whether the project could move from “announcement to implementation.”
“Investors will want reliable pipelines, faster and more predictable permitting, policy stability, clearer revenue models and better coordination across state and federal jurisdictions,” Najibulla said.
Mr. Carney is trying to convince them that things are changing. The government established a Major Projects Authority to expedite approval of projects deemed to be in the national interest, alongside a “one project, one review” approach aimed at reducing federal-provincial overlap.
Ziemba said the summit is an opportunity to show investors how it works. “But this is still in the early stages.”
What do all this mean for Canadians?
Even if Carney funds more of these projects and they get built, there remains a larger debate over who ultimately benefits. In an interview with Democracy Now, Canada’s New Democratic Party leader Abi Lewis criticized the prime minister for “further privatizing our economy by selling off our airports and ports for the benefit of foreign investors.”
This discussion will unfold just outside the summit. Labor, Indigenous, housing and climate groups are planning a rally Monday under the banner of “majority versus money,” arguing that Canada’s economic future should not be primarily shaped by corporate executives and global investors.
The trade war is shifting the focus of Canadian investment from manufacturing and other industries built around North American markets to ports, pipelines and logistics that help Canada’s resources reach new markets.
Ziemba also pointed to another potential tradeoff. These sectors do not necessarily create the same number of jobs and require large amounts of capital. As a result, “the benefits for Canadians looking to replace a U.S.-integrated sector may be limited,” she said.
Even if there’s a big announcement this week, it’s only part of the story.
Ziemba said investors will focus on how much money they actually commit, the timeline and “clarity on who is paying.”
“The summit will help solve the initial problem and show investors what is available,” Najibullah said. “But execution will determine long-term success and whether the capital actually arrives.”
