
Despite the new deal being made to boost artificial intelligence, CNBC’s Jim Cramer said Tuesday that investors should keep the stock independent.
The host of “Mad Money” gave two main reasons for not appearing on the show. Acceleration Holdings: He’s becoming cautious about data center stocks ahead of the midterm elections, preferring established companies with a track record. That’s why Cramer’s Charitable Trust, a portfolio managed by CNBC Investment Club, instead owns stocks in AI infrastructure companies such as gas turbine manufacturers. GE Vernova and electrical equipment suppliers Eaton.
“Acceleration has an exciting story, but I don’t want to jump into this after it’s released on a sob,” he said. “For now, put acceleration on your watch list and see if management can deliver results before pulling the trigger.”
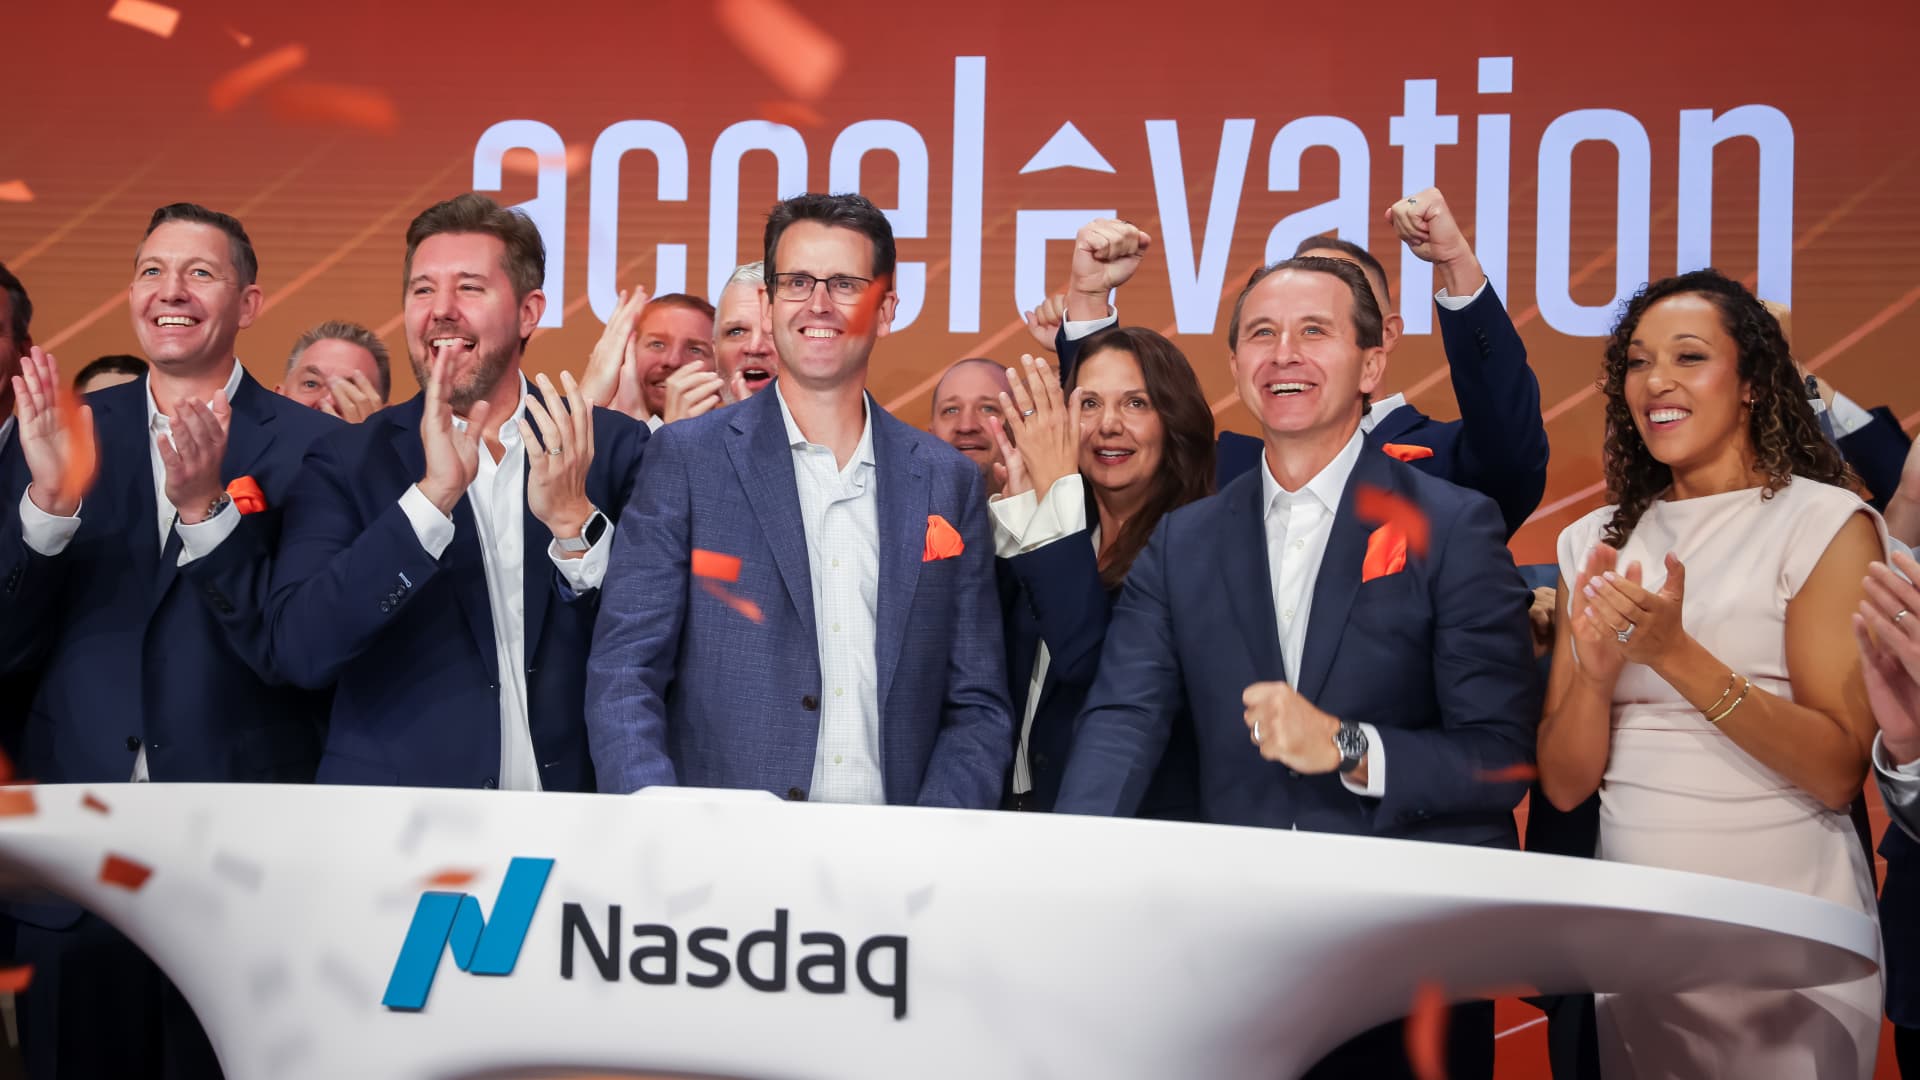
Acceleration, which manufactures and installs electrical equipment, cooling equipment and support structures in data centers, priced its Sept. 29 offering at $18 per share, below its proposed offering range. The stock debuted the next day and closed at $17.95. The price has since fallen to just over $15, marking a disappointing first few weeks for companies benefiting from a surge in demand for AI infrastructure.
Cramer’s first concern goes beyond acceleration. With midterm elections just three weeks away, he expects political opposition to data center construction will continue to be a headwind for the industry overall. Mr. Cramer is reluctant to recommend acquisitions in this area before voters head to the polls, as the massive power demands of these facilities and their potential impact on energy costs have become political flashpoints.
“If you’re looking to acquire a data center supplier, I think you should wait three weeks until after the election, when I expect the political heat to subside somewhat,” he said.
His second concern is specific to acceleration. Although the company’s growth has been impressive, Mr. Kramer is not confident in its ability to consistently turn that demand into profits, especially as it competes with large industrial companies.
Accelevation’s revenue grew 147% in 2025, and sales grew an additional 176% year over year in the first half of 2026. However, during this period, rising labor costs and project inefficiencies put pressure on gross profits. “So it turns out that some of this work was much more difficult to do profitably than they anticipated,” Kramer said.
He also expressed concern about Acceleration’s competitive position, saying: Vertive and Eaton, an established company pursuing overlapping segments of the data center infrastructure market. “There are a lot of different ways to play this story,” he said. “I would rather use something that I have confidence in.”
