
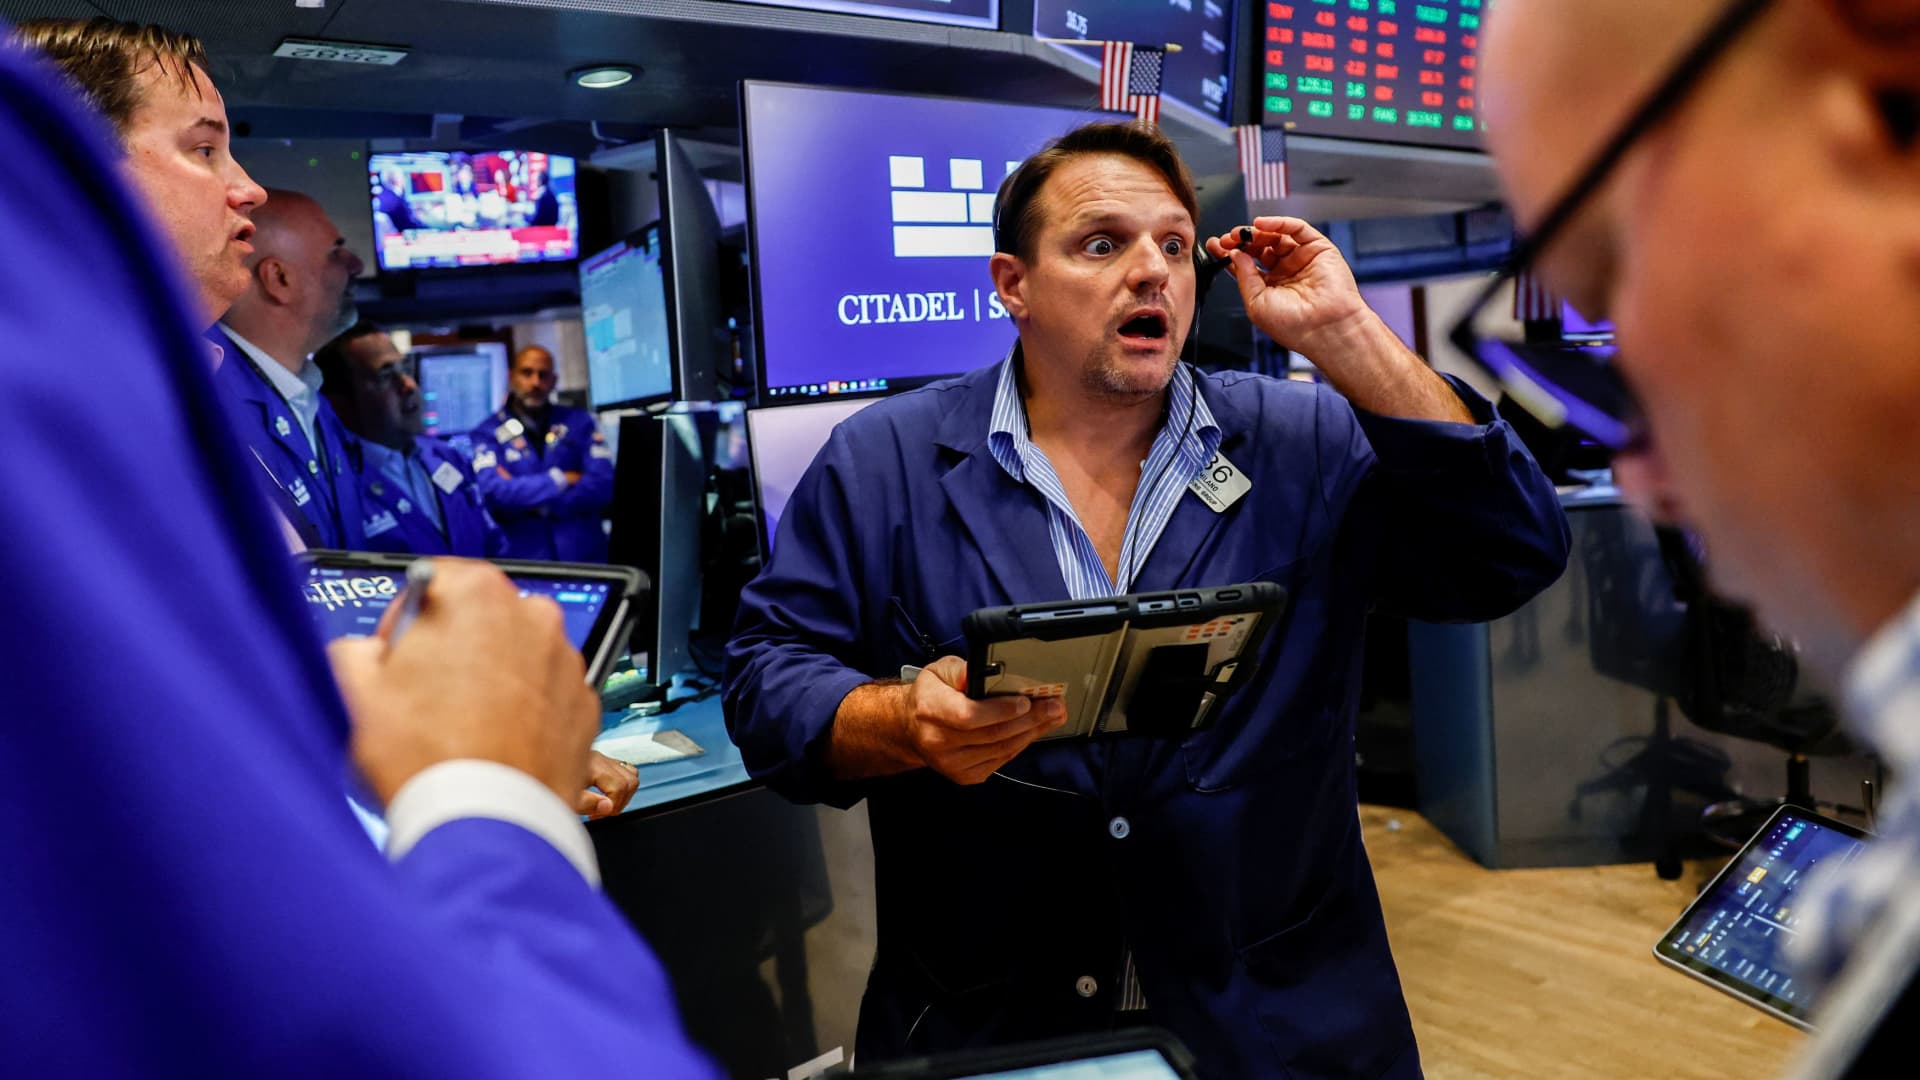
Traders work on the floor of the New York Stock Exchange (NYSE) on September 16, 2026 in New York City, USA.
Gina Moon | Reuters
The US Federal Reserve is tightening monetary policy, and the effects could be felt far beyond the US.
The Federal Reserve on Wednesday raised interest rates for the first time since July 2023 as part of efforts to combat inflation caused by soaring oil prices and other factors, and signaled the possibility of further rate hikes.
Experts told CNBC that a restart of the US monetary tightening cycle could mean a stronger dollar, more pressure on other countries’ currencies and less room for other central banks to ease monetary policy for global markets.
Rising U.S. interest rates could keep global bond yields rising, putting pressure on stock valuations and economic growth.
Mark Zandi, chief economist at Moody’s Analytics, told CNBC that the Fed’s rate hikes and signals of further rate hikes are putting some upward pressure on the dollar and downward pressure on other currencies.
put pressure on the currency
One of the most direct channels through which the Fed’s tightening policies are transmitted around the world is through the dollar.
Key assets such as oil, natural gas and agricultural products are priced in dollars, so rising U.S. interest rates support the dollar while also putting pressure on other currencies.
This is “certainly creating stress,” Zandi said, especially for an economy whose currency and monetary policy are closely tied to U.S. interest rates.
Japan is one of the markets that is attracting attention. A weaker yen could strengthen the case for further tightening by the Bank of Japan, he elaborated. “This will put pressure on Japan to follow suit and continue raising rates,” he said.

Navin Saigal, head of Asia-Pacific fixed income at BlackRock, agreed that the market’s hawkish interpretation of the Fed meeting “could put some pressure on Asian currency and bond markets in the near term.”
A weaker currency could also raise the local currency cost of imported goods, complicating central banks’ efforts to fight inflation.
This comes as oil prices have already risen significantly due to conflicts in the Middle East, and some countries are at risk of a combination of higher energy costs, weaker currencies and higher interest rates.
influence policy
The Fed’s shift also comes as central banks in some major developed countries continue to tighten policy.
The European Central Bank raised interest rates by 25 basis points last week, and JPMorgan Asset Management expects the Bank of Japan to raise rates by a quarter of a percentage point this week.
“Central banks in developed countries are in line with monetary tightening to address inflation concerns,” said Tai Hui, chief market strategist for Asia Pacific at JPMorgan Asset Management.
Rising U.S. Treasury yields as interest rates rise also raises the prospect of capital outflows to the U.S. from other markets, putting pressure on central banks to respond.
Still, the Fed’s moves do not necessarily mean a synchronization of global rate hike cycles.
The inflation situation across Asia is unusually different. China and Thailand continue to face deflationary pressures, while inflation rates in Australia and Japan remain above central bank targets. Meanwhile, India’s inflation rate is roughly in the middle of the Reserve Bank of India’s target range, according to BlackRock.
In other words, even if a strong dollar gives policymakers less room to ease, domestic conditions may ultimately outweigh the pressure on the Fed to mechanically follow suit.
Market impact
For the market as well, a prolonged period of rising interest rates will raise the bar for stocks and other risky assets.
Rising government bond yields make fixed income assets more competitive with stocks, but they also increase the cost of financing for companies and reduce the present value of investors’ bets on future returns.
The level of yields may be more important than the speed or orderliness of the rise, said Liz Ann Saunders, chief investment strategist at Charles Schwab. He said the move toward 5% on the 10-year Treasury is largely justified by inflation, expectations for Fed policy and strong nominal economic growth.
“If yield movements start to become disorganized, I think we’re going to have a bigger problem digesting the stock market, but I think the economy and the market can handle this to some degree if order is maintained,” Saunders told CNBC.
It is also unlikely that the pressure will be evenly distributed. Saunders said higher interest rates were already hurting more cyclical areas of the market, while strong earnings supporting employment could complicate the inflation outlook.
JPMorgan’s Hui said if the Fed remains hawkish through 2027, investors may need to reassess valuations, especially for technology stocks, which are relatively sensitive to interest rates.
Rising US interest rates are only one side of the global market equation. The resilience of the U.S. economy, which has given the Fed room to tighten, could support export demand and business activity in other regions as well.
BlackRock’s Saigal said strong U.S. growth will continue to fuel global activity, trade flows and business fundamentals across Asia, even as rising interest rates create short-term pressures.
