

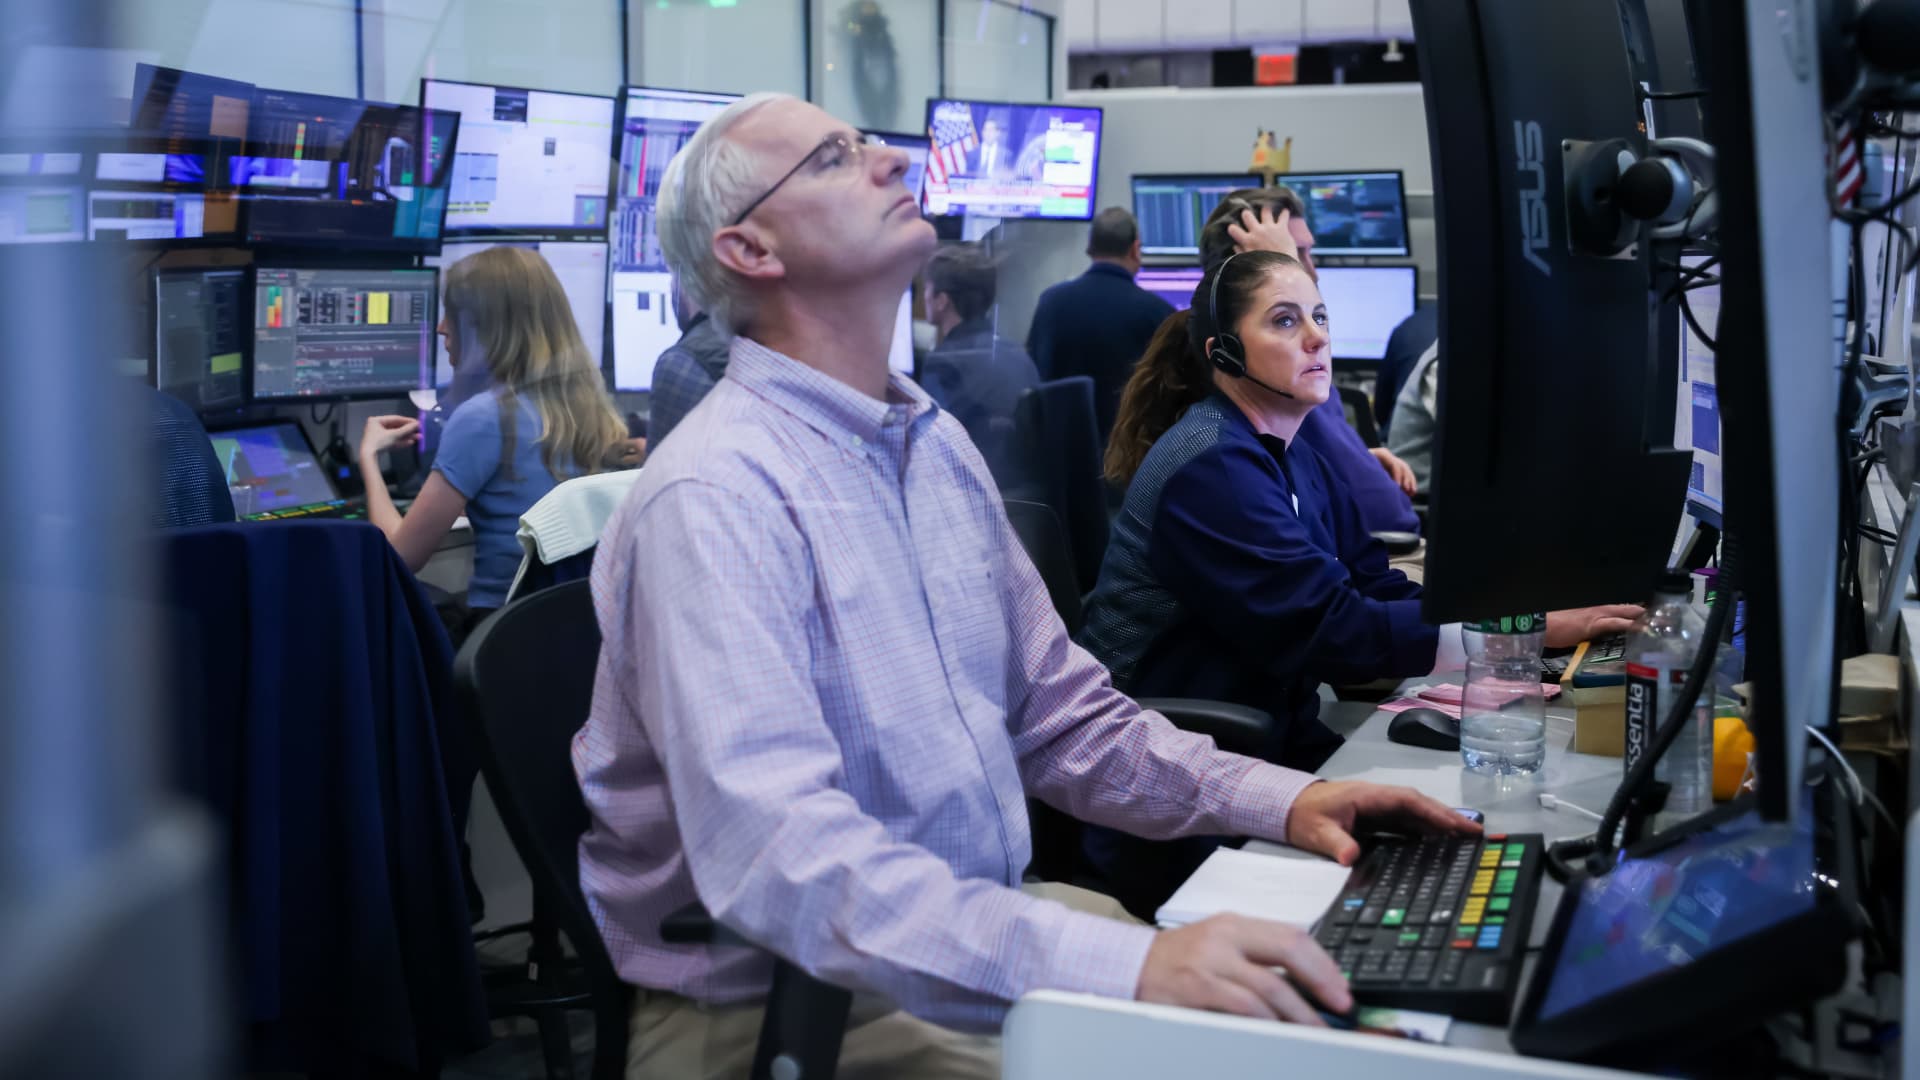
Traders work on the floor of the New York Stock Exchange (NYSE) on Wednesday, October 28, 2026 in New York, USA.
Michael Nagle | Bloomberg | Getty Images
On Friday, stocks ended their worst week since June, but a group of the most sophisticated options analysts agree that options market reaction has been oddly muted.
on the other hand, CBOE Volatility Index (VIX)The so-called fear index reached its highest intraday level since April on Friday, but quickly fell back to close at 19.4. The rollover is S&P500 It ended the day down nearly 2%. Brent Koczuba of Spot Gamma said the 2.2 point move in the VIX was “relatively modest” for such a drop in stocks. His analysis looked at 126 declines since 2018, and says the VIX should have risen by nearly 2.6 points.

CBOE Volatility Index, 5 days
Among them Nasdaq 100 indeximplied volatility increased for most option contracts, but there were important exceptions. The price of out-of-the-money 20-50% put contracts rose on a volatility basis after the Oct. 16 selloff, according to data shared by Nasdaq’s Kevin Davitt.
So not only did traders not add to S&P 500 options on Friday, they were especially cautious about which hedges they bought on the Nasdaq. For example, puts were higher on the Nasdaq two weeks ago, according to data from the Nations Index. And the out-of-the-money S&P 500 index is “not being chased at this point,” Nomura managing director Charlie McElligott wrote, indicating investors remain calm in the face of the decline.
“Index options skew has not been particularly responsive to the spot stock declines that have persisted for several days this week, and where it has, it has been driven in part by lower call volume,” McElligott said in a note to clients on Friday.
One reason for the lack of hedging could be that asset managers are selling stocks quickly rather than using options to protect them from further decline.
One of the more popular charts over the weekend came from Morgan Stanley’s Prime Brokerage. Total global equity exposure is down 8% from its recent peak, the biggest drawdown in at least a decade, according to the firm’s data on long-short active managers.
“Long/short has experienced a massive deleveraging event,” said Zed Francis, chief information officer at Chicago-based Convexitas. “You buy short, you sell long. If you’re closer to cash than you were before, you don’t need to hedge. I think this is the main reason why implied volatility remains quiet in months of increased stress.”
