

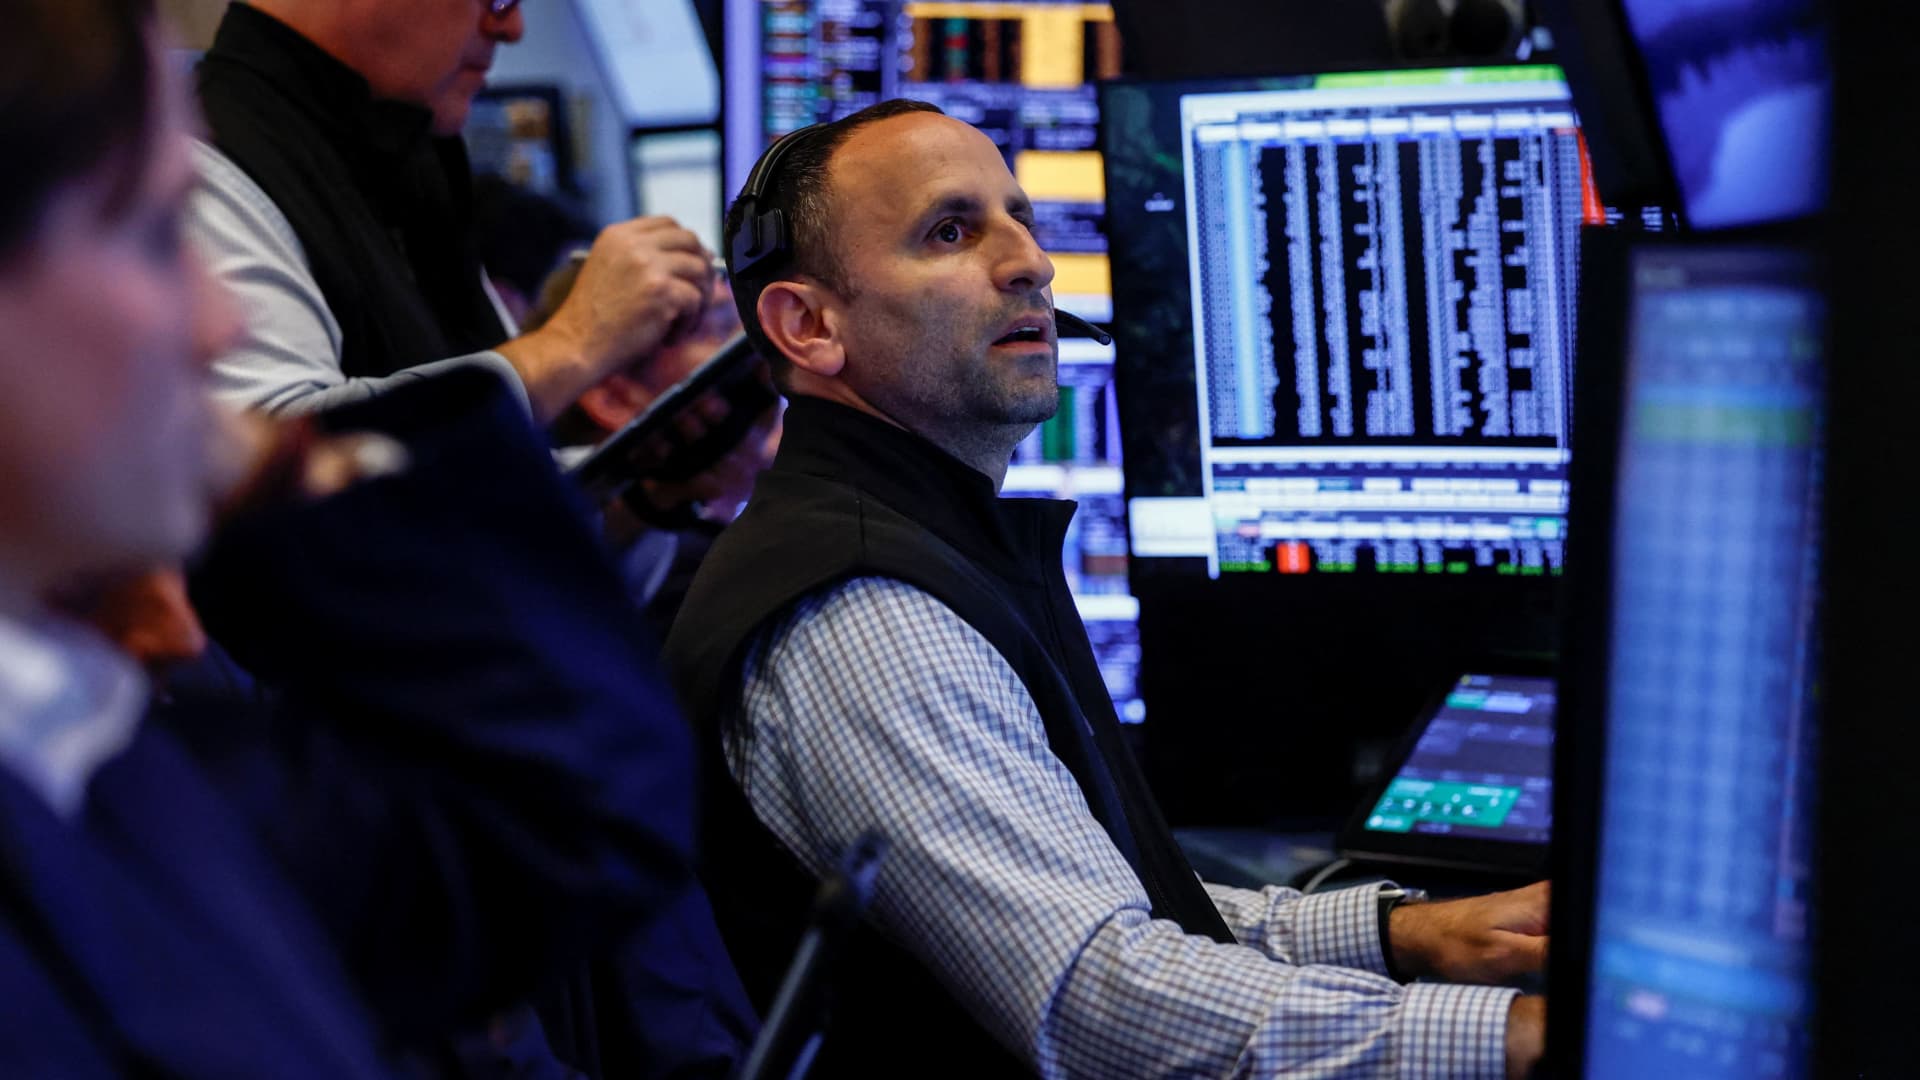
Traders work on the floor of the New York Stock Exchange (NYSE) on November 4, 2026 in New York City, USA.
Gina Moon | Reuters
Whether it’s a referendum on the midterm elections or a continuation of the semiconductor bear market dating back to the group’s peak in June, one thing is clear from Thursday’s options trading. Few traders saw it coming.
This is clear from the rapid increase in CBOE Volatility Index (VIX)up 5.7 points about 90 minutes after Thursday’s opening bell, topping No. 28. This was the highest level for the VIX index since March 31, the day after the S&P 500 sold off and hit its bottom as tensions between Iran, Israel and the United States reached a fever pitch.
The VIX rose more than 11 points from Thursday’s intraday low to high, marking its biggest single-day change since April 9. But given the 3% decline in the S&P 500, some argue that volatility should be higher. Traders use the rule of thumb that 16 points on the VIX equals a 1% change in the index.
The S&P 500 index was headed for its steepest decline since April 2025.

CBOE Volatility Index Year-to-date
“My data says risk aversion, but my gut feeling is that this is a crash that could create a bull-buying opportunity,” Noel Smith said. “I don’t think macro factors like oil or interest rates are causing this. Those things are relatively unchanged. The tape looks like a liquidation, and from what I’m hearing about hedge funds, that’s exactly what it is.”
Wednesday’s reaction to the decline in semiconductor stocks will add to the worries for traders who noted that the VIX index was too calm despite Wednesday’s selloff in tech stocks. and VanEck Semiconductor ETF According to data from the X account OddStats, it was the first time in market history that the VIX fell by more than 4 points at the same time.
As of midday, the VIX index had about 800,000 call trades, 3.5 times the 30-day average, according to Cboe data.
