
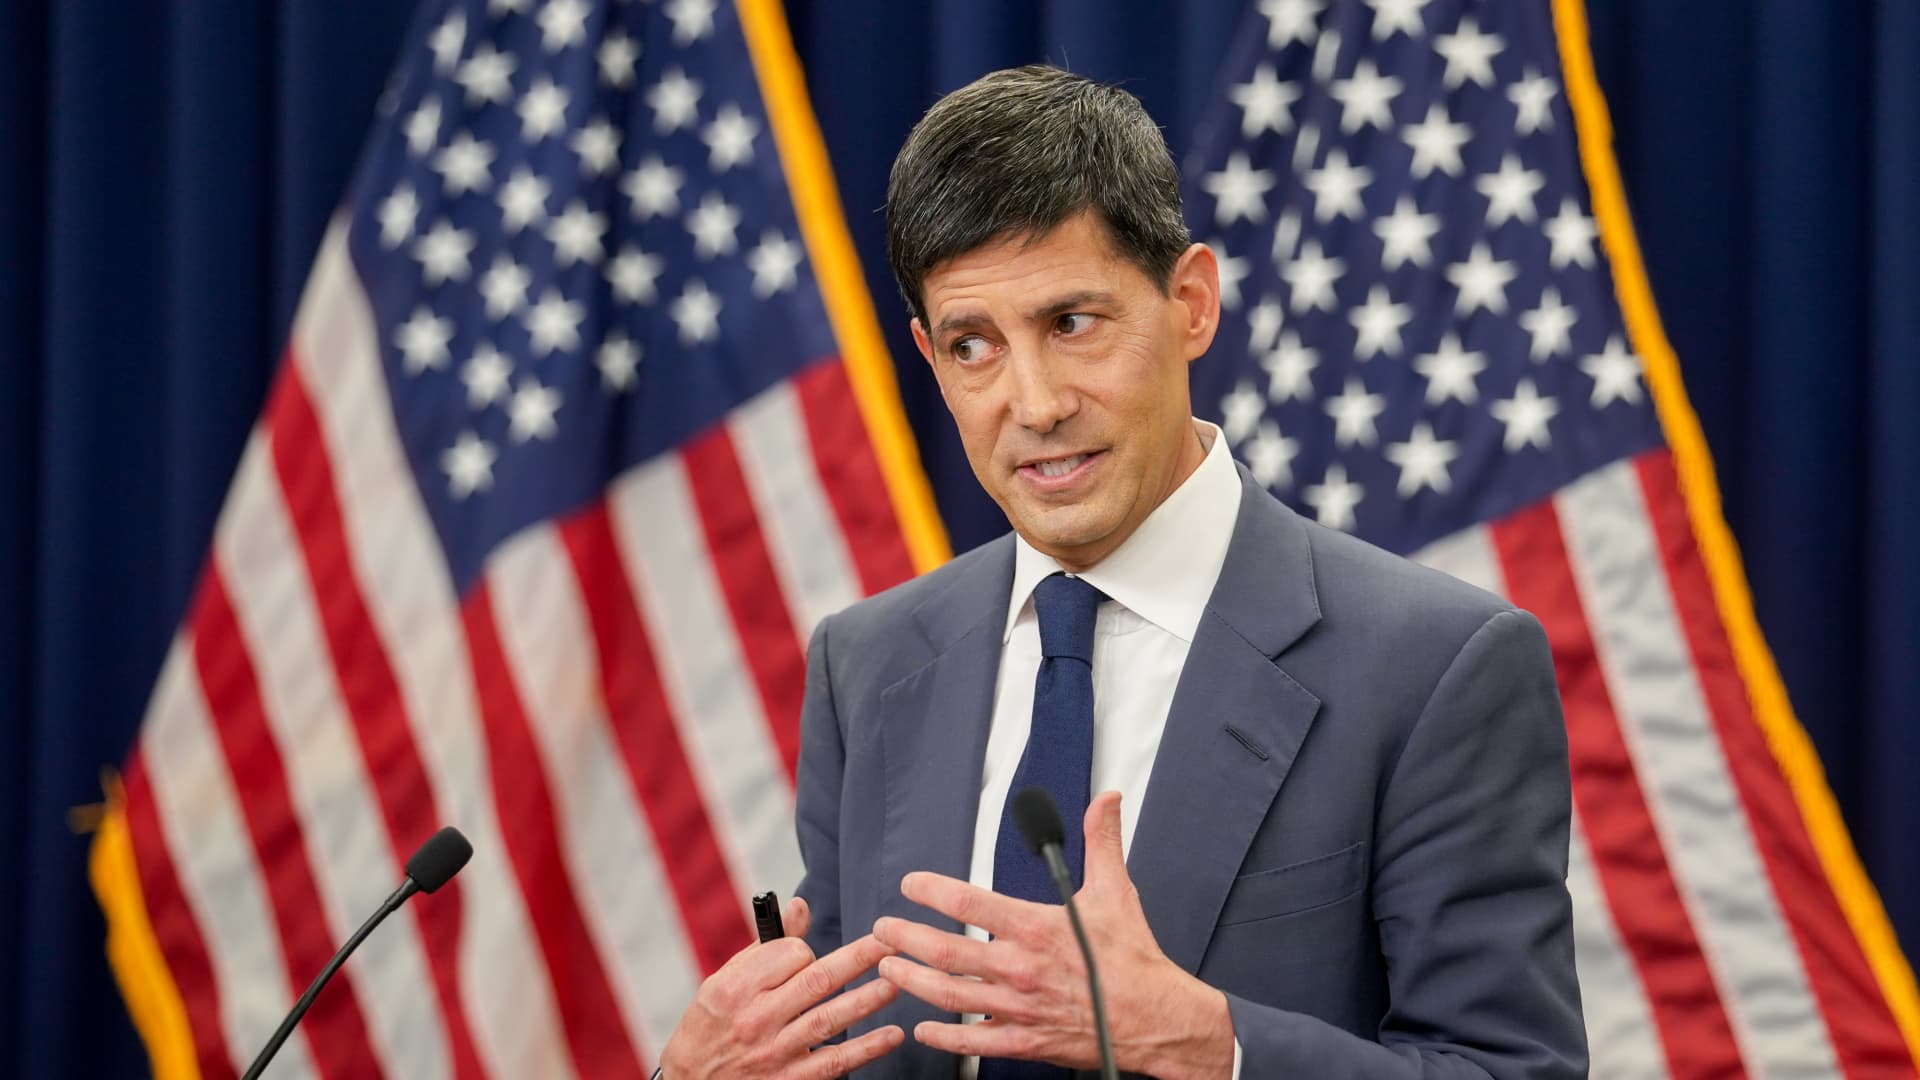
Federal Reserve Chairman Kevin Warsh faces a difficult crowd this week as he and policymakers decide on the immediate and future direction of interest rates.
Markets are focused on Wednesday’s vote, which will almost certainly see a quarter-point rate hike, but it’s far from clear how wide the gap will be among the 12 voters on the Federal Open Market Committee.
Additionally, Chairman Warsh will have to decide how to communicate this move. Will this rate hike be an unusual one-and-done move, will there be more in the future, or will the chairman maintain his mysterious stance of not trying to steer the market in either direction?
“With the market priced in like this, it would be shocking if he stepped in and did nothing,” former New York Fed President Bill Dudley said in an interview with CNBC. “It would be a huge loss to his credibility because it would basically be all talk and no action.”
In fact, as of Monday afternoon, futures traders were pricing in a more than 92% chance of a rate hike this week, and a more than 75% chance of the FOMC implementing further policy measures in December, according to CME Group FedWatch metrics. The federal funds rate, the benchmark overnight borrowing rate, currently ranges from 3.50% to 3.75%.
That possibility becomes even more likely after last week’s renewed fuel price and inflation data showed prices continued to rise in August. Both trends echo Mr. Warsh’s comments several weeks ago that the Fed would be forced to act unless there were more concrete signs that inflation was returning to the central bank’s 2% target.
However, there are considerable complications.
Wait or act?
First, the Fed has historically looked at the types of trends that are currently accelerating inflation. Economists generally agree that much of this year’s gains are due to energy supply shocks from tariffs and the Iran war, both of which have an uncertain impact on the long-term trajectory of inflation.
“We see no strong economic case for raising funds rates,” Goldman Sachs economist David Mericle said in a client note. “We believe the 2% overshoot is entirely due to temporary factors whose impact is likely to fade.”
Nevertheless, Goldman moved from unchanged to higher rates at this week’s meeting, largely because its economists believe market expectations will force the Fed to act.
Whether the same holds true for the FOMC, which voted 9 to 3 in favor of leaving it unchanged at its July meeting, is another matter.
All three opponents (regional presidents Laurie Logan of Dallas, Beth Hammack of Cleveland, and Neel Kashkari of Minneapolis) supported the quarter-point rate hike the Fed last met two months ago. Assuming their position has not changed and there is nothing in public comments to suggest a change, that means the other four members will have to switch their vote from Hold to Raise.
Perhaps the most closely watched voter is Governor Christopher Waller.
In public remarks on September 3, Waller expressed support for another hold on hold at this meeting, while issuing the usual caveat that he would be watching the data closely to confirm that the disinflationary trend continues. Most of the time he simply encouraged patience rather than rushing the hike.
“What’s the cost of waiting for one meeting? If we raise it by 25 basis points now and have one meeting, it won’t bring it down to 2%,” he said.
Indeed, while the August CPI showed headline inflation running at 3.4%, the core rate, which excludes rising food and energy costs, was at a more moderate 2.4%, down 0.1 percentage point from July.
Waller was not alone in advocating patience. New York Fed President John Williams told CNBC less than two weeks ago that a “wait and see” approach seemed to make sense. Mr. Williams, traditionally considered part of the New York Fed’s influential “troika,” took over as head of the New York Fed and said earlier in the summer that he believed inflation had peaked.
Governor Michael Barr also expressed concern in recent remarks about temporary inflation becoming more entrenched and said he was open to raising interest rates rather than deciding to do so.
FOMC collapse
So who will join the trio of opponents in July?
Warsh is widely expected to be part of the hiking group, given statements he made last month in Jackson Hole, Wyoming. Governor Lisa Cook said in early August that she was “ready to act” to combat inflation. Conversely, Philadelphia Fed President Anna Paulson and Chicago President Austan Goolsby have also recommended a more patient approach.
If that happens, the vice chair, Governor Philip Jefferson, will remain. Former Fed Chairman Jerome Powell has taken a decidedly low profile since leaving the top job, while Michelle Bowman said little about monetary policy over the summer and last made relevant comments in May, when she also voiced concerns about unnecessary interest rate hikes.
Then there’s the even bigger wild card. If Mr. Warsh presses forward with Hiking’s case, will those on the fence simply cross over to his side to present a united front?
The difference in votes not only reveals the extent to which intellectuals are divided within the committee between those who think inflation is temporary and those who think price pressures are becoming entrenched. It would also be an important signal about how effectively Mr. Warsh’s leadership is reverberating within the Fed.
“It’s important to note that even if the Fed does indeed raise rates this week, it may not seem like a close call in retrospect,” said David Kelley, chief global strategist at JPMorgan Asset Management, in a weekly market note. “If a majority on the committee unites around the decision to raise rates, there is a good chance that others will join in and present a more united front to the people and the president.”
In such cases, Kelly said the final vote could have two, one, or no dissenting voices.
From there, the market will focus on updates to the Fed’s “dot plot.” The grid details the interest rate forecasts of all 19 anonymous meeting participants, but Warsh declined to discuss the latest information for June.
Investors will be watching to see how much confidence there is in two rate hikes this year, and the outlook for 2027. This will also include projections for 2029. The Fed rarely raises or lowers rates once, but rather in cycles, as policymakers consider gradual, one-time rate hikes ineffective.
Assuming Mr. Warsh downplays forward guidance and does not participate in updates, a 10-8 split in favor of a single rate hike could indicate that “some participants may be ambivalent about the first rate hike, and some may wish to avoid further boosting market expectations,” Mericle wrote.
“However, if more participants than we expected see a rate hike this week as a normal response to rising oil prices, AI demand, and the start of a series of rate hikes, we see a risk of a majority of two hikes.”
If there is a close vote within the committee, all eyes will be on Mr. Warsh’s press conference Wednesday afternoon and how the chair communicates the FOMC’s views.
“The Fed needs to explain what it thinks about the economy,” said Dudley, a former New York Fed president.
“Now (Warsh) just has to follow this up with action,” Dudley said. “If he does that, I think that basically solves the problem that he caused in the first two press conferences.”
