
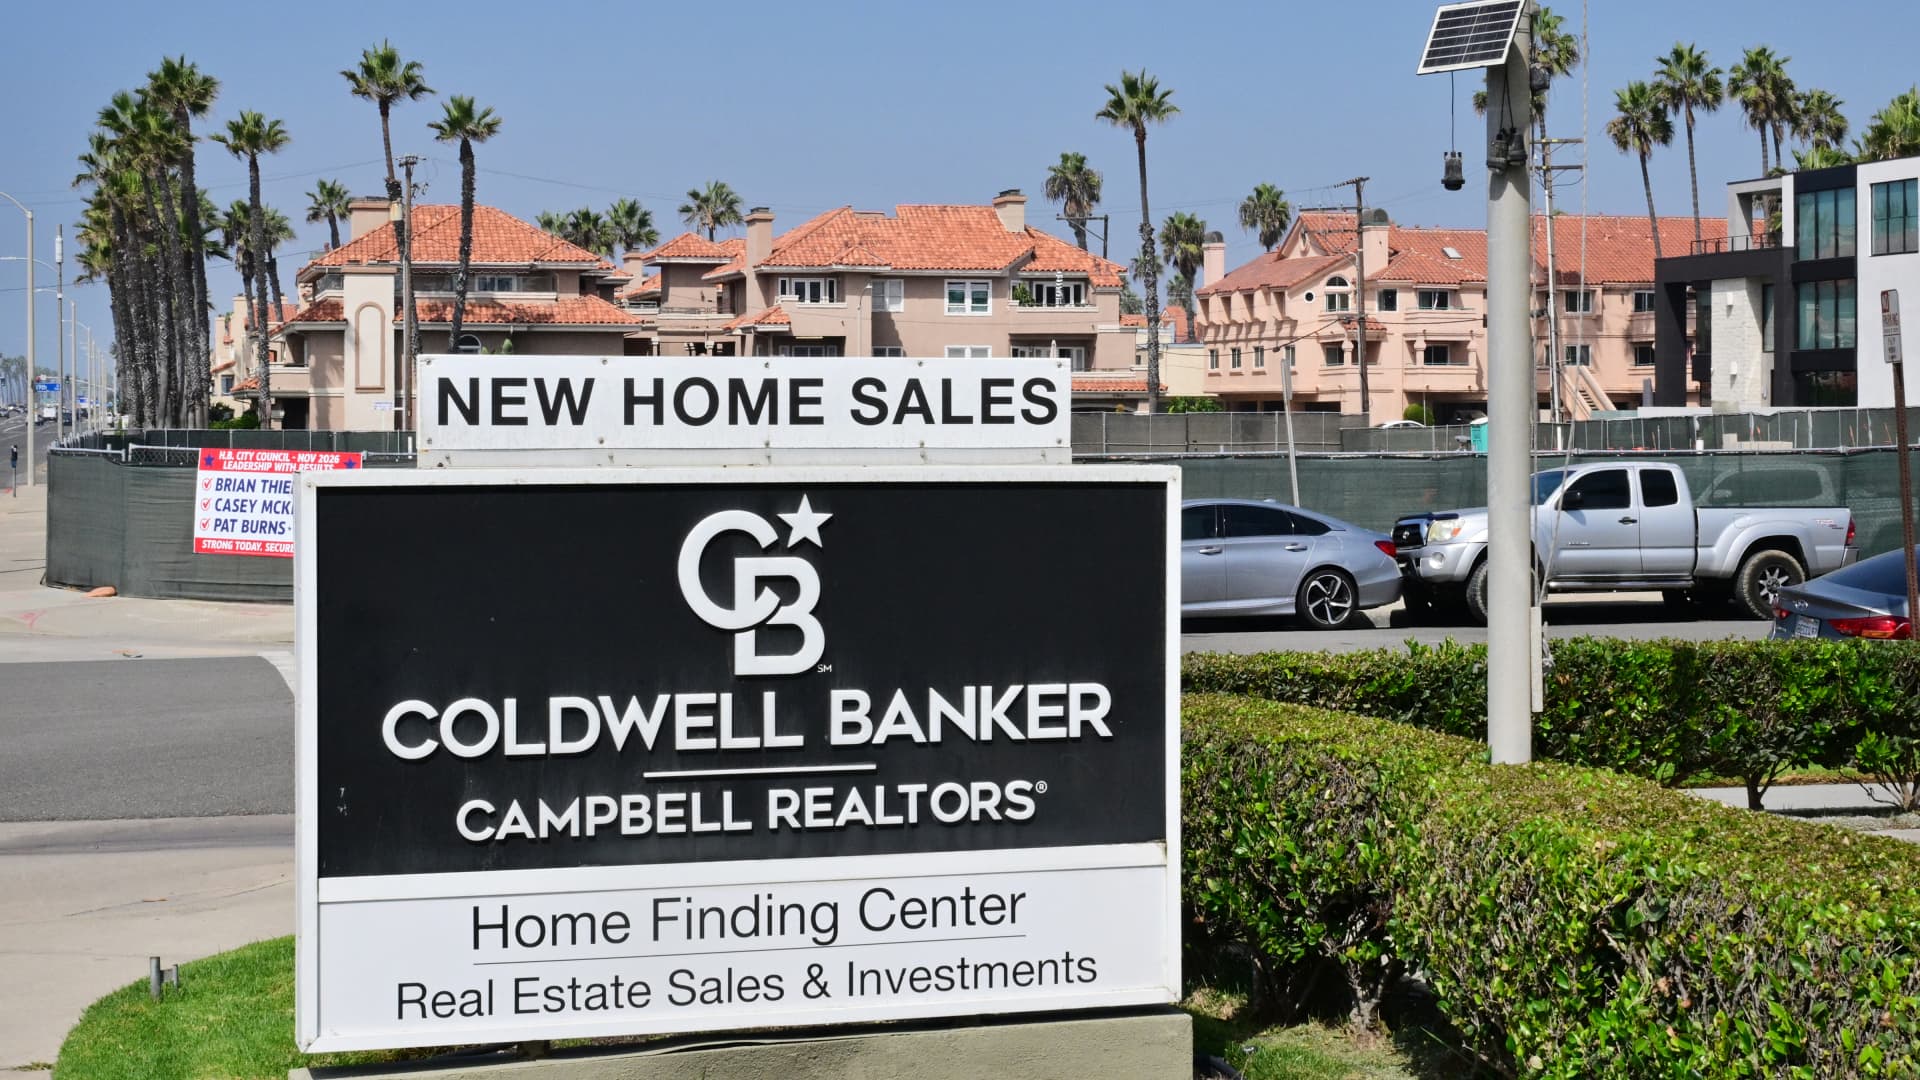
New construction home advertised for sale in Huntington Beach, CA on September 25, 2026.
Frederick J. Brown | AFP | Getty Images
Mortgage interest rates rose last week to the highest level in nearly three years. As a result, demand for both refinancing and home purchases continued to decline sharply and steadily.
Total mortgage applications fell 4.2% from the previous week, according to the Mortgage Bankers Association’s seasonally adjusted index.
The average contract interest rate for a 30-year fixed-rate mortgage with a conforming loan balance of $832,750 or less, including origination fees for loans with a 20% down payment, increased from 7.30% to 7.49% last week, a point increase of 0.75 to 0.84.
Mortgage refinance applications, which are highly dependent on interest rates, fell 8% for the week and 56% from the same week last year. As interest rates rise each week, the pool of eligible refinances shrinks.
“Few homeowners have an incentive to refinance at these rates,” MBA economist Joel Kang said in the release. “With interest rates about 1 percentage point higher than a year ago, refinance applications last week were at their lowest level since 2025 and fell to less than half of last year’s pace.”
The number of applications for mortgages to buy homes fell by 2% during the week, and by 15% compared to the same week last year.
“Purchase activity decreased across all loan types, with FHA purchase applications decreasing the most, down 6%, as rising interest rates further compound ongoing affordability challenges for many homebuyers,” Kang added. “As noted in recent weeks, an increasing proportion of borrowers are choosing ARMs (adjustable rate mortgages) to lower their first payments, with the ARM share holding steady at 10.3% last week.”
Adjustable mortgages have lower interest rates, but can adjust in either direction after a fixed period. That’s why they are considered more risky. For comparison, during the first few years of the pandemic, when fixed mortgage rates were hitting record lows multiple times, ARM’s application share was less than 3%.
Mortgage rates fell slightly this week, according to a separate Mortgage News Daily survey. Although this level is near the highest level since 2003, the average financial institution’s yield is 7.56%, near the lowest level in more than a week.
“What’s causing this? Is this a sign that the recent rally is starting to wane?” wrote Matthew Graham, chief operating officer of Mortgage News Daily. “While it is premature to draw such conclusions, it is somewhat reassuring that Monday’s long-term high was essentially consistent with the high seen on September 30th. This is the kind of ‘double top’ move that some analysts expect when trying to identify a change in momentum.”
